General

Building Wealth: Human Capital vs. Financial Capital

Back in 2003, when I began my career as a young sales manager in the hospitality industry, I earned an annual salary of $26,000. Little did I know at the time that my human capital – as in, the present value of my expected future income throughout my working lifetime – would be worth nearly $3,000,000!

I did some back-of-the-napkin calculations and was surprised to learn I’ve already earned a million dollars over my 15-year career. I find that incredible, given that I’ve never earned a six-figure salary and, in fact, my wages have been stagnant for the past four years.

Projecting my income forward using a modest 3 per cent annual growth rate reveals the potential to earn another $2 million by the time I turn 55.

Human Capital vs. Financial Capital

Put in different terms, however, and you can see that my human capital is shrinking each year. That’s because the value of my human capital peaked the day I started my career (back in 2003) with my entire lifetime of earnings ahead of me. Since then I’ve steadily used up my earning power and the value of my human capital has gradually declined.

The idea of eroding capital doesn’t sit well with me, but that’s where the second form of wealth building – your financial capital – comes into play. See, I’ve been a diligent saver for most of my career, which means converting my human capital (earnings) into financial capital (investments). Continue Reading…

Make & Save: The importance of actionable Personal Finance habits

By Hellen McAdams

Special to the Financial Independence Hub

When it comes to actionable personal finance habits, earning more money and saving a good portion of it are near the top of the list. Sadly though, before you can ascend the tower of wealth, many of us need to first dig out of the basement of debt.

Escape Debt in 5 years

Did you know the average American household has approximately $137,063 in debt? (all figures $US.) That’s too much debt. But what if you were to discover it’s possible for the average household to get out from under the thumb of that kind of debt in as little as five years?

There are several ways to do this. Loan consolidation is a practice whereby you reduce the complication of managing debt by combining everything together. If you have a bunch of little debts that individually compound separately from one another, one possible solution could be to take out a small loan, pay them off, then pay off the small loan in a single payment from then on.

There are online loans of this type which can, believe it or not, be secured online, if you’re considering such.

Still, this is just a debt transition; it doesn’t truly get rid of that which you owe: it merely reduces the complexity of paying a dozen little things off in tiny increments; like cellphones, furniture, and medical bills. A better way to get your debt paid off more quickly is to downsize.

Debt Relief Strategy

This is where you have to establish good financial habits. This hypothetical revolves around $3,000 a month in earnings from the primary breadwinner of the household. That comes to $36,000 a year before taxes. Now say you’ve got $137,000 in debt hanging over your head. You need to find a way to pay that off with the money you’ve got. Continue Reading…

How alternative investments protect your Retirement in a down market

By Matthew Ardrey

Special to the Financial Independence Hub

When I review the portfolio of new clients as part of their financial plan, they almost always have at least one of the following concerns on their mind. They ask how long can stocks continue to climb, given it has been an eight-year bull market or how can their portfolio earn any income with interest rates being so low. More often than not they ask both.

These are real concerns I hear from real people I meet. More and more I am finding that traditional investment solutions are not enough on their own.

Consider how our investment world has changed since 1990. In 1990, an investor could purchase a Government of Canada bond yielding 9.9%, invest in equity markets with a 15X Price Earnings Valuation and lived on average to age 77. In 2017, that same Government of Canada bond yields 1.5%, the Price Earnings Valuation has increased to 22X and average life span is 82 years.

Coping with longer lives, low interest rates and inflation

So the average Canadian investor is now facing a longer life, with fully valued or overvalued equity markets and a fixed-income yield that barely keeps up with inflation even before taxes. Traditional investments can offer little in the way of a solution, especially without increasing the risk profile of my client.

This is where alternative investments can add real value to a portfolio.

Many alternative investment strategies provide yields well in excess of the 1.5% bond yield mentioned above, often averaging annual returns in the 6 to 8% range. The income produced from this part of the portfolio can be used to supplement the low current yields on fixed income.

In addition to return enhancements, alternative investments have a very low correlation to traditional investment markets. What this means is, their performance is not meaningfully impacted by changes in the equity markets. This not only provides diversification, but also portfolio preservation in times of negative volatility.

What are alternative investments? They are any investment that is not a public stock, bond or cash security. Some examples would be private debt, infrastructure, real estate and private equity. They invest in private income oriented investments they can generate stable, high levels of income or by using sophisticated equity hedging strategies to reduce volatility.
Alternatives can have barriers to entry

As with all great things, many investors will wonder, “What’s the catch?” Though there is no “catch” with alternative investments, there are barriers to entry for the average investor. The two main barriers to investing in alternative investments are:

  1. High investment minimums because the investor is not an Accredited Investor (has $1 million in investable assets or $300,000 of income)
  2. Many financial firms do not have the specialized skill set to analyze these investments and thus do not offer them

Though these barriers exist, they can be surmounted by engaging with an appropriate investment counselling firm. The advice provided by an investment counselling firm will allow an investor to access the alternative investment even if not accredited. The firm chosen should have a process to identify alternative investment solutions with proven money managers who have strong track records and a disciplined investment process. Thus, they can engage in the relationship with the alternative investment manager on your behalf.

During the past 30 years, pension plans have been achieving some of the highest returns. It is no coincidence that during the same time period their allocation to alternative investments has also increased substantially to enhance returns and decrease volatility risk.

Institutions have tripled allocation to alternatives

According the annual asset mix report produced by the Pension Investment Association of Canada, which reports on the $1.6 trillion invested by Canadian pensions, the allocation to alternative investments has increased from 10% in 1990 to 33% in 2015. This is an increase of over 200%!

These funds hold the financial future of thousands if not millions of Canadians in their hands. The “smart money” is moving out of the traditional investment world into the alternative one. Now you have the opportunity to do the same.

The world was a very different place in 1990. Brian Mulroney was Prime Minister of Canada, Microsoft released version 3.0 of Windows and The Simpsons first aired on TV. It only makes sense that the investing world would have changed since that time too. If your portfolio isn’t positioned to take advantage of the new investing reality, then my only question is what are you waiting for?
Matthew Ardrey, CFP, R.F.P., CIM, FMA is a VP, Wealth Advisor with TriDelta Financial. He has been providing unbiased advice to his clients on their financial planning and investment management needs since 2000. He can be reached at matt@tridelta.ca.


 

Should buyers make a move in slower Autumn housing market?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

Depending on where you live in Canada, purchasing real estate in recent years hasn’t exactly been a cakewalk. Tight supply and rampant buyer demand (and alleged speculative investing) have pushed home prices to what some experts argue are unsustainable levels in the nation’s hottest markets.

However, following a slew of new policy changes introduced over the last year — such as Metro Vancouver’s foreign buyer tax and the Ontario Fair Housing Plan — those red-hot conditions have changed, with real estate boards from both markets reporting slower sales in the months following.

That’s made a dent in the national numbers, reveals the latest analysis from the Canadian Real Estate Association: with a 11 per cent drop in sales from last September. This is despite the typically busier autumn market, which is often the last chance for buyers to make a serious go of it before the snow — and holiday season — sets in. Seasonally adjusted activity was up slightly month over month at 2.1 per cent.

Too soon to call for market stability: CREA

While this could indicate market conditions are starting to settle after what has been a turbulent spring and summer market, it’s too soon to call it a trend, say CREA’s analysts.

“National sales appear to be stabilizing. While encouraging, it’s too early to tell if this is the beginning of a longer-term trend,” stated CREA President Andrew Peck.

Calmer sales activity hasn’t translated to greater affordability, though: home prices continued their ascent, with benchmark prices rising in 13 of MLS’s tracked markets. It’s the first time in seven years that all markets have seen simultaneous growth, with the national average price coming to $487,000.

However, prices are increasing at a slower pace than at the market’s peak, and that’s mainly due to the lost steam in the detached house segment since March. One- and two-storey single family homes appreciated by 7.9 and 7.2 per cent respectively, compared to the sizzling condo market, which saw 19.8 per cent appreciation, and townhouses at 13.5 per cent.

Continue Reading…

In Victory Lap it’s not about “more money”

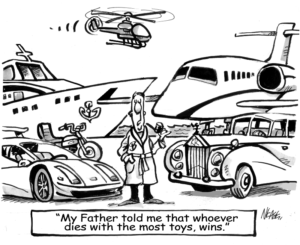
One of Steve Nease’s cartoons from Victory Lap Retirement

My view about money changed once I left the corporate world. “Why?,” I wondered.

Early in my life I was lead to believe money was the most important measure, the one thing that matters on a personal scorecard. I became wired to succeed, earn promotions and win awards. All in the pursuit of “more money,” money for the family, money for more stuff.

This pursuit came at a cost; pressure to produce personal results in a competitive environment doesn’t come without hard work, long hours and time away from the family.

We end up spending more time at work or thinking about work when we are out of the office. We sacrifice time with our families and time pursuing our passions. All that time working in a corporate environment causes you to conform; to become the corporate person somewhere along the way you lose the freedom to be the real you. We trade our true personality in exchange for economic security: a security which in today’s environment is not even guaranteed.

My relationship with money changed when I finally began to feel financially secure late in my career. My priorities changed and I was able to step back and realize that my career was only providing financial security, but little else.

I learned that the worst thing you can do is to spend time working at a job that does not provide fulfillment, all for a little more money. Living, maybe existing is a better word, causes you to lose yourself a little bit each day. You find yourself sitting at work, glancing now and then at your pension statement, trying to hang on for a retirement which if not planned gets you away from work, but still may not be fulfilling.  Sure, you can save a little more for a retirement, but you really have no idea how you will spend your time. The paradox is that for many of us our financial situation is at an all-time high, but the quality of life is at an all-time low.

I was lucky to be “retired” by the Corp.

In hindsight I was lucky to be “retired” by the corp.; it freed me to pursue what Maslow calls self-actualization. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.