General

Do you need to “De-FANG” your portfolio of giant US tech stocks?

Do you need to De-FANG your portfolio or are you so focused on Canada that you’re actually underweight on the big US tech stocks?

My latest MoneySense column looks at the post-Trump surge in tech stocks and the more recent retrenchment in the sector. For the full article, click on the highlighted text here: Do you need to de-FANG your portfolio.

FANG is of course the famous acronym created by Mad Money’s Jim Cramer and stands for Facebook, Amazon, Netflix and Google.

But as the piece goes into in some detail, and per the image above, there are alternative acronyms that include Apple and Microsoft, although not IBM (despite the graphic above).

The question is whether so-called “Couch Potato” type investors who use the MoneySense ETF All-stars already have sufficient technology exposure to participate in the expected long-term growth of technology and particularly Internet giants like Google, Facebook, Amazon and the like. Certainly after last week’s  big announcement that Amazon seeks to acquire Whole Foods, this question is increasingly relevant.

As you’ll see, broad-based ETFs tracking the S&P500 index already have significant tech exposure: roughly a third in these names. Less so for global ETFs exposed to firms outside North America, although these too have healthy exposure to the sector.

Canadian-centric investors woefully underweight technology

Continue Reading…

How to set long- and short-term financial goals

By Angela Baker

Finances are always problematic, and everyone struggles to find balance in this field.

At the beginning of our professional careers, we are on a tight budget with little perspective for any progress. As time passes, our financial goals get higher and desires may seem unrealistic.  There are many ways to plan finances and to set long-term and short-term financial goals. Below, we will try to explain steps for success in this activity.

Define goals and objectives

If you decided to set financial goals, start with clear contemplation about what you need and how you will achieve that. This is the first and most important step. Decide how much money you want to possess each day, month or year. Then after you have determined the amount, start to plan the way for realizing the financial goal.

This may include a new activity like running a website, opening a store, renting houses or finding a well-paid job. No matter what is it, you need a lot of planning and counting. Also, you must research a lot, listen to advice from friends, people around you, and acquaintances. Only with fully-planned action will you be on the way to achieve short- and long-term financial goals.

Identify your financial requirements

The second strategy in setting your financial objectives includes identifying personal needs about money. Everyone spends a certain amount of money daily for basic needs as food, car, hygiene, or meetings with friends. If you live alone, it will be easier to recognize personal requirements because we all know our own needs. Otherwise, if you have a big family and  have to maintain all of them, it will cost you days to count how much money you need. Also, you should not leave out extra spending for a holiday, services in the house, clothes, etc. The final list could make you scared or nervous, but you must face it.

Improve your saving habits

Continue Reading…

Millennial Money: How I deal with my Financial Anxiety

How do I deal with my Financial Anxiety? Other than “I don’t.”

As a ‘mature student’ and a Millennial I find myself really struggling to maintain any sort of enviable lifestyle on a basically non-existent budget. At 25, it feels beyond embarrassing to still be relying on my parents, especially after having had a 1-year contract (in Hong Kong) which kept me self-sufficient. Though it has felt at times like a back-track, I know that in the long run this step back into financial dependence will be worth it.

In discussions with some of my friends, it became clear that I was in no way alone in feeling a little lost and hopeless in the finances department. It has been said time and time again that as millennials, we are meant to be discovering our passions and taking risks with our careers, but clearly all of this does little to dissuade those of us in the midst of these struggles from feeling as if we’re doing something terribly wrong.

Stop comparing yourself to your peers

How am I meant to reconcile these feelings with the facts I know to be true ( it’s just temporary! As soon as you’re finished school you’ll feel so much better about your finances)? One of my closest friends had some helpful words when I came to her with how I was feeling: You have to stop comparing yourself to people around you.

I’m sure that response has elicited at least one “duh!” from this audience, and even I myself am well aware of this simple truth. It is, however, a different thing to actually put into practice.

We’re at the age now where half of us are well into our careers, purchasing first homes, getting married, and even starting to have children. Meanwhile the other half (the camp I fall into) are running around like chickens with our heads cut off trying to find one stable thing in our lives to grab hold of to keep us steady. Continue Reading…

Is a fixed-rate or variable-rate mortgage right for you?


By Alyssa Furtado, RateHub.ca

Special to the Financial Independence Hub

Interest rates in Canada have rarely seen such lows, which makes borrowing money to buy a home pretty attractive. But when you start looking around for the best mortgage rates, homebuyers face a choice of going with a variable-rate or a fixed-rate mortgage.

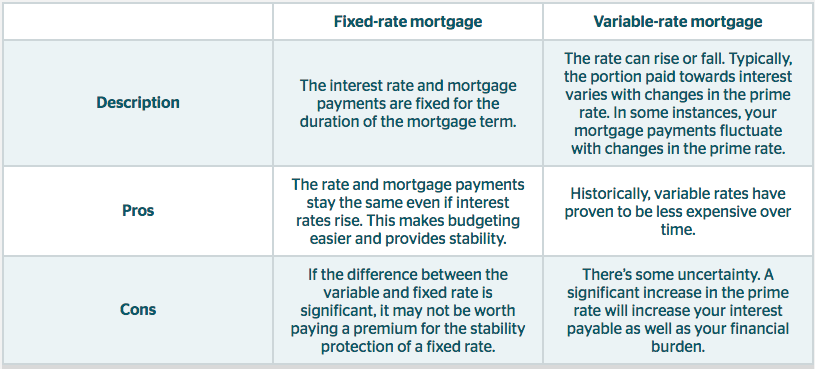
So what’s the difference? A variable-rate mortgage follows interest rates as they move up and down. And a fixed-rate mortgage is locked in for a certain term. Sounds simple, but deciding which option works for you can depend on a number of factors. Here are some essential pros and cons:

Fixed-rate mortgages

Pro: Added security

You don’t have to worry about whether your payments will change because of economic factors you can’t control during the mortgage term. This makes long-term financial planning much easier.

Say you get a five-year fixed-rate mortgage, with a 2.5% interest rate. Regardless of whether interest rates go up or down elsewhere, the rate will stay at 2.5% for the entire five-year period. This allows you to set it and forget it until it comes time to renew your mortgage, at which point you’ll need to renegotiate your rate. At this point your rate could be higher or lower.

Con: Added expense

The luxury of knowing your rate will remain the same will likely cost you, as fixed rates tend to be higher overall.

Variable-rate mortgages

Pro: You can save a bundle

Although by no means guaranteed, historically borrowers save more money over time with this method. Your rate is correlated to the prime lending rate, which can fluctuate. Your rate is quoted as the prime rate plus or minus a certain percentage, such as prime minus 0.4%. In this instance, if the prime rate is 2.7%, your mortgage rate will be 2.3%. Such a small percentage might not look like it will affect your payments, but the savings will add up significantly over time.

Con: Rates can always go up

The variable-rate option comes with a certain risk. If your bank’s prime lending rate changes, the interest moves up or down in conjunction with it. The amount you actually pay your lender on a regular basis (biweekly, monthly, etc.) won’t necessarily change. If the interest rate goes down, more money from your payment will go toward paying down the principal. If the rate goes up, more of the payment will be eaten up by interest, and sometimes your regular payment can also rise. Continue Reading…

The 10 most common Millionaire Habits

By Jessica Kane

Special to the Financial Independence Hub

The ambition and ability that it takes to achieve wealth comes from all kinds of people, but not all from the same locale, upbringing or backgrounds. This begs the question, do rich people have anything particular in common? Well in a sense, yes they do.

Most of the people who have achieved the status of millionaires engage in daily rituals that help them meet their goals. These are primarily activities that engage them in a personal and private way, but many other millionaires share these daily rituals in common with other wealthy individuals.

So for readers who would like to become richer and realize their potential to become millionaires themselves, here are the ten things to consider incorporating into your own daily routine. These 10 daily rituals may be the boost you are looking for to become the next millionaire, or at least a person of better financial means.

1.) Be the Early Bird

Everyone has heard this one expressed by mentors in life, but not everyone takes it to heart like they probably should. Starting early is a common theme when discussing daily rituals with most modern day millionaires. Getting a jump on the rest of the day begins by being awake earlier than the other birds out there. Also, being up early allows more time in the day and more hours to engage in personal activities. This seems to be the most common daily ritual that most millionaires practice.

2.) Maintain a healthy diet

Staying healthy is important, but a lot of people don’t make it a priority. Not the average millionaire: these people understand that a sick day means a non-working day. The more involved in wealth building a person becomes, the more value they place on their personal health and well being. Because if you are not able to get out of bed, you surely cannot make decisions and be there when needed in the business world. So eating right is a first step to being more successful.

3.) Keep fit and exercise

Continue Reading…