General

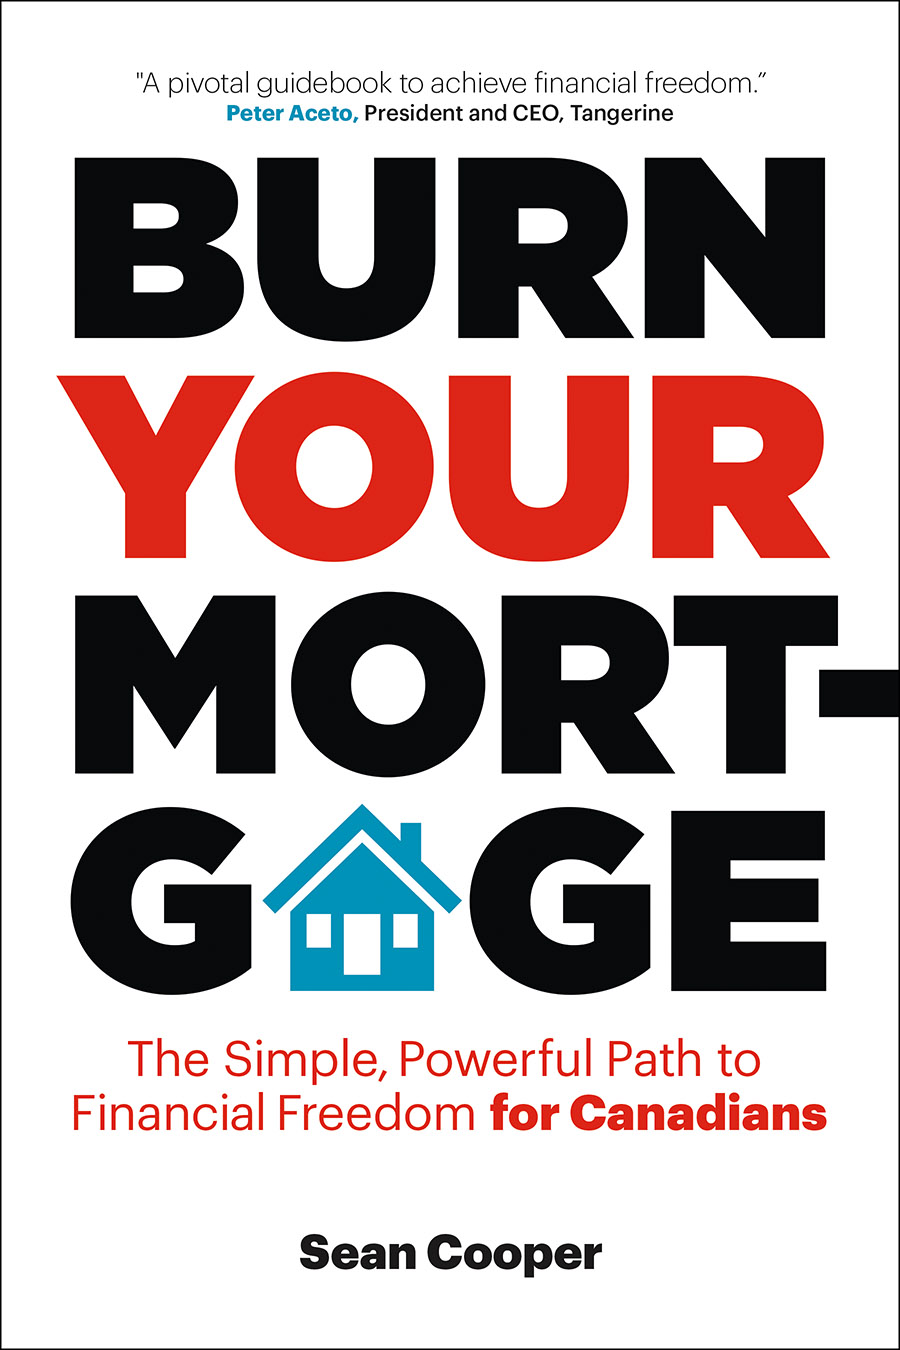
Burn Your Mortgage: The simple, powerful path to Financial Freedom

By Sean Cooper

Special to the Financial Independence Hub

Five years ago I read Jonathan Chevreau’s financial novel, Findependence Day, and it changed my life forever.

One of the central themes of the book is that the foundation of Financial Independence is a paid-for home. I wasn’t a fan of six figures of mortgage debt hanging over my head for the next 30 years, so I aimed to pay off my mortgage as quickly as possible.

A little over a year ago I reached my goal of “Findependence” when I burned my mortgage – literally. I paid off my home in Toronto in just three years by age 30. Thanks to a stroke of luck and good timing, the story went viral, making headlines around the world from the U.K. to Australia. I received hundreds of email from people congratulating me and wanting to follow in my footsteps.

This inspired to me write my new book, Burn Your Mortgage: The Simple, Powerful Path to Financial Freedom for Canadians. With home prices skyrocketing in cities like Toronto and Vancouver, many feel like  the dream of homeownership is out of reach. I’m here to tell you that it’s not. I may have paid off my mortgage in three years, but that doesn’t mean you have to. There are simple yet effective lifestyle changes that anyone — from new buyers to experienced homeowners — can make to pay down their mortgage sooner.

Some people argue it doesn’t make sense to pay down your mortgage early with interest rates near record lows. I see it differently. Instead of using low interest rates as an excuse to pile on more debt, use them as an opportunity to pay down the single biggest debt of your lifetime: your mortgage.

Here’s an excerpt from my book that looks at why you’re most likely better off paying down your mortgage instead of investing. [Editor’s Note: the official launch of the book is today.]

Why pay down your Mortgage when you can come out ahead Investing?
Continue Reading…

When you should NOT invest in an RRSP

Eva Wong, Borrowell

By Eva Wong, co-founder, Borrowell

As the March 1 deadline looms for contributions  to a Registered Retirement Savings Plan (RRSP) this year, many Canadians will be thinking about how much they should contribute to their retirement savings.

Perhaps surprisingly, for many, that number should be zero.

That’s because 30 to 40% of Canadians carry a balance on their credit cards, where many of them are paying 19.9% interest and even more.

To pay 19.9% interest on money that is borrowed, and invest money in an RRSP where it would only earn a return of 6 or 7%, doesn’t make sense.

Let’s say someone had $5,000 to either pay down their credit card or invest in their RRSP, and they chose to put that money into an RRSP. They would pay $995 in credit card interest and earn only $300 in return on their investment, assuming a 6% return

There may be situations where if they had the discipline to use their tax refund to pay off some of the balance on their credit card, it could work out evenly — but that assumes a high enough income to get a significant tax refund and the discipline to use the tax refund to pay off debt.

Paying down debt is a guaranteed return

Continue Reading…

How to Supersize your RESP – Use it as a TFSA and other tips

By Aaron Hector, Doherty & Bryant Financial Strategists Inc.

Special to the Financial Independence Hub

The purpose of this article is to show you how to think outside the box and use an RESP [Registered Education Savings Plan) in ways that you may not have previously considered. But before we get to that, let’s look at the basics.

How does an RESP work?

To help you save for your child’s post secondary education, the government provides a 20% match by way of the Canada Education Savings Grant (CESG). The CESG matching is subject to both annual and lifetime maximums.  Specifically, on your first $2,500 of contributions each year, you’ll receive $500 in grant money, to a maximum of $7,200 in lifetime grants per child. To illustrate over time, if you contribute $2,500 per year, you will max out the grants available to you in 15 years (14 years at $2,500 + 1 year at $1,000, with a 20% match = $7,200).

If you don’t start making contributions when your child is born, or if there’s a lapse in contribution installments, you are able to ‘reach back’ and receive grants for previous years. You can reach back one year at a time. Therefore, you could consider a contribution of up to $5,000 this year if you missed making a contribution last year, or any year prior, and that would net you a CESG of $1,000 in total- $500 for the current year grant, and $500 for a prior year grant. The carryforward of unused CESG accumulates for every year including the year of birth, regardless of whether you have actually opened an RESP account.
Continue Reading…

The Big Dip in Financial Freedom

There is something very wrong with the work world today. It is far too common to find employees who are tired, over-worked, stressed out, and living in fear of an uncertain future.

As a result, people are eating too much, watching too much television, and complaining too much, often self-medicating with drugs and/or alcohol or taking prescription medication to cope with their stress.

How can it be that in North America, with two of the most prosperous societies in the world, people are taking more medications for anxiety, depression, and sleep disorders than ever before?

Blame it on the big dip.

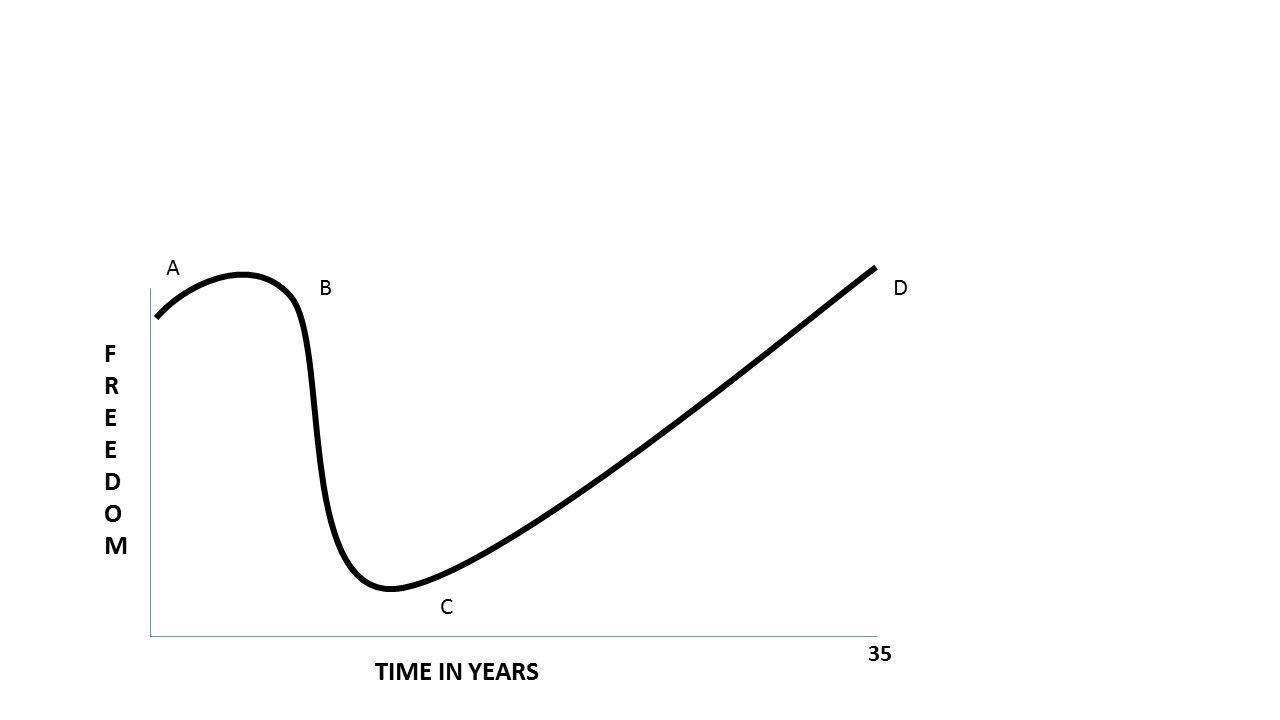
The graph above represents a typical person’s (mine) working lifecycle. I call it the “big dip” as it’s only fair to recognize Seth’s influence on the development of the concept.

You will note two axises, the vertical one representing personal freedom and the horizontal one representing time spent in years. The graph isn’t to scale but it does get the point of the story across. Be warned, it might scare you: it gave me the jitters when I first drew it so you might want to sit down for this one.

Entry point A is when you leave school and start working, maybe in a “corp.,” like I did. It’s a happy time. Life is fun and exciting and you do not have any significant worries. You are finally making some real money for the first time. One could reasonably say a person at this point is financially independent. They carry no personal debt, their parents still provide them with a roof over their head and food on the table. Life is as simple as it could be. Work-Eat-Have Fun-Repeat.

Everyone’s goal at this point is similar. Work hard, get promoted and make more money. This was the path to success as taught to them by their parents and teachers and every kid wants to look successful in the eyes of their parents, right? Continue Reading…

Why it may get tougher for Toronto move-up home buyers

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

It’s no secret the Toronto real estate market is one of Canada’s toughest: scant supply and spiralling prices make it exceedingly difficult for first timers to break in.

However, given the average detached house price has surpassed $1.3 million, according to the Toronto Real Estate Board, it can be even more challenging for buyers needing an upgrade – and a recent City Hall proposal threatens to make it even costlier to move up in the market.

The City of Toronto’s Executive Committee has been mulling over hiking the land transfer taxation rate for the portion of homes valued between $250,000 to $400,000 to 1.5%: a 0.5% increase. The move would effectively “harmonize” the municipal tax rate with the province of Ontario’s, and raise $77 million for the city’s beleaguered budget. It would also equate to a $750 increase on top of the $11,000 already paid in Land Transfer Taxes to City Hall. Enough is enough, argues the Toronto Real Estate Board (TREB).

Double the tax in Toronto

Continue Reading…