Inflation

Inflation

Retired Money: What ETFs are appropriate for retirees?

Photo by Alena Darmel from Pexels, via MoneySense.ca

My latest MoneySense Retired Money column looks at what ETFs might be appropriate for retirees and near-retirees. You can find the full column by clicking on the headlined text here: The Best ETFs for Retirement Income.

I researched this topic as part of a MoneyShow presentation on the ETF All-Stars, scheduled early in September, to be conducted by myself and MoneySense editor Lisa Hannam. Regular MoneySense and some Hub readers may recall that I was the lead writer for the annual ETF All-Stars package but after almost a decade decided to pass the reigns to new writers: this year’s edition was spearheaded by Michael McCullough.

While the ETF All-stars (which are selected now by a panel of seven Canadian ETF experts) are appropriate for all ages and stages of the financial life cycle, a solid subset of the picks can safely be considered by retirees. A prime example are the Asset Allocation ETFs, many of which have been All-Star picks since Vanguard Canada launched them several years back, and since matched by BMO, iShares, Horizons and others.

Generally speaking, young people can use the 100% growth AA ETFs like VEQT etc., or (which I’d be more comfortable with), the 80% growth/20% fixed income vehicles like VGRO. Near-retirees might go with the traditional 60/40 stocks/bonds mix of classic balanced funds and indeed pension funds: VBAL, XBAL, ZBAL, to name three.

Those fully in Retirement who want less risk but a bit of growth could flip to the 40/60 stocks/bonds mix of VCNS, XCON (check) and ZCON (check.).

In theory all you need is a single asset allocation ETFs, no matter where you are in the financial life cycle. After all, all these ETFs are single-ticket highly diversified global plays on the stock market and bond market, covering all or most geographies and asset classes. And their MERs are more than reasonable: 0.2% or so.

A single Asset Allocation ETF can suffice, but consider adding some tactical layers

In practice, most investors (whether retired or not) will want to do a bit more tinkering than this. For one, the asset allocation ETFs tend to have minimal exposure to alternative asset classes outside the stocks and bonds realm. They will include gold stocks and some real estate stocks or REITs, but little or no pure exposure to precious metals, commodities or indeed cryptocurrencies. (Maybe that’s a good thing!).

The MoneySense article bounces my ideas for adding tactical layers to an AA ETF. For example, you might use the 40/60 VCNS instead of 60/40 VBAL, for 80% of your investments, reserving the other 20% for more tactical mostly equity specialized ETFs. You’d aim for a net 50/50 asset mix after blending the AA ETF and these tactical ETFs. Continue Reading…

Was Inflation transitory?

By Dale Roberts, cutthecrapinvesting

Special to Financial Independence Hub

Inflation is coming down in Canada and the U.S. And one can argue that the rate hikes have had little effect. After all, Canadians and Americans are spending money, and employment is strong. The economy has been very resilient. Perhaps inflation was transitory after all, caused by the pandemic and the invasion of Ukraine. This is not the traditional inflation fight script. The economic soft landing argument is getting more support. Was inflation transitory?

Total inflation in Canada is back ‘on target’ in the 2% to 3% range.

That said, core inflation is still sticky.

From this MoneySense post

According to Statistics Canada, the June slowdown was driven primarily by a year-over-year drop of 21.6% in gasoline prices. Meanwhile, the largest contributors to the rise in consumer prices are food costs — which rose 9.1% in June — and mortgage interest costs (up 30.1%).

It’s likely a very good guess that rates are staying higher for longer. The bond market is certainly suggesting that as well.

The 5-year remains elevated.

Fixed-rate mortgage holders will likely be resetting at higher borrowing costs over the next 2 to 3 years – adding several hundred dollars a month to the typical mortgage payment. Of course, that takes money out of the economy and money that would have been spent on goods and services.

Next year may be sunnier than forecast

In the Globe & Mail, Ian McGugen offered a very interesting post. Ian looks to one of the most optimistic economists, and that is a growing group.

Jan Hatzius, chief economist at investment banker Goldman Sachs, has set himself apart from the crowd in recent months by declaring that the United States will not sink into a recession. Continue Reading…

The great migration to Cash: Money Market and Short-Term Fixed Income

Image from Pixabay: Alexander Lesnitsky

By Matt Montemurro, CFA, MBA, BMO ETFs

(Sponsor Content)

One of the biggest trends in the market, thus far in 2023, has been the flurry of inflows ($AUM) into money market and short-term fixed income. We have seen a “great migration to cash” as investors are literally being paid, handsomely, to park cash on the sidelines. We are now 6 months through the year and flows into the short end do not seem to be slowing down. Thus far YTD, we have seen $5.7bln flow into money market and ultra short-term fixed income ETFs, accounting for over 50% of all flows into fixed income ETFs in 2023 (Source: NBCFM ETF).

Money Market and Ultra Short-Term Fixed Income:  after years of being a forgotten segment of the market, how and why are they the leading asset gatherer?

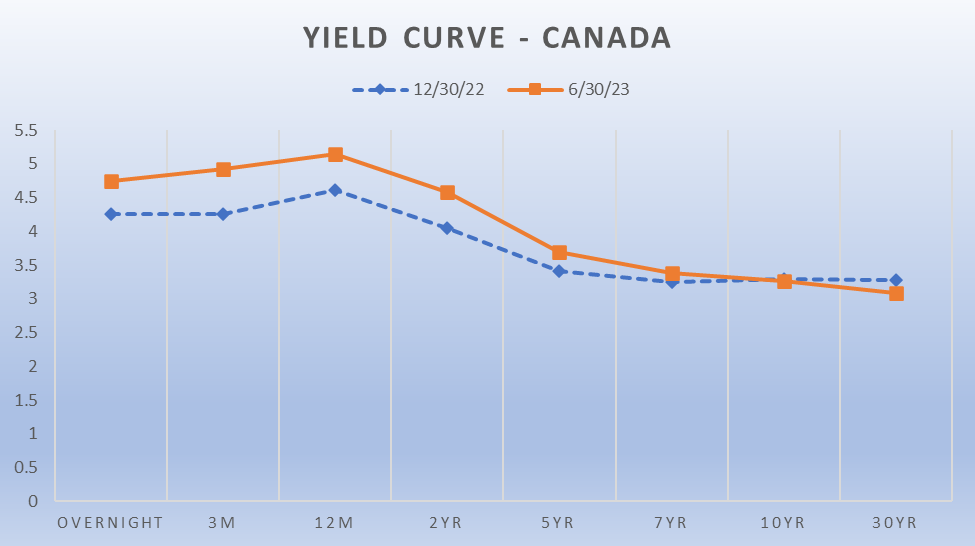
With the accelerated path of rising rates, we have seen in the short end of the yield curve; (the overnight rate) the yield curve inverted. An inversion of the yield curve is caused when shorter-term rates rise faster than longer-term rates. Generally, this is something that occurs but reverses quite quickly.

Not this time. We are currently in a period of a prolonged yield curve inversion, which could be a leading indicator of economic weakness to come. This inversion is exactly what these money market and ultra short-term fixed income investors are looking to cash in on. Lock in higher shorter-term rates and take advantage of the inverted yield curve.

For too long, investors were forced to move outside of investment grade bonds and further out the yield curve to achieve their yield and return expectations. The market has shifted that paradigm on its head and allowed investors to truly get paid to wait on the sidelines in cash.

 Current Canadian Yield Curve

Source: Bloomberg, June 30, 2023

The short end appears to be the sweet spot for many investors, in terms of risk and reward.

Risk: by targeting the short end of the curve, investors will be minimizing their interest rate sensitivity (Duration exposure) and will generally be buying bonds that will be maturing in less than 1 year. Buying investment grade bonds, issued by high quality issuers, this close to maturity provides investors with downside protection as all these bonds will mature at par.[1]

Reward: Achieve a higher yield to maturity than further out the curve. Allowing investors to earn higher yields for lower interest rate sensitivity risk. The current market isn’t paying investors to lend money for longer periods. The front end provides an extremely attractive proposition for investors.

Today’s market is uniquely positioned and many market participants expect volatility to be on the horizon and as higher interest rates make their way through the economy, potentially causing growth to slowdown. Money market and short-term fixed income are well positioned for this environment, as investors can weather the potential volatility in the market while still meeting income and return needs. Continue Reading…

The Four-year Rule: One of the Must-Know Stock Trading rules for Beginners

Are you interested in stock trading rules for beginners? The “four-year” rule is an important one to understand for growing your profits

TSInetwork.ca

Are you interested in stock trading rules for beginners? Most “market rules” turn out to be demonstrations of the fact that random events tend to occur in bunches. The “research” they grow out of generally consists of studying statistics until you find start-and-end dates of periods when a hypothetical indicator would have paid off.

In most cases, if you change the start and/or end dates, the market rules/indicators lose their advantage or go into reverse. Even if you stick with the same start and end dates, the indicator will still go into reverse eventually.

However, the four-year rule is an exception among other stock trading rules for beginners. That’s because it’s based on events that tend to recur in predictable phases of the four-year U.S. Presidential term.

Some statistics are worth a close look

From the election of Andrew Jackson in 1832 till the election of Donald Trump in 2016, the U.S. has gone through 47 complete four-year Presidential terms.

In the first years of each of these 47 four-year presidential terms (starting with the year after the Presidential Election year) the average result for the U.S. stock market was a gain of 3%.

In the second years (the mid-term election years), the annual gain averaged 4.0%. The average result for the third years (the pre-Presidential Election years) was a 10.4% gain. The average for the fourth years (the Presidential Election years) was a gain of 6.0%. (Source: Stock Traders Almanac 2022.)

This pattern probably comes about because of a couple of unchanging things about most U.S. Presidential Elections:

  • First, most U.S. political office holders, regardless of party, want to get re-elected, or pave the way to the election of a successor from their own party.
  • Second, U.S. Presidential Elections bring out many “swing voters” who might not bother to vote in less important elections. They tend to get interested in the Presidential Election because of the torrent of attention it inspires, in the media and in day-to-day conversation.

That’s why newly elected or re-elected presidents often introduce unpleasant necessities in the first year or at least first half of the term. (The best recent example is the need President Trump felt to confront China early in his term.) Swing voters (or voters generally, for that matter) will have had time to get over the shock of the news before the next Presidential Election. In fact, the unpleasant necessities of the first half of the term may have begun paying dividends by the second half. Continue Reading…

Now that interest rates are higher, is it time for near-Retirees to consider partial Annuitization?


My latest MoneySense Retired Money column looks at our own family’s experience in starting to annuitize. Click the highlighted text for the full column: Should retirees in their early 70s partly annuitize?

Apart from the fact interest rates are now closer to 5% than zero, my wife and I are approaching the time when our RRSPs must be collapsed, converted to RRIFs, or fully or partly annuitized. That of course is required by the end of the year you turn 71.

One financial blogger and financial planner was ahead of the curve on rates and annuities. A year ago, on his Boomer & Echo blog, Robb Engen made the case for annuities just as interest rates were starting to rise. See Using annuities to create your own personal pension in Retirement. “Annuities fell out of favour (if they ever were in favour) when interest rates plummeted over the past 10-15 years,” he wrote, “But with interest rates on the rise, annuities are certainly worth another look.”

Engen’s case for annuities revolves around how they minimize longevity risk: the fear many retirees have that they’ll outlive their money. “An annuity provides a predictable income stream for life – much like how a defined benefit pension, CPP, and OAS pays benefits for as long as you live. Nothing protects you from longevity risk quite like having a guaranteed income that’s paid for life.”

 Those who lack an employer-sponsored Defined Benefit pension plan and therefore have hefty RRSPs are particular candidates for annuitization. Yes, it’s true that most Canadians will have some inflation-indexed annuities in the form of the Canada Pension Plan (CPP) and Old Age Security (OAS) but some may feel comfortable transferring a bit of stock-market and interest-rate risk from their own shoulders to that of the insurance companies that offer annuities.

With respect to the interest rate rises of the past year and what it means for annuities, “I agree that the timing is ripe for those approaching retirement,” says Rona Birenbaum, founder of Toronto-based Caring for Clients, a financial planning firm that includes annuities in its recommendations.

 Birenbaum – who is working to help our own family take a partial plunge to annuitization – suggested looking first to non-registered money that could be earmarked for an annuity, as it’s very tax efficient. Alterntively, “using RRSP assets makes sense providing the lack of liquidity doesn’t constrain future needs.”

Moshe Milevsky a fan of “slow partial” annuitization

Famed finance expert Moshe Milevsky, who has authored several books on retirement and annuities – notably Pensionize Your Nest Egg, coauthored with Alexandra Macqueen — told me in an email that “I will say that I have grown to become a fan of ‘slow partial’ as opposed to ‘rapid full’ annuitization, which helps smooth out the interest rate risk and is even more valuable from a behavioral psychological perspective.” Continue Reading…