Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Asset bubbles and where to find them

Vanguard Group

Commentary by Joseph H. Davis, PhD, Vanguard global chief economist

Republished with permission of Vanguard Canada

There’s only one sure way to identify an asset bubble, and that’s after the bubble has burst. Until then, a fast-appreciating asset may seem overvalued, only for its price to keep rising. Anyone who has tried to breathe one last breath into a balloon and finds it can accommodate two or three more breaths can relate.

Yale University’s William Goetzmann learned just how hard it can be to pinpoint a bubble. He found that assets whose prices more than double over one to three years are twice as likely to double again in the same time frame as they are to lose more than half their value.1

Vanguard believes that a bubble is an instance of prices far exceeding an asset’s fundamental value, to the point that no plausible future income scenario can justify the price, which ultimately corrects. Our view is informed by academic research dating from the start of this century, before the dot-com bubble burst.

Are there asset bubbles out there now? We at Vanguard have great respect for the uncertainty of the future, so the best we can say is “maybe.” Some specific markets, such as U.S. housing and cryptocurrencies, seem particularly frothy. U.S. home prices rose 10.4% year-over-year in December 2020, their biggest jump since recovering from the global financial crisis.2 But pandemic-era supply-and-demand dynamics, rather than speculative excess, are likely driving the rise.

Cryptocurrencies, on the other hand, have soared more than 500% in the last year.3 It’s a curious rise for an asset that is not designed to produce cash flows and whose price trajectory seems like that of large-capitalization growth stocks: the opposite of what one would expect from an asset meant to hedge against inflation and currency depreciation. Rational people can disagree over cryptocurrencies’ inherent value, but such discussions today might have to include talk of bubbles.

What about U.S. stocks? The broad market may be overvalued, though not severely. Yet forthcoming Vanguard research highlights one part of the U.S. equity market that gives us pause: growth stocks. Low-quality growth stocks especially test our “plausible future income” scenario. For some high-profile companies, valuation metrics imply that their worth will exceed the size of their industry’s contribution to U.S. GDP. Conversely, our research will show that U.S. value stocks are similarly undervalued.
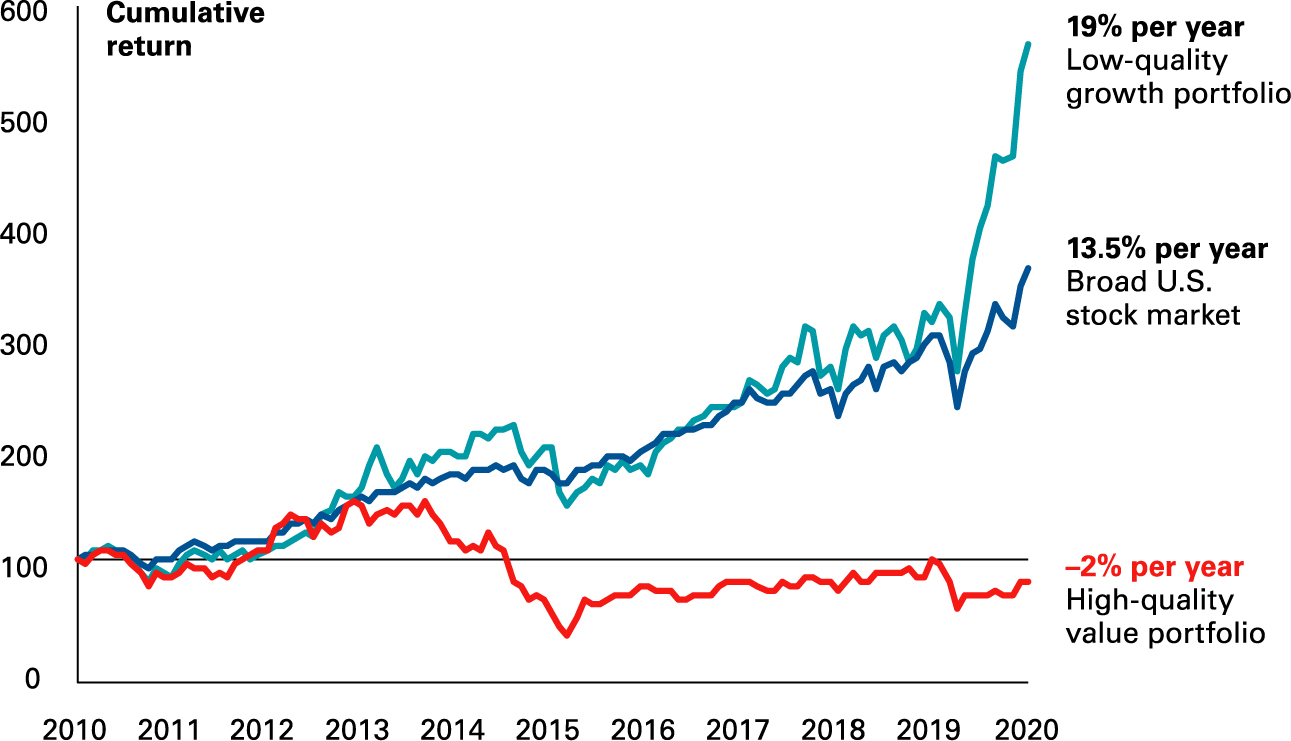
 

Low-quality Growth has outperformed the market


Notes: Data as of December 31, 2020. Portfolios are indexed to 100 as of December 31, 2010. Low-quality growth and high-quality value portfolios are constructed based on data from Kenneth R. French’s website, using New York Stock Exchange-listed companies sorted in quintiles by operating profit and the ratio of book value to market value (B/P). The low-quality growth portfolio is represented by the lowest quintile operating profit (quality) and B/P companies. The high-quality value portfolio is represented by the highest quintile operating profit and B/P companies. The broad U.S. stock market is represented by the Dow Jones U.S. Total Stock Market Index (formerly known as the Dow Jones Wilshire 5000) through April 22, 2005; the MSCI US Broad Market Index through June 2, 2013; and the CRSP US Total Market Index thereafter.
Source: Vanguard calculations, based on data from Ken French’s website at Dartmouth College, mba.tuck.dartmouth.edu/pages/faculty/ken.french/data_library.html; MSCI; CRSP; and Dow Jones.
Past performance is no guarantee of future returns. The performance of an index is not an exact representation of any particular investment, as you cannot invest directly in an index.


Low-quality growth stocks — companies with little to no operating profits — have outperformed the broad market by 5.5 percentage points per year over the last decade. Of course, there are reasons why growth stocks may be richly valued compared with the broad market. Growth stocks, by definition, are those anticipated to grow more quickly than the overall market. Their appeal is in their potential. But the more that their share prices rise, the less probable that they can justify those higher prices. A small handful of these “low-quality growth” companies may become the Next Big Thing. But many more may fade into obscurity, as occurred after the dot-com bubble. Continue Reading…

Gold still trusted over Bitcoin, but gap is closing

A report by LendEDU finds Bitcoin is making a lot of headway with investors over Gold. 56% said Bitcoin is a better investment to maximize profits, versus just 33% for gold. However, they still see gold as a better store of value against inflation, with 50% answering gold  (including 67% over the age of 54), and 39% saying bitcoin.

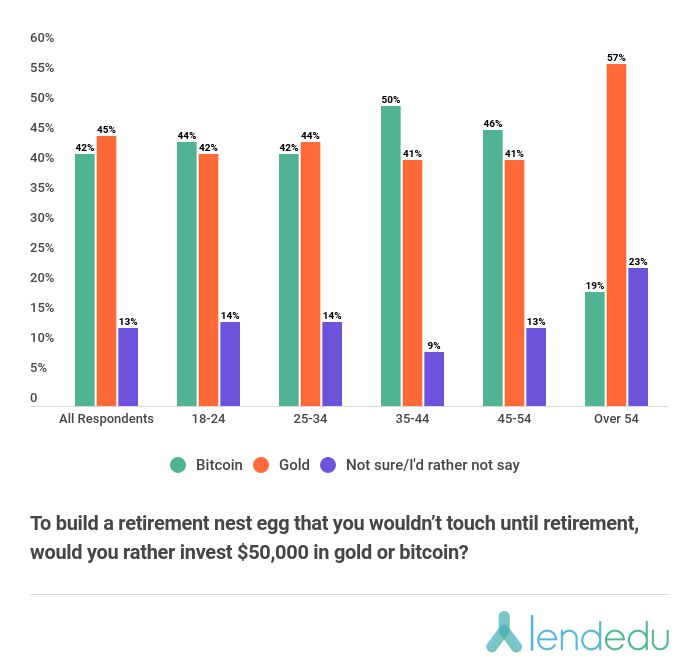
On behalf of New Jersey-based LendEDU, research firm Pollfish surveyed 1,000 Americans on April 21st to see how they would deploy an initial US$50,000 to build a retirement nest egg, and found gold only had a slight edge: 45% versus 42% for bitcoin. However, if the goal of the $50,000 investment is strictly to maximize profits, 49% specified bitcoin, versus just 37% for gold.

LendEDU Director of Communications Mike Brown says Bitcoin is up roughly 68,189,500% since its start in 2009, while gold is up 105% over the same period.

“Gold is proven as a reliable investment and safe haven against market volatility and inflation, which is especially relevant in 2021. Bitcoin is becoming a competitor for just the same thing, although its wild price fluctuations are not for the faint-hearted and attract a younger, more aggressive investor … We found gold is still trusted for more cautious investing, especially amongst older Americans, but bitcoin is closing that gap and is preferred for speculative investing, especially with the younger crowd.”

LendEDU’s Mike Brown

Brown says the survey results were “none too surprising; bitcoin has periods of monumental gain that make it a salivating buy for aggressive investors trying to make a profit. But it also has periods of monumental loss and faces constant regulatory and institutional scrutiny that make it a questionable buy if your first investment priority is protecting the money you already have.”

Gold, on the other hand, doesn’t have eye-popping surges like bitcoin but is safe and has historically delivered steady profits to the patient investor looking for a financial safe haven.

The survey reveals a younger bias towards bitcoin and an older population favoring gold. Thus, 56% of those between the ages of 18 and 24 thought bitcoin was the better speculative asset, while 29% thought gold was. The percentages were 29% and 55%, respectively, for poll participants over 54.

Similarly, 42% of the 18 – 24 cohort thought bitcoin was a better store of value to protect against inflation, while 44% said gold. For the over 54 cohort, those percentages were 16% and 67%, respectively.

Brown found the 35-44 age group surprising as they were quite bullish on bitcoin in all four questions and broke with the normal trend that had older respondents favoring gold and younger ones opting for bitcoin. “This could be due to this demographic getting in on bitcoin in the extremely early stages, around 2010 when they were in their mid-twenties or early-thirties.”

When asked if they have invested in bitcoin or gold recently amid concerns about inflation, 15% had invested in gold, 31% in bitcoin, 15% in both, and 36% in neither.

For retirement investing, gold still holds a dwindling edge

In another part of the survey, poll participants were given four increasing monetary values and asked if they would rather invest each value in either bitcoin or gold to build a retirement nest egg that they couldn’t touch until retirement. In nearly every scenario, gold was the preferred retirement investment choice over bitcoin. Only when $1,000 was the starting amount did more respondents (47%) want to invest in bitcoin over gold (43%).

But as the starting amount went up, so too did the risk, which is likely why respondents switched over to the less-risky, less-volatile gold to start building their retirement nest eggs as the questions progressed. As Brown notes, “Retirement accounts should be stable, and you’ll lose a lot less sleep investing $50,000 in gold instead of $50,000 in bitcoin.”

Even so, no matter the initial investment amount, most age groups preferred building their retirement nest egg through bitcoin rather than gold. For example, 46% of the 45-54 cohort wanted to invest $50,000 in bitcoin compared to 41% who said gold. Continue Reading…

Death and Taxes, Cross-border Style

Dollar Printing: Global Macro Shifts; Franklin Templeton Investments Licensed from Gettyimages

By David Cieslowski, CPA, CA, CFP, CIMA

(Sponsor Content)

As Benjamin Franklin famously wrote, “… in this world, nothing is certain except death and taxes.”  For US citizens, as well as some Canadians who own US assets, the first may be swiftly followed by the second.

In the United States, an estate tax is applied to the transfer of the taxable estate of every deceased  American citizen, resident or non-resident, including green card holders or others with dual US-Canadian citizenship. Even Canadian citizens who have never stepped foot in the United States, but hold US securities or other US assets, could find their estates subject to a tax on situs assets, which are defined as assets with a tangible or intangible direct US connection or location.

The low-down on US estate tax

Estate tax falls into the category of transfer taxes, as opposed to income tax. It can be substantial; those in the top marginal tax bracket may pay up to 40% on estates with assets of more than US$1 million. Moreover, for US citizens and residents this tax applies to assets held worldwide. Real estate ownership alone can easily exceed those limits.

Fortunately, the reality is somewhat more encouraging. Only around 2% of the US population actually pays estate tax, largely because of exclusions that effectively spare all but the largest estates.

The two most common exclusions are:

  • Annual exclusion of US$15,000 per person
  • Lifetime credit of US$11.7 million for 2021 and indexed annually. Something of a political football, this credit can rise or fall along with changes in government[1]. The current credit limit is set to expire at the end of January, 2025.

These annual exclusions are portable, meaning they can be used by any descendant of the deceased.

The gift that keeps on giving: to the IRS

In the battle of wills between those determined to transfer all of their wealth to succeeding generations and those determined to “tax to the max,” many strategies have been tried and failed. Gifting assets to relatives while the owner is still alive has been one of the more popular tactics. Not surprisingly, the IRS employs two additional taxes to thwart such attempts at tax-free wealth transfer.

The first is a garden-variety gift tax. For non-spouses, annual exclusions are the same as for estate taxes. For spouses they are more generous: unlimited for spouses who are US citizens and $159,000 for 2021 (indexed annually) for spouses who are not. Continue Reading…

The best Cryptocurrency Payment Apps and Wallets in 2021

Different coins of crypto currency, including ethereum, litecoin, bitcoin, monero, ripple, and dash.

By Hristina Nikolovska

Special to the Financial Independence Hub

The latest Bitcoin bull run made many people want to jump on the train and use or store cryptocurrencies. There are many digital assets to choose from, and while wallets support most of them, the traditional payment apps have just started to experiment. PayPal was the latest company to show interest in allowing users to purchase cryptocurrencies with its app. 

Even though it covers 26 currencies in various countries, PayPal currently allows Bitcoin purchases to US citizens only. Still, that’s a great start. If you’re curious to know how to use crypto or invest in it and hold it, these are some of the best payment apps and crypto wallets to explore. 

Cryptocurrency Payment Apps

Both merchants and private individuals can use these payment apps to send and receive various coins. Fees are minimal, and payments are fast. 

Coinbase Commerce

Coinbase Commerce is one of the most famous cryptocurrency apps to help merchants accept payments. Coinbase Commerce doesn’t charge fees, and it also supports price-stable cryptocurrencies. Payments are irreversible, and merchants can immediately sell earned crypto for cash or USD coin. This app integrates with WooCommerce and Shopify. 

BitPay

BitPay is available for both personal and business users. This app can store and manage BTC, Bitcoin Cash, Ethereum, and other coins. Also, it comes with a BitPay Prepaid Mastercard. Merchants can use this app to accept crypto payments with just a 1% fee. 

Electroneum

Electroneum (ETN) is helping people across the globe pay for goods and services in-store and online. It’s accepted in more than 190 countries and brings benefits to people, merchants, and corporations. It removes the need for a bank account and provides new payment opportunities for all. 

GoCoin

GoCoin is one of the longest-running blockchain invoicing platforms. It supports Bitcoin, Bitcoin Cash, Litecoin, Ethereum, and EOS. The fee is only 1%, and the GoCoin gateway provides ultimate flexibility and security of payments for merchants. Merchants of all sizes, as well as startups, are using GoCoin all over the world.

BTCPay

BTCPay Server is an open-source crypto payment processor. It’s secure, private, and free to use. There’s no usage fee, and merchants can connect their e-commerce store or use other apps to receive payments. BTCPay is excellent for invoicing and supports WordPress, Tor, WooCommerce, Magento, and other platforms. 

The Best Wallets to Store Digital Currencies 

Even though payment apps can also serve as wallets, some cryptocurrency owners prefer to download separate software to store their investments.  Continue Reading…

Where to invest 2021 RRSP contributions

By Graham Priest

Special to the Financial Independence Hub

In today’s low interest rates environment, investors are looking beyond GICs and equities to generate greater returns over the long term. The economic recovery has surpassed expectations, and individuals are looking beyond COVID-19 and a return to some normalcy by the end of the year. With this in mind, there are several different kinds of investments that Canadians could consider making from their RRSP contributions in 2021.

For example, technology stocks and other “work from home” related stocks that performed well in 2020 might take a breather in 2021 if more of us start heading back to the office.  Areas of the market that underperformed in 2020 may exceed expectations this year. For example, recently energy stocks have started to display strength. Emerging markets is another area that will likely perform well in the next year. If the USD declines in value, it will be an added benefit for emerging markets, as a large portion of their debt is denominated in USD.

Additionally, after a rough 2020, Real Estate Investment Trusts (REITs) are gaining a leadership role within the market. Many REITs have strong yields that provide income that exceeds the interest paid on government and corporate bonds. However, REITs are a good investment inside a TFSA. The income distribution from a REIT is generally taxable income, and in a TFSA, there is no tax on that income.

Put high-growth investments outside RRSP

Investments that have the potential for exponential growth may be better suited outside of an RRSP, as withdrawals from an RRSP are taxed as income. Withdrawing large capital gains tax-free from a TFSA is a better option for investors who have RRSP and TFSA accounts. Continue Reading…