Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

10 smart spending tips from frugal Small Business owners

How can small business owners be more frugal and spend smarter?

To help you and your small business to be more frugal and spend smarter, we asked small business owners and financial experts this question for their best advice. From polyphasic sleep to developing your IT skills, there are several tips to help your small business to be more frugal and to spend smarter.

Here are ten ways your small business can be more frugal and spend smarter:

  • Google my Business
  • Unsecured Loan or Line of Credit
  • Outsource to Experts
  • Free Trials
  • Check annual discounts for Services
  • Reevaluate your Digital Marketing Strategy
  • Budgeting ahead to Avoid Impulsive Spending
  • Use Free Software
  • Automate and Delegate
  • Only Spend if it adds more Value than it Costs

Google my Business

Google Ads offers small businesses a great opportunity to develop visibility in search result pages. By expressing a willingness to bid on keywords relevant to a business, small business owners can pay per click to attract potential customers to their website. However, as competition amongst advertisers increases, so does the cost per click. In our industry, keyword costs can be $50 – $100 per click. With rising advertising costs, small businesses have less and less margin for profits. To spend smarter, small businesses can invest in an organic search presence to increase their visibility for keywords without paying for each click. One simple step for small businesses is to start a Google My Business page to increase visibility on the local level. Alternatively, businesses can blog about topics similar to keywords in a Google Ads account to reduce paid ad costs and increase organic traffic. — Dan Reck, MATClinics

Unsecured Loan or Line of Credit

Pre-revenue businesses still need to spend in order to launch a new venture. Sometimes the best time to be frugal is when a small business owner is seeking financing and needs to pay extra attention to the interest rate that comes with an unsecured loan or line of credit. Many funding sources tout simple application processes and short pre-approval turnaround times. Be careful not to move too fast on a loan that carries a higher interest rate. Instead, take the time to do your due diligence because some upfront work can save on long-term frugality. — Craig Johnson, Unsecured Funding Source

Outsource to Experts

Let’s say that you’re a small business owner who wants to invest in something like SEO (search engine optimization). You can pay an SEO agency like us $2,500 per month, or $30,000 per year to perform SEO at an expert level. Or, you can hire an SEO manager internally for $65,000 to $85,000 annually to perform SEO for a company. Sometimes, it saves to outsource certain services to experts instead of hiring internally for a business need. Consider the alternatives before posting a job description to a career page. –– Brett Farmiloe, Markitors

Free Trials

Sending secure communications typically comes with a cost to ensure security and compliance. However, some communications companies offer free trials to test their service. For example, our company offers small businesses the ability to send a free fax. If a small business owner is looking to be frugal when it comes to communications, seek out these free trials as a way to save money and discover services that can truly support your business. — Eli Patashnik, iFax

Check Annual Discounts for Services

If you know that you are going to be using a service for an entire year, see if you can pay the entire year in advance for a discount. This often netted us 10-20% discounts on services that we were already paying for. Even if a service doesn’t appear to offer this type of discount, you should inquire as some companies will offer quarterly or semi-yearly discounts as well. I also recommend a quarterly review of your small expenses and ensure that everything is being used. There were many times, we were able to cut costs by simply realizing that we no longer properly utilized a specific service. — Matt Blake, Entrepreneur, Investor and Partner

Reevaluate your Digital Marketing Strategy

Look at your digital marketing ad spend, analytics and metrics. Are you meeting goals and objectives? There is a lot that can be done organically (non-paid) with content marketing — blogging, videos, podcasts — in conjunction with social media marketing, that will help with Search Engine Optimization (SEO) and drive traffic to your website without spending money. Continue Reading…

The Resilience of Dividends

Franklin Templeton: Image by iStock

By Nick Gétaz and Matt Quinlan

Franklin Equity Group (Sponsor Content)

As fund managers with the Franklin U.S. Rising Dividends team, we believe that a company increasing its dividends is evidence of three key characteristics: growth, strong capital allocation, and resilience.

Firms that show substantial and sustainable dividend growth also tend to experience greater long-term stock price appreciation. Being able to consistently increase dividend payouts, even during periods of wider economic malaise (the past year being a perfect example) points to a company that is well managed and with a resilient business model. Investors can therefore participate in market growth, while still protecting their capital against downside risk.

Dividend-paying companies can be found across all sectors, and diversification is an important element of the Rising Dividends portfolio. Currently, Industrials, Information Technology and Health Care have the largest allocations in the fund, while there is no exposure to Communication Services, Utilities and Real Estate: the latter two sectors’ growth prospects make them generally less attractive at the moment.

In Health Care, current holding Medtronic PLC is a good example of the type of company we seek out for the portfolio. With consistent dividend increases for 43 years, the world’s largest medical device manufacturer has a diversified and resilient product shelf. Medtronic is a leading provider of cardiovascular and surgical products, and the development of surgical robots and a suite of cardiac rhythm products position it for potential sales growth and efficiency gains in the coming years.

The largest position in the fund is Microsoft, which has accounted for 8–9% of the portfolio over the past year. In our view, Microsoft has a number of different growth drivers among its cloud, enterprise productivity and gaming offerings. Microsoft Teams has also become a vital tool for many companies that had employees switch to working from home over the past year, which is further evidence of Microsoft’s resilience and ability to thrive through different market cycles.

Dividend cuts were less severe than expected during the pandemic

Resilience, on a variety of fronts, has certainly been required over the past year as the COVID-19 pandemic has hammered the global economy. At the outset of the crisis, dividend reductions were widely predicted, but these cuts weren’t as far reaching as expected: in our portfolio, approximately 3% of holdings reduced dividends in 2020.

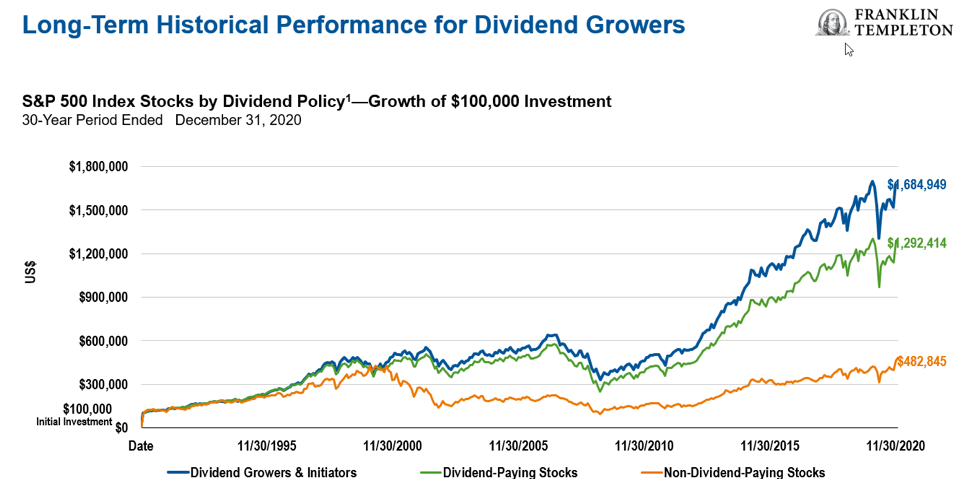
Historically, the evidence shows that dividend-growing stocks have tended to perform better than stocks that don’t provide dividends, and they have done so with less risk. The chart below shows dividend growers against the S&P 500 Index over the 30-year period ending December 31, 2020. This time frame includes multiple market cycles and downturns, including the Dot-Com collapse; the Global Financial Crisis; “The Lost Decade”, the 10-year period up to 2009 when U.S. equities (represented by the S&P 500 Index) had a near-zero return; as well as the correction of last February/March.


Taking a long-term view, corrections and drawdowns are inevitable, so it’s crucial to build portfolios of high-quality companies that can navigate different economic cycles. Continue Reading…

Review: The Disciplined Trader

81o4jz+QTgLI am not and never will be a “trader,” in the sense of a full-time stock-picker/market-timer.

However, on the suggestion of my financial advisor, I recently ordered and read a copy of a classic trading book called The Disciplined Trader, by Mark Douglas (New York Institute of Finance, 1990).

Personally, my main interest in the topic involves hedging downside risk:  taking actions that limit some downside, at the expense of some potential upside. What surprised me about this book — which bears the subtitle Developing Winning Attitudes — is how much space was allocated to psychology and mental attitudes. In fact, fully all of the third of the four major sections is devoted to what I would call “softer” topics like understanding the nature of the mental environment, how memories, associations and beliefs manage environmental information, managing mental energy and similar topics. Continue Reading…

Investing in times of uncertainty

It’s easy to stick to your long-term investing plan when times are good. Indeed, if your investment portfolio had any U.S. market exposure at all over the past 12 years you’ve likely enjoyed nearly uninterrupted growth.

Of course, there are always bumps in the road. Stocks fell sharply in a short period between February and March 2020, the swiftest decline in history. The world was shutting down in response to the COVID-19 pandemic and investors panicked. But stocks came roaring back and the S&P 500 ended the year with a gain of 18.4%. Things were good again. Until they weren’t.

Investors have been worried about a prolonged stock market crash for years. Those fears are heightened each year that stocks continue to rise. Surely this can’t last forever. Meanwhile, as we come out of the pandemic, there’s anxiety over inflation and rising interest rates, which has put downward pressure on bond prices. Long-term government bonds are down 12% on the year. U.S. treasuries, the ultimate safe haven, are down 3.3%.

In uncertain times we look to economic forecasts and predictions of what’s to come. There’s no shortage of opinions, so it’s easy to find one that fits your narrative. It’s hard not to listen when legendary investors like Jeremy Grantham call this the greatest bubble since 1929.

So, what’s an investor to do when stocks are poised to crash, bonds are in a free-fall, and cash pays next to nothing? Even gold, often pegged as an inflation hedge and portfolio diversifier, is down nearly 10% year-to-date.

Are you properly diversified?

Is your portfolio as diversified as it should be? Does it have a mix of Canadian, U.S., International, and Emerging Market stocks? A mix of short-term and long-term corporate and government bonds?

Are you judging your portfolio as a whole or by its individual parts? It’s never easy to see a specific holding fall in value. It makes you wonder why you hold it at all. Bond holders must be feeling that way right now.

If you hold Vanguard’s Canadian Aggregate Bond Index (VAB), you’re likely not pleased to see this performance:
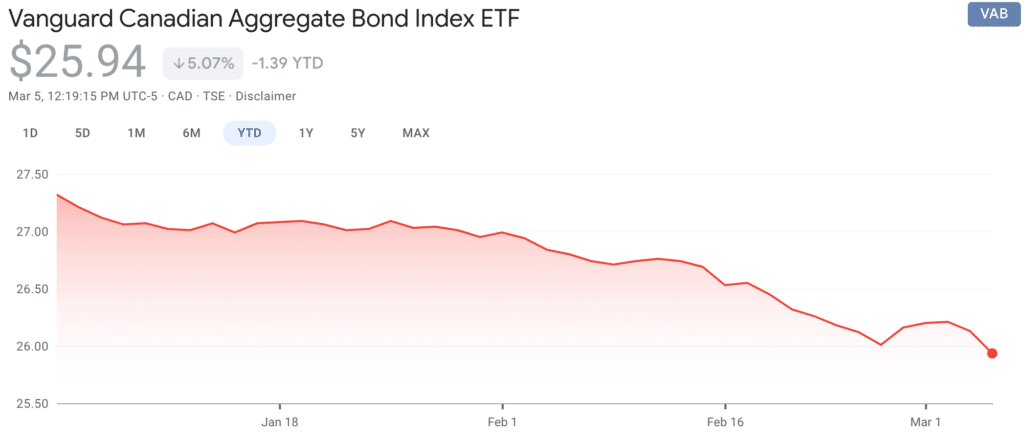
VAB YTD returns

When you add U.S. and Global bonds to the mix, the results are similar but slightly more favourable:
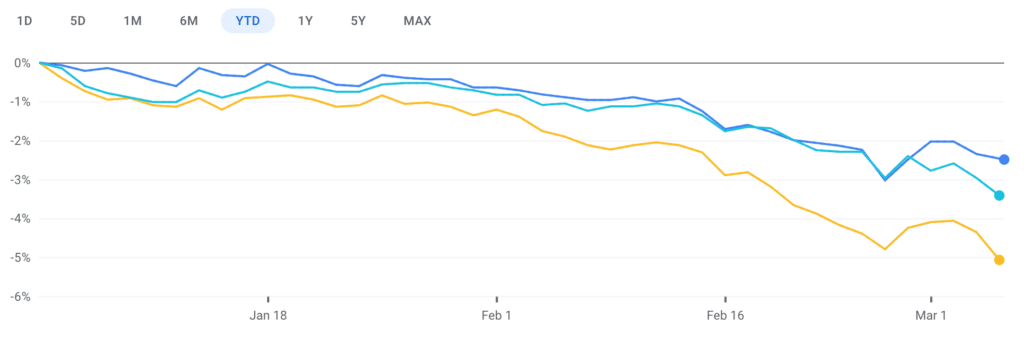
Vanguard US and Global Bonds YTD

Now let’s add Canadian, U.S., International, and Emerging Market stocks to the portfolio using Vanguard’s FTSE Canada All Cap Index (VCN), Vanguard’s U.S. Total Market Index (VUN), Vanguard’s FTSE Developed All Cap ex North America Index (VIU), and Vanguard’s FTSE Emerging Markets All Cap Index (VEE):

Vanguard Canadian, US, International ETFs

When you put all seven of these ETFs together you get Vanguard’s Balanced ETF portfolio (VBAL). Each part following its own unique path, but blended together using a rules-based approach that maintains the original target asset mix through regular rebalancing.

Here’s how that looks over a three year period (since VBAL’s inception):
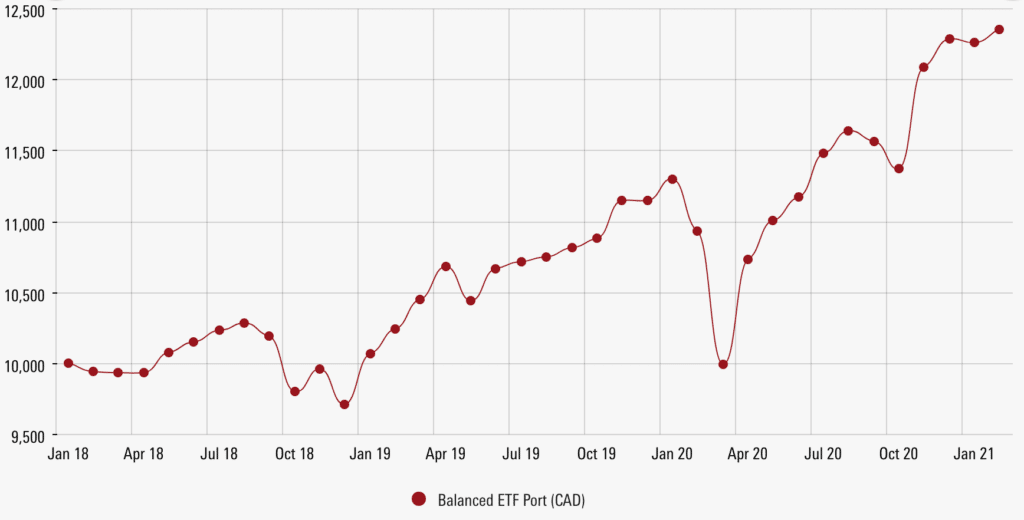
VBAL since inception

This is what diversification looks like. While some individual parts lag behind, others lead the charge and drive the overall returns. Regular rebalancing helps ensure you always buy low and sell high while managing your risk and return. The result is a compound annual growth rate of 7.3% since 2018.

Perhaps the best way to visualize how diversification works is by looking at the periodic table of investment returns over the past 20 years (source: www.callan.com):
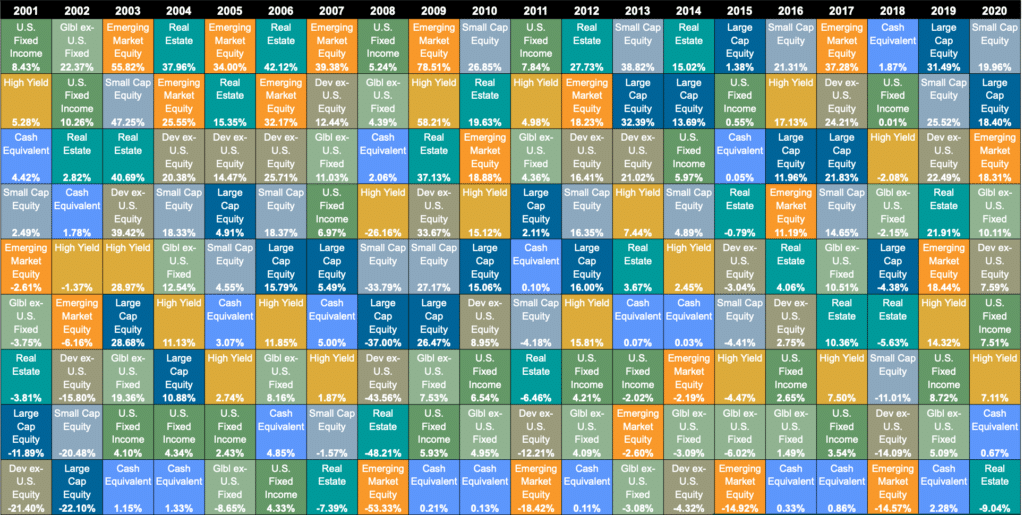
Periodic Table of investmeent returns

Last year’s winner is often next year’s loser. Every asset class has had its turn at or near the top, including large cap stocks, small cap stocks, emerging markets, real estate, bonds, and yes, even cash (once).

Do you think you can predict which assets will lead the way in 2021 and beyond? Unlikely. That’s why it’s best to diversify broadly so you can capture market returns without trying to guess where to park your money.

What about pulling out all of your investments and moving to cash? Well, cash was the worst performing asset class in eight of the 20 years. Even in 2008-09 bonds were the better bet.

Have you rebalanced?

I’ve written before about investors getting distracted by shiny objects like cryptocurrency, technology stocks, and high-flying fund managers. Even seasoned investors were moving more of their money into U.S. stocks, technology stocks, and Bitcoin to capitalize on rising markets.

Indeed, why hold bonds at all when every other asset class has been soaring?

The result is a portfolio and asset mix that is likely out of step with your original goals.

Rebalancing is counterintuitive because it forces you to sell what’s going up in value and buy more of what’s going down. It’s tough to wrap your head around selling U.S. stocks to buy more Canadian stocks. Or worse, to buy more bonds.

It’s even more difficult in uncertain times. It’s easy to look back at March 2020 or March 2009 as buying opportunities of a lifetime for stocks. But in the moment it probably felt terrifying to even be holding stocks at all.

Today, nervous investors are worried about holding bonds. What should be the stable portion of their portfolio is suddenly underwater and signs of future upside are nowhere to be found.

Damir Alnsour, a portfolio manager at Wealthsimple, has heard from many of these anxious investors in recent days. They’re asking questions like, will bonds keep going down?

“The answer is that no one really knows if it is likely to continue, but we always look at our portfolios with a long-term lens because we don’t allocate our investments based on short-term market performance. We expect that in the future there will be times where stocks are doing well, and bonds are underperforming but also the opposite. We can’t predict these times, and we don’t think anyone else can either,” said Alnsour.

He encourages his clients to take a 30,000-foot view and remember the reason their portfolio includes bonds. Bonds are a long term source of return that improve the stability of your portfolio because they often react to changes in the economic environment differently than stocks.

“During most of the major stock market downturns historically, bonds have increased in value and helped cushion losses,” said Alnsour.

Just like the three-year chart of VBAL’s returns, a well-balanced and diversified portfolio is expected to rise over time: after all, that’s why we invest in the first place. But it’s normal for the same portfolio to suffer minor short-term losses along the way that can sometimes take weeks or months to recover.

Back to Wealthsimple’s Alnsour:

“Also, keep in mind, we would rebalance the portfolio if bonds were to continue to sell-off. What this means is that should the bond allocation drop below our rebalancing threshold, we would sell some equities to add to bonds and therefore pick up more fixed income at a cheaper price and better yields (just as we would have sold bonds to add to your equity position in March of 2020!).”

Don’t Just Do Something, Stand There!

Your portfolio is like a bar of soap. The more you touch it, the smaller it gets. Yet in times of uncertainty we can’t help but feel like we need to do something to curb losses or increase gains.

The better choice, assuming you have a well-diversified and automatically rebalancing portfolio, is to log out of your investing platform, close your internet browser, and do nothing. Focus on your family, friends, hobbies: anything that will prevent you from logging back on and seeing your investments in the red.

As PWL Capital portfolio manager Benjamin Felix says, “your investment strategy shouldn’t change based on market conditions.”

That’s right. You identified your risk tolerance and time horizon, and chose your original asset mix for a reason. You understood that markets fluctuate, often negatively, for periods of time and that is out of your control. Yet when markets are going through their downswing, you feel compelled to change your approach.

Let’s go back to the term, “uncertainty.” Isn’t the future always uncertain? When are we investing in certain times?

Pundits and market forecasters often paint a bleak future, like Grantham’s 1929-style crash or Dr. Doom Nouriel Roubini calling for hyperinflation. The truth is nobody knows how this will play out.

What if you make a tactical shift to your investment strategy and you’re wrong? There are plenty of investors who moved to cash after the global financial crisis and never found their way back into the stock market. Once you convince yourself of a particular narrative it’s nearly impossible to admit that you were wrong and change course.

Final Thoughts

It’s reality check time for investors. We’ve been in a bull market for 12 years (minus a few blips). Almost everything has worked, which can lead to overconfidence in your investing skills. Meanwhile, many investors have strayed away from their original goals to chase even higher returns from U.S. stocks, technology stocks, and the like.

It’s time to check in on your portfolio and make sure it’s broadly diversified and risk appropriate for your age and stage of life. It’s time to rebalance, if you hold multiple funds, and get back to your original target asset mix. Finally, if you’re already invested in an appropriate asset allocation ETF or robo-advised portfolio, it’s time to do nothing. Don’t change your investing strategy based on market conditions.

Take a long-term view of your investments rather than looking at the daily changes (which can be maddening). That’s how to invest in uncertain times.
In addition to running the Boomer & Echo website, Robb Engen is a fee-only financial planner. This article originally ran on his site on March 5, 2021 and is republished here with his permission.


10 Stock Types investors could consider in 2021 

By Emily Roberts

For the Financial Independence Hub

Following a challenging year for us all, we are confident that those reading this and beyond are more than happy to see the back of 2020. As we make our way further into 2021, the pandemic’s impacts are beginning to show themselves more, and we can see the different ways that the pandemic changed our lives in some way or another.

Financially, the last year has been one of the toughest that many of us have ever faced. A large majority of the world population experienced the economic crash of 2008 but have stated that the last year has been similar in some elements but drastically different in others. It is no surprise that experts have estimated that the pandemic’s financial impact across the globe is set to be much worse than that felt back in 2008.

As a result of this, there is little surprise that people are searching for ways that they can be more economic themselves, and how they can improve their current situation. We are seeing more and more people monetizing on their existing skills in every direction, creating a small, online business selling some type of arts and crafts or baked goods.

While these are certainly effective ways of boosting your income following a set-back, this is not the only avenue available to those searching for a side hustle. With an increased interest in the world of cryptocurrency as of late, and with a 350% increase in how many Google searches have been made into Bitcoin, there undoubtedly appears to be an interest in investing our money.

If you are interested in finding out more about investing your money moving forward and the different stock types to consider when exploring this world, you are in luck! Detailed below is a helpful list of the best stock types to consider in 2021. Read on for more.

Before deciding to invest

Particularly when exchanging money, you want to make sure that you have put some thought into this. The last thing that you want to do when attempting to boost your income is to put yourself into any sort of financial difficulty.

Those who are clued up on all thing’s stocks are probably aware that there is risk involved in investing in stocks. But for those who are not, this is one thing that is well worth considering before jumping into this world.

By ensuring that you correctly understand the ins and outs of what you are getting yourself into, you can rest assured that you will be moving money around in a safe manner.

It is worth noting that investing in stocks takes some time and patience; you will not see the results overnight, so it is worth monitoring over time. On that note, let’s get to the main event: what types of stock exist.

Different Stock Types 

  1. Common Stock: As the name here suggests, this is the most common type of stock that exists and which you can invest in. Common stock is an ideal stepping-stone into the world of investment and is suitable for those who are first starting out on their investment journey and building up a portfolio. When you invest in a common stock, you own a share in the stock and in the company’s profit as well. Those who choose to invest in a company through common stock can also expect to get the ability to vote on the company policy and anything else of importance that requires shareholder’s input.
  1. Preferred Stock: This type of stock is often compared to bonds. Unlike common stock, preferred stock pays investors a fixed dividend, whereas the common stock offers investors the opportunity to earn dividends, but these are not guaranteed. Preferred stock is an ideal choice for those looking to invest in something while prioritizing income rather than any sort of long-term growth. Much like that of common stock, those who invest in a company’s preferred stock can vote on matters involving shareholders but are also given more preferential treatment. What’s more, if a company is to go into liquidation or declare bankruptcy, those who own preferred stock are returned their dividends before those who have common stock.
  1. Mining Stocks: Unlike other aspects of the investment world, this may well be a term that not many people are aware of. That said, these are also stocks worth investing in during 2021. More so when wanting to boost your income. Much like our other suggestions, it is advised that those interested in investing into these particular stocks do adequate research levels first. Mining stocks have multiple elements to them, and these are known as either major or junior mining stocks. Major mining stocks are known to work in a similar way to that of blue-chip stocks. On the other hand, junior mining stocks are akin to  penny stocks. To learn more about mining stocks and how you can go about investing into this particular type of stock in 2021, check out the guide created by Wall St Now on their website.
  1. Blue Chip Stock: Following its brief mention previously, we thought it best to explain further what we mean by Blue Chip Stock and why it is one of the best stocks to invest in as we head further into 2021. Blue Chip Stock investors can expect to experience relatively low risks regarding their investment into a business. Companies that allow the opportunity to invest in Blue Chip Stocks are generally considered leaders in their industry. With strong reputations regarding products and services, those who choose to invest in this particular stock can rest assured that they will receive some sort of pay-out at some point.
  1. Cyclical Stocks: Another term those outside the investment world may be unfamiliar with, but another excellent type of stock worth investing in when wanting to make some profit in 2021. Cyclical stock is also known as equity stock and is generally used in businesses and companies that are manufacturing certain goods; this can include cars, houses, and other equipment. Generally speaking, we pay for necessary goods like food and drink on at least a weekly basis. We don’t tend to put a second thought into these purchases, and it is something that we need and therefore pay for often. Cyclical stocks rise and fall in value based on the ups and downs that come with being a business and any external influence. Think of economic crises – much like what we have seen in the last year – as well as economic booms. To make a profit through cyclicals, you would need to purchase a stock in a company during a time when the price is at its lowest. This could be during an economic crisis, so it is certainly worth considering at a time such as the present. To make a profit, simply sit with your investment and be patient until a time when the price has risen, during an economic boom. When investing into cyclical stocks, one thing that should be considered is that during times of recession, the investment you have made could be regarded as worthless. So, make sure to do your research before making the jump.
  1. Defensive Stocks: While on the topic of investment during the recession, our attention turns to the world of Defensive Stocks. Another suggestion for those looking to invest in 2021 is an ideal suggestion on the off chance that we enter another recession in the future. Continue Reading…