Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Debt lifts Gold

By Nick Barisheff

Special to the Financial Independence Hub

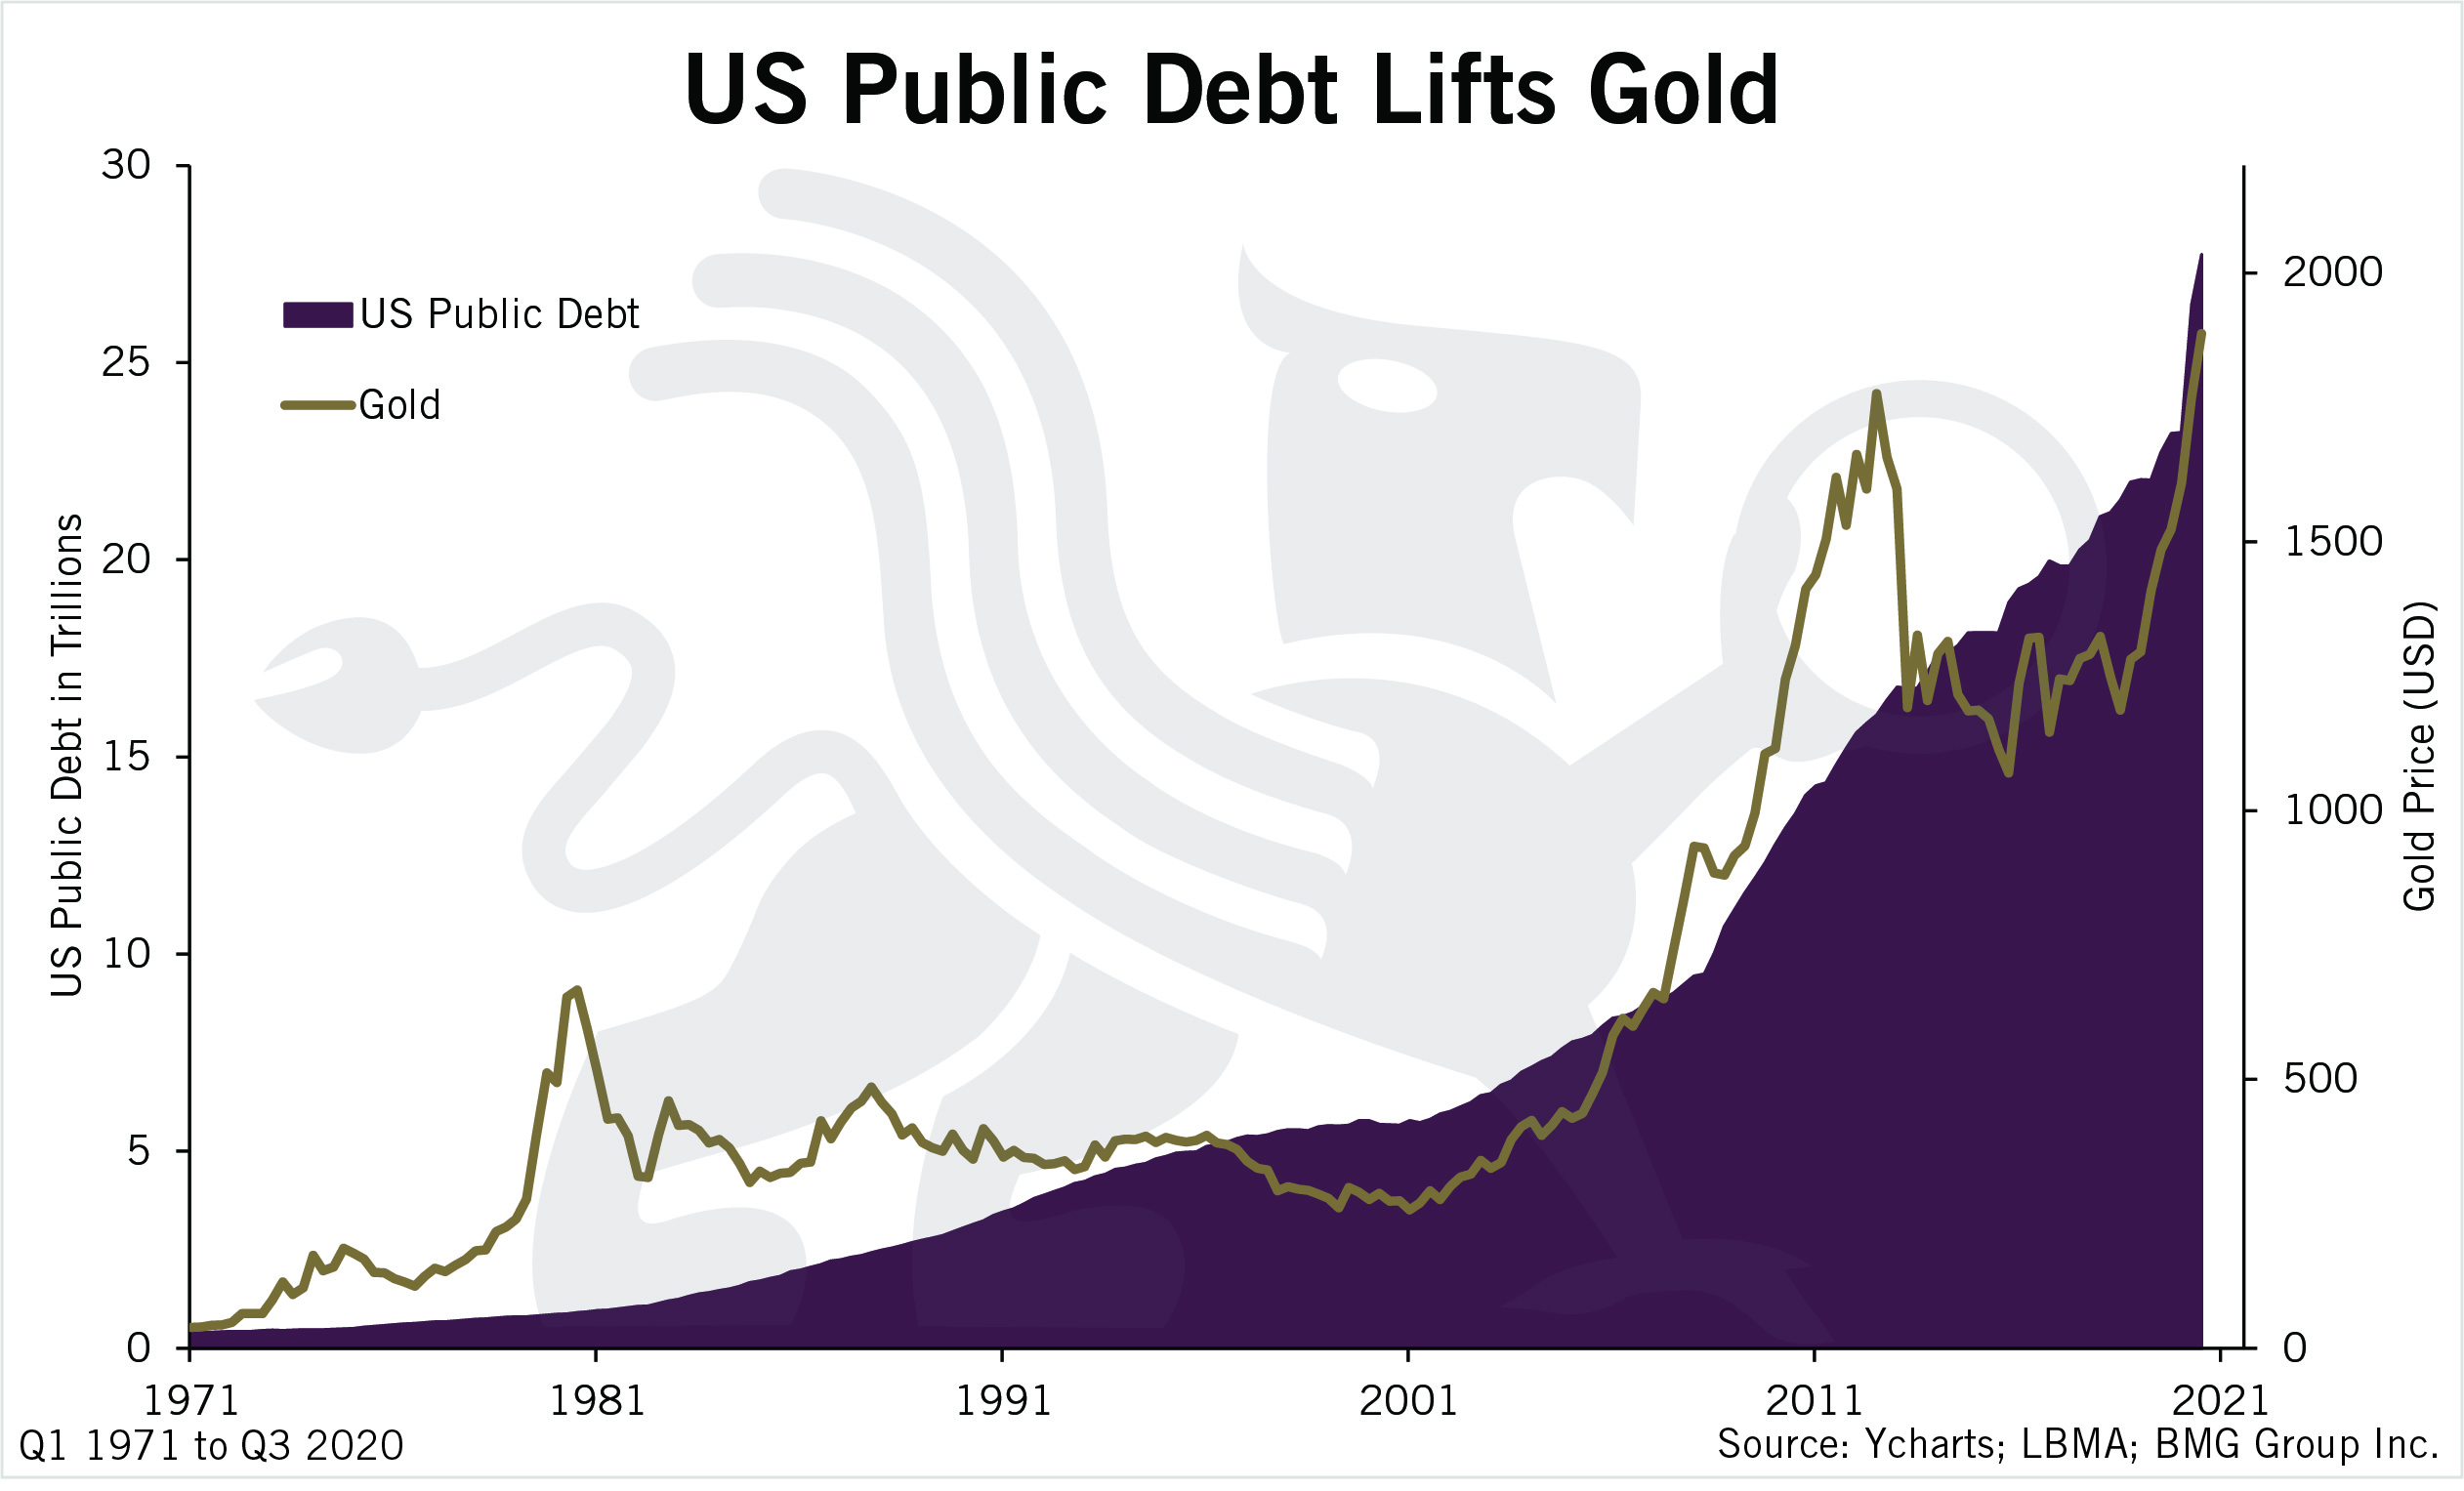
The world is awash in debt, an immense, unfathomable ocean of financial obligations. The stack of IOUs is so enormous, the balances so large, they will never be fully settled without dreadful consequences to the global economy. This tsunami of debt was unleashed in 1971, when Nixon ended the backing of the US dollar with gold.

Since 1971, US debt and gold prices have increased greatly. Traditionally, rampant increases in US debt occur when trying to pull the economy out of an economic downturn as displayed in the spikes that occurred in 2008 and 2020.

Considering the amount of debt that has already been taken on to combat the pandemic — combined with the rising uncertainty involving vaccinations and new strain variants — it can be anticipated that the worst is yet to come. As Democrats push towards passing an additional US$1.9 trillion stimulus package, governments are willing to take on previously unforeseen levels of debt to prop up the economy during the pandemic. This could lead to a promising future for the price of gold.

Manipulation of Precious Metals markets

This divergence has been caused by manipulation of precious metals. A great deal has been written about this and one of the best books on the subject is Rigged – Exposing the Largest Financial Fraud in History, by Stuart Englert.

Price manipulation never lasts, and when it ends there always tends to be a reset to inflation-adjusted levels. The biggest questions are: when and how high will gold and silver prices rise?

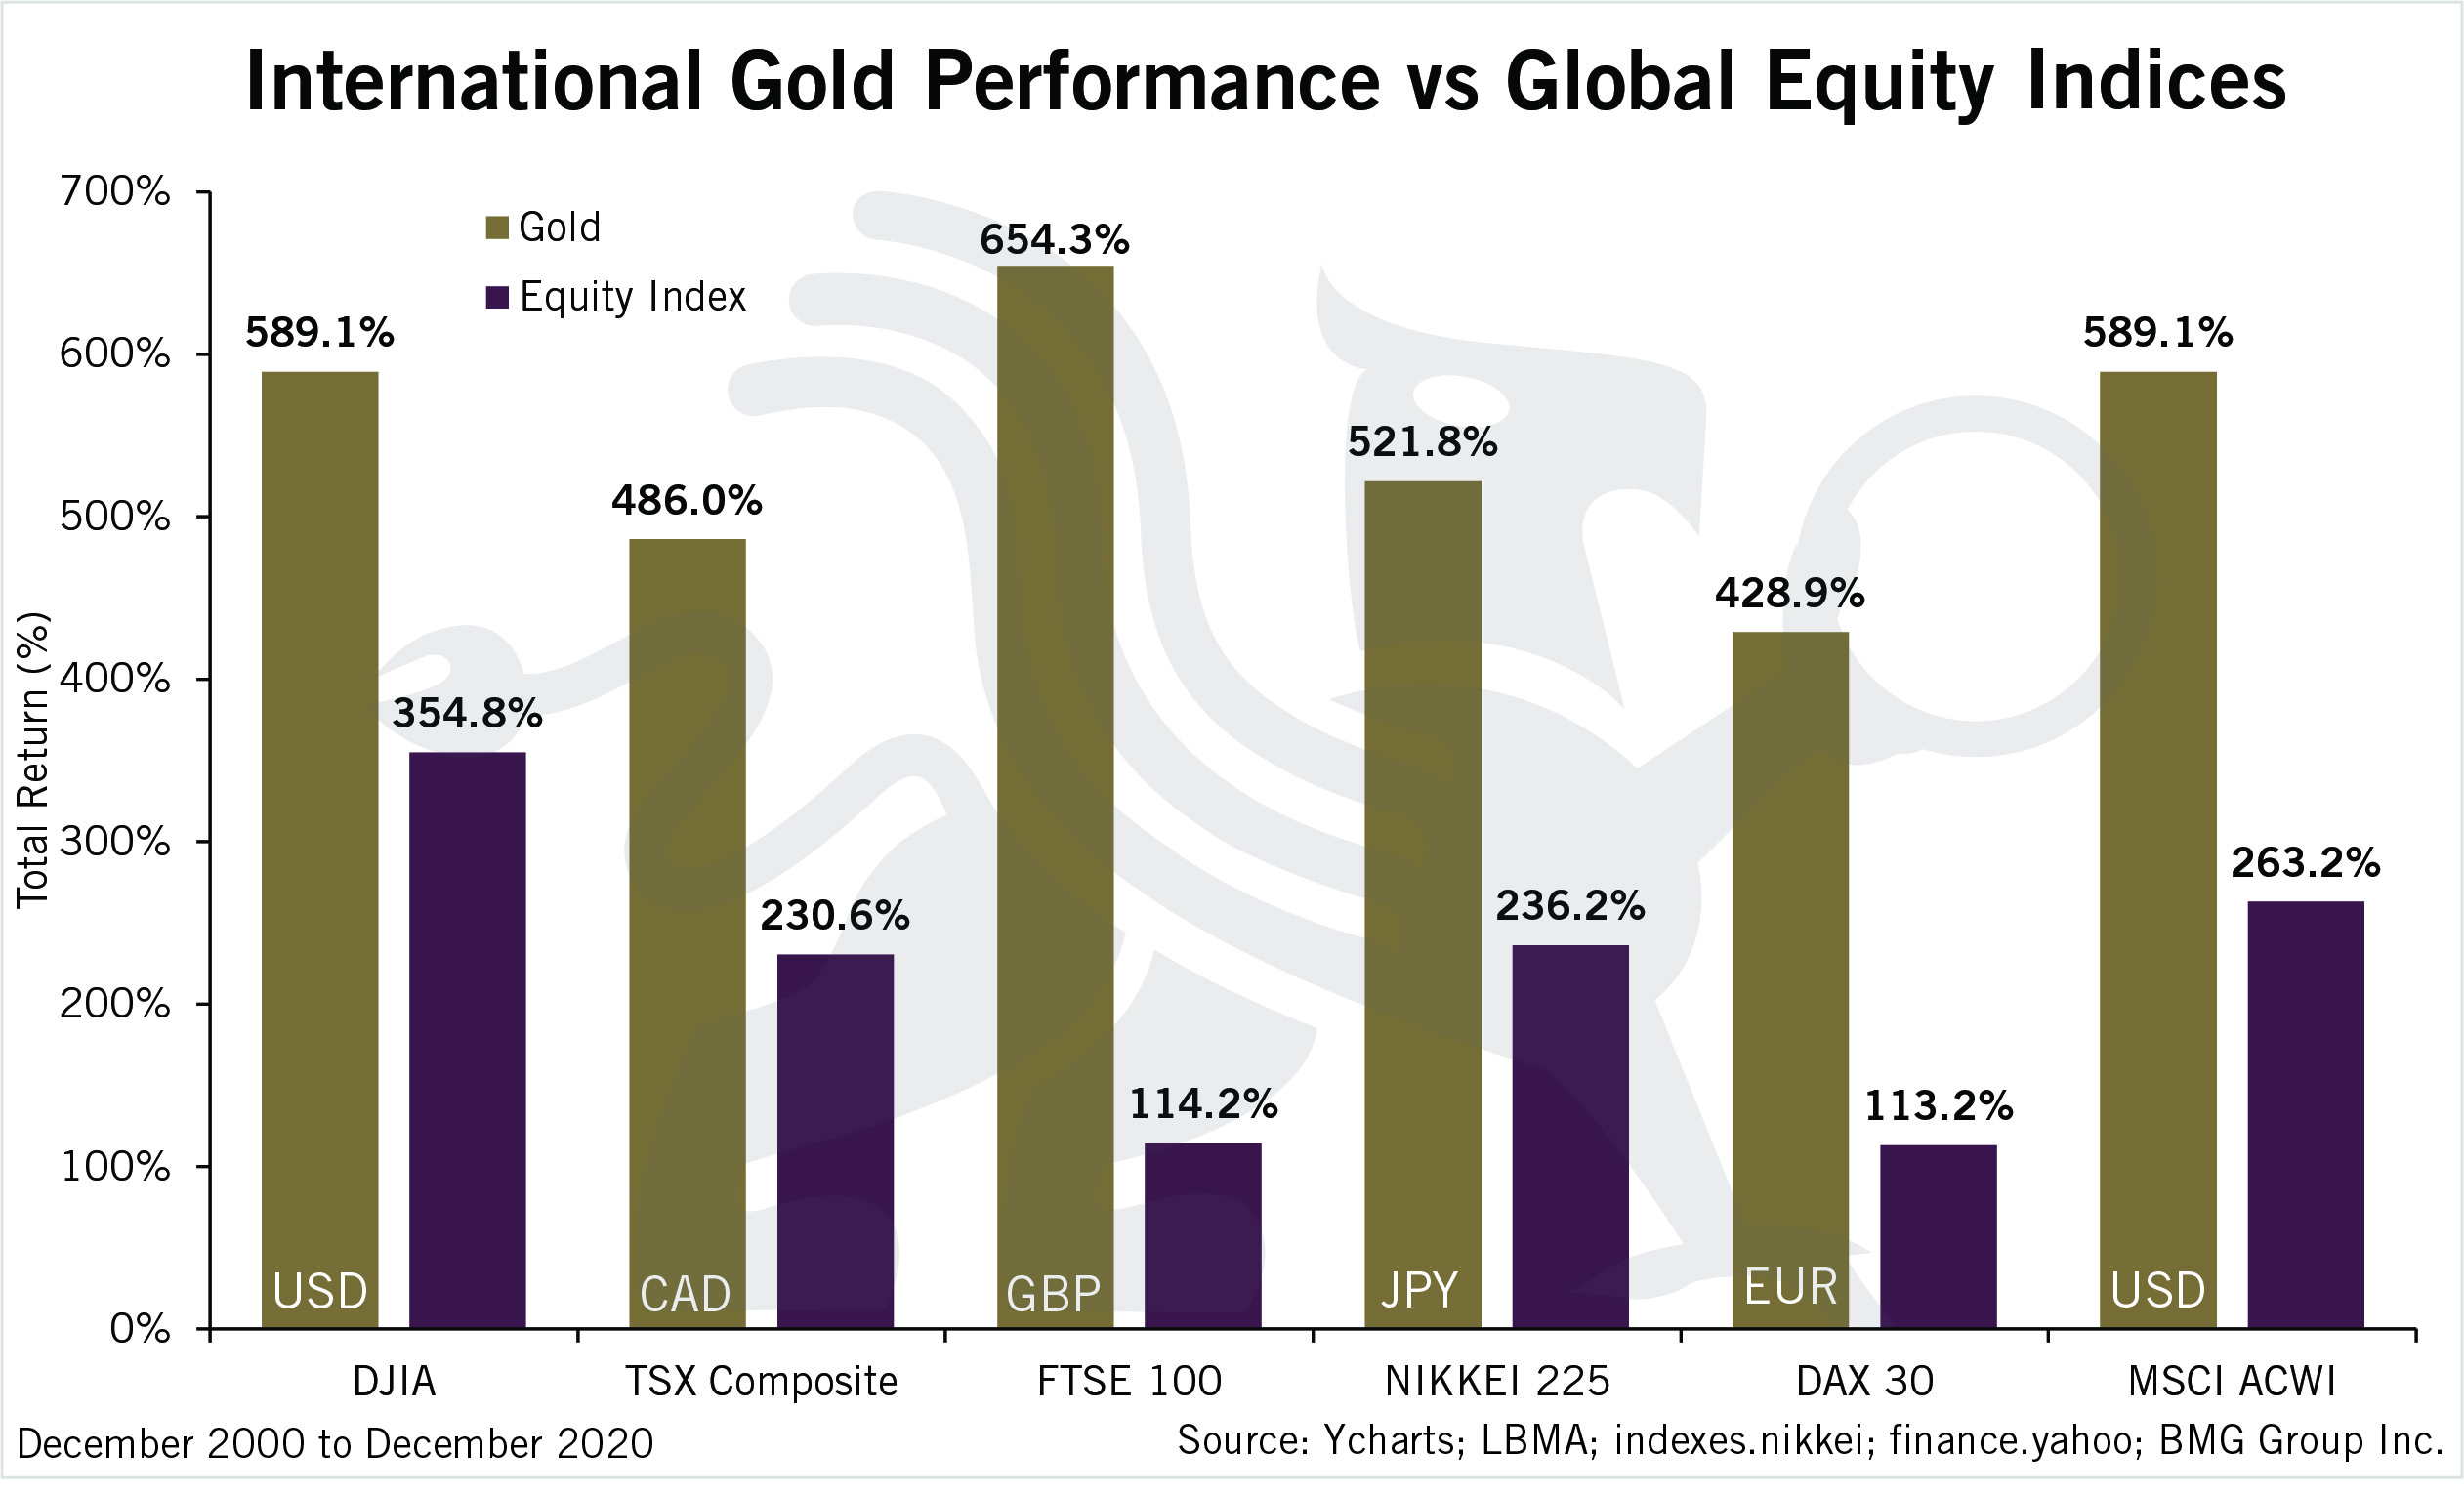
However, even with manipulated markets precious metals have outperformed traditional financial markets and have generated over 10% returns in all currencies over the last 20 years.

How soon precious metals rise to normalized levels depends on how rapidly governments and central banks inundate the world with debased dollars and other fiat currencies, and how quickly individuals and institutions lose faith in those increasingly worthless debt-based currencies.

The US national debt alone is nearly US$28 trillion. This doesn’t include the $159 trillion of unfunded liabilities, which brings the total to US$187 trillion or about US$480,000 per American citizen. This number also doesn’t include the $21 trillion in unaccounted federal expenditures discovered by Prof. Mark Skidmore and his economic students at Michigan State University.

Global debt hits 365% of World GDP

Global debt hit $277 trillion last year, or 365% of world gross domestic product (GDP). Public debt as a percentage of GDP has soared to unsustainable and perilous levels. The US debt-to-GDP ratio hit 136% last year. Canada’s debt-to-GDP ratio increased by nearly 80% through the third quarter of 2020, the highest rate among developed nations.

When you translate these incomprehensible and burgeoning debt totals into per capita obligations, it is obvious that they will never be repaid. They can only be inflated away.

Combined with hundreds of trillions in unfunded government liabilities, swelling debt and unregulated financial derivatives form a bottomless abyss that eventually will engulf nations and swamp the entire financial system. Little wonder that in 2002, billionaire investor Warren Buffett dubbed derivatives — which essentially are debt instruments used as collateral to take on more debt — “financial weapons of mass destruction.” At that time derivatives totaled $100 trillion, whereas today they are in excess of $1 quadrillion.

Socialists maintain public debt is acceptable when borrowing is for the common good, and Modern Monetary Theory (MMT) advocates claim unlimited government spending is not a problem. They believe governments can create an infinite amount of currency to fund social services and public works projects. They fail to recognize that debt is not wealth and increasing the currency supply decreases its value and produces price inflation.

Continue Reading…

Valentines Day: Is it easier to find true love or achieve financial independence?

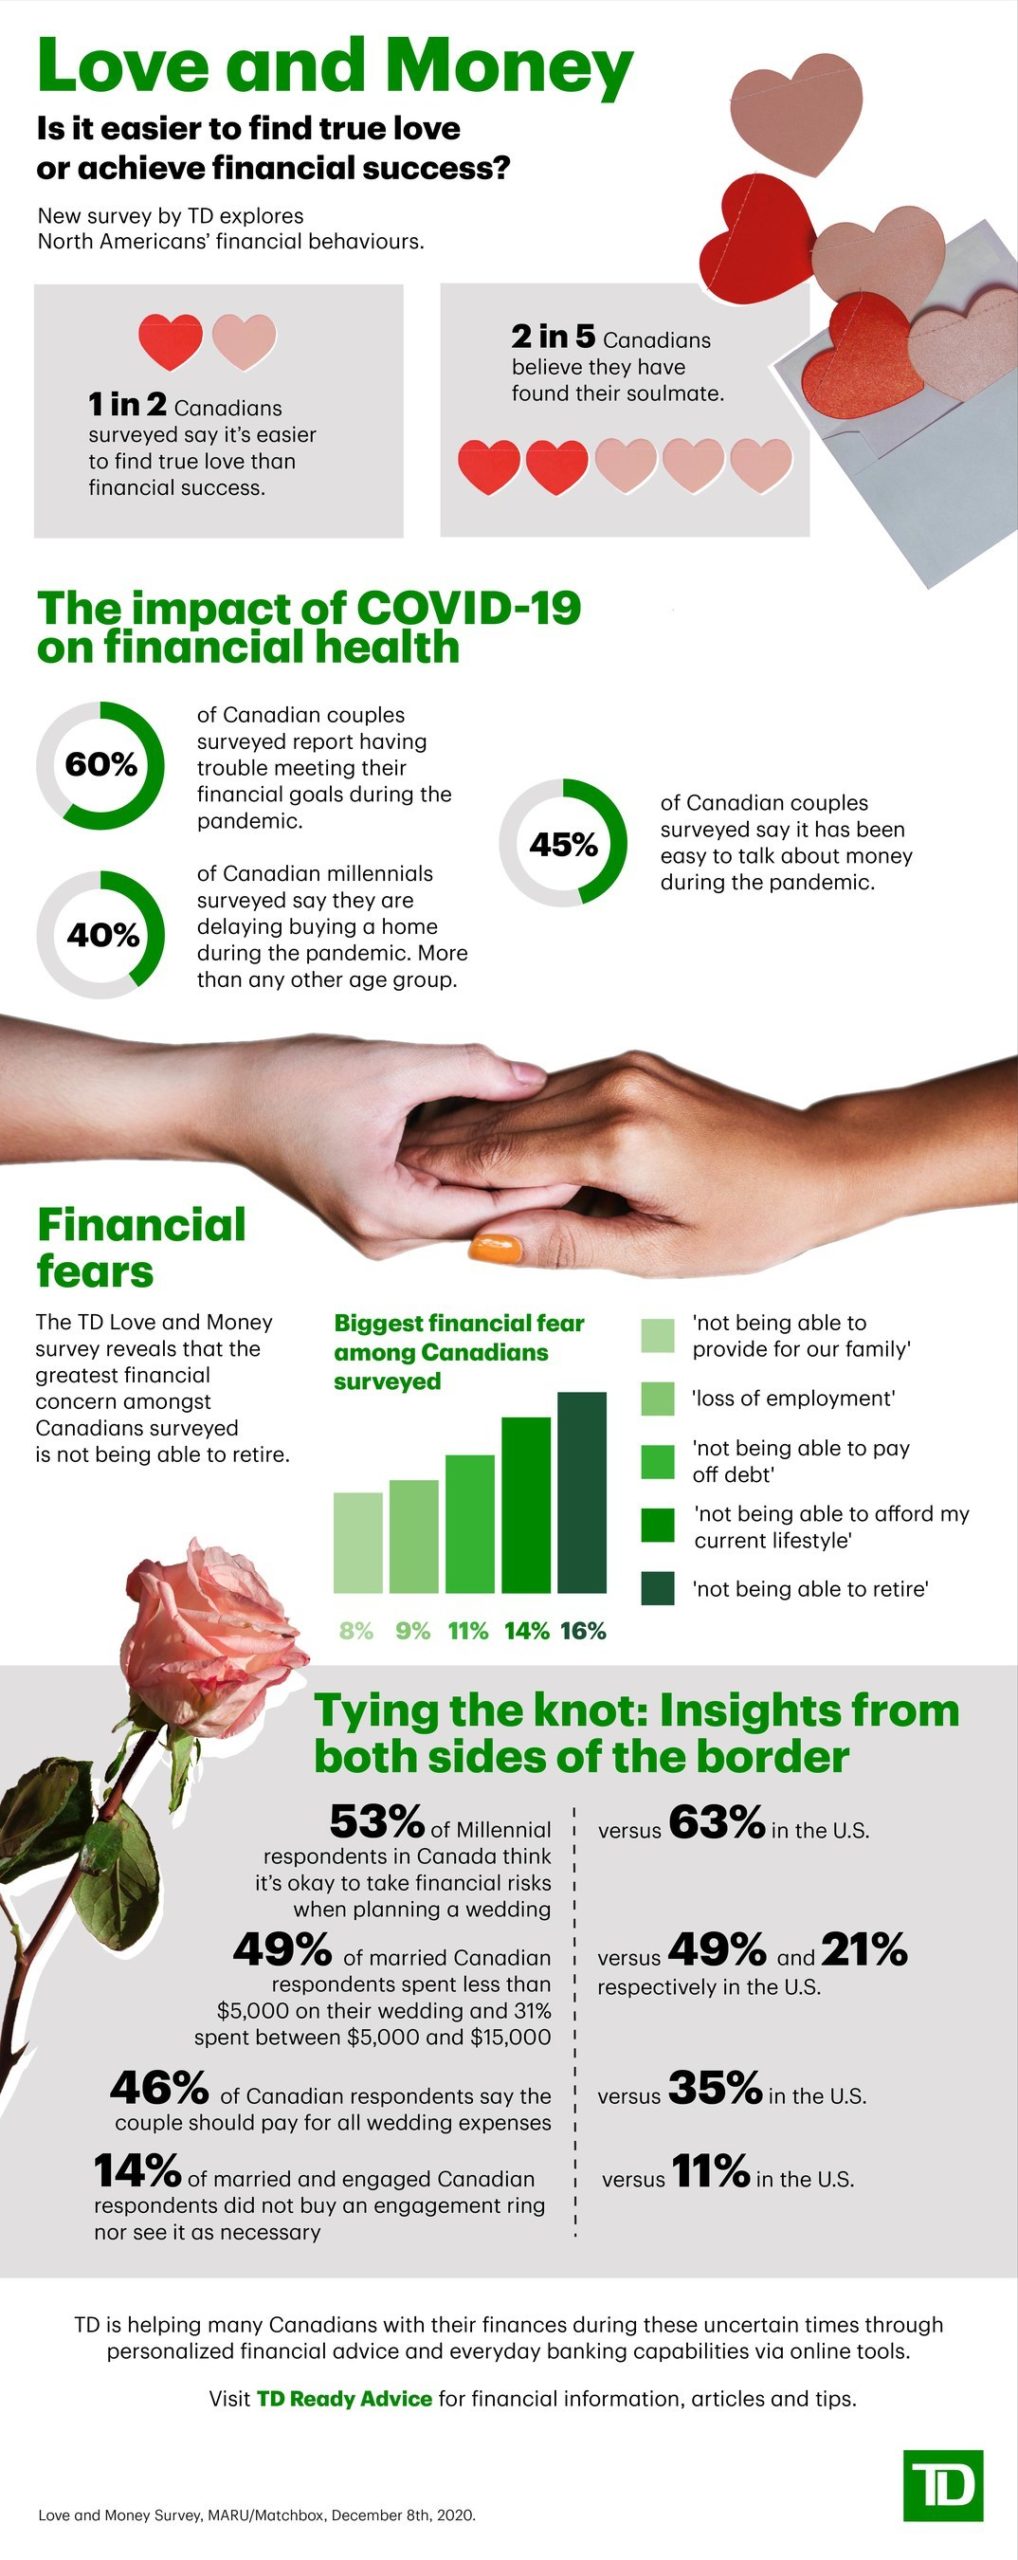
According to Love and Money – a survey from TD exploring the financial behaviours of more than 3,000 married, in-a-relationship or divorced North Americans – half of Canadians surveyed (49%) believe it’s easier to find true love than financial success.

However, that’s not to say those Canadian couples surveyed aren’t feeling cautiously optimistic about their future financial goals.

Despite challenges from the pandemic, nearly nine in ten (88%) respondents are currently saving for something. For those already in committed relationships, the survey also reveals that for most couples (45%) it has been easy to talk about money during COVID-19.

Nearly half (49%) say the pandemic has led to more open and constructive conversations about their finances, including the need to adjust spending habits by reducing spending on non-essential items (62%) and delaying larger purchases (36%).

With Love and Money revealing that six out of ten (60%) couples surveyed are having trouble meeting their financial goals during the COVID pandemic, it’s clear that having conversations about money are critical. In fact, “not talking about money with my partner on a regular basis” is the top financial mistake noted amongst Canadian respondents.

Fortunately:

  • 77% of Canadian couples surveyed say they typically open up about their finances within the first year of their relationship: including 56% who get very candid within the first six months.
  • Among Canadian married couples and those in a committed relationship, 85% say they talk about money every month.

But even though it seems most Canadians aren’t shying away from the (financial) “talk,” the TD Love and Money survey also shows that some Canadian respondents may be more likely to ask for forgiveness than permission.

  • Among the 8% of who admit to keeping financial secrets from their partner, 62% don’t ever plan to disclose them. Canadian couples surveyed admit to hiding a secret bank account (29%) or significant credit-card debt (22%).
  • Only 53% of Canadian Millennials say they agree with their partner on what expenses constitute a ‘want’ or a ‘need’.
  • 81% of Millennials admit to making unreasonable financial decisions, and one quarter (25%) say excessive and frivolous spending was one of them.

Tying the knot: Insights from both sides of the border

As expected, walking down the aisle looks very different during the pandemic, as many North American couples deal with the impact of lockdowns, gathering restrictions and reduced income. Consequently, Love and Money reveals that of the engaged Canadian couples surveyed whose wedding planning was impacted by the pandemic, more than half (56%) either postponed or downsized their nuptials.

When it comes to the big day, the TD survey also shows:

  • 53% of Millennial respondents in Canada think it’s okay to take financial risks when planning a wedding, versus 63% in the U.S.
  • 46% of Canadian respondents say the couple should pay for all wedding expenses, versus 35% in the U.S.
  • 49% of married Canadian respondents spent less than $5,000 on their wedding and 31% spent between $5,000 and $15,000, versus 49% and 20% respectively in the U.S.
  • 14% of married and engaged Canadians and 11% of their U.S. counterparts did not buy an engagement ring nor see it as necessary.

Biggest concern is not being able to retire

In terms of financial worries, the TD Love and Money survey also reveals that the greatest financial concern among Canadians is the fear of not being able to retire. Despite this concern, only one third (32%) of Canadians say they meet with a financial advisor on an annual basis. Continue Reading…

Investing is not a game

LowrieFinancial/Unsplash: michal-parzuchowski

By Steve Lowrie, CFA

Special to the Financial Independence Hub

“You can’t invest without trading, but you can trade without investing. … [T]hinking you’re investing when all you’re doing is trading is like trying to run a marathon by doing 26 one-mile sprints right after the other.” — Jason Zweig

Are you out of breath trying to keep up with the breaking news about GameStop and all the other red-hot trades o’ the day? Here’s a synopsis (to date), and what it means to you as an investor:

Seemingly Unstoppable Games

During the last week of January, a perfect storm of traders converged on the market, propelling the prices of a few previously sleepy stocks into the stratosphere.  Jason Zweig of The Wall Street Journal reported, “From Jan. 25 through Jan. 29, a ragtag army of individuals sent shares in GameStop Corp. up 500%, and sent many others skyrocketing too.”

Reddit Gone Wild

Interestingly, there was no huge, breaking news or major shift in these companies’ fundamentals to explain the surge.  Instead, a tidal wave of trading momentum happened to form on a Reddit forum called WallStreetBets.

Big Short-Sellers Get Squeezed

Whatever inspired the movement, it soon became a force of its own, like an online flash mob buying and holding shares at increasingly higher prices.  Why would anyone do this?  Many may have just gotten caught up in the excitement.

Short-selling involves borrowing a company’s shares from someone else, selling them, and then hoping the price goes down so you can buy them back at a lower price.  You then return the shares to the lender, while pocketing the difference.  If you pay more to buy the shares to settle your debt, you have lost money.  The risk of short-selling is that the maximum profit you can make is 100% (if the shorted stock goes to $0); however, the potential loss can be many times your original investment.  (Theoretically, your potential loss is unlimited if the share price keeps going up.)

If the price shoots upward, short-sellers can face margin calls, requiring them to cough up the difference between the original share value and the fast-soaring price.  Or worse, lenders can demand their borrowed shares back, forcing the short-seller to either find another borrower or buy back the shares in the open market at whatever price they can get.  In the case of GameStop, short-sellers like Melvin Capital Management lost billions of dollars meeting margin calls, which in turn became chum to the feeding frenzy.

Main Street vs Wall Street (David vs Goliath)

In typical fashion, the financial mainstream media has pitted this as some sort of epic battle between thousands of small, individual investors just trying to make a buck vs. the Wall Street/hedge fund fat cats backed up by some sort of rigged system.  Don’t kid yourself.  There were pros and sophisticated traders on both sides of this.  No novice is going to have the knowledge to orchestrate not only a short-squeeze, but an option-based gamma-squeeze on a heavily researched deep fundamental value stock.  At least not without a little help.

Robinhood Parries

As the frenzy continued, many U.S. retail trading platforms – including Robinhood, Schwab, TD Ameritrade, and others – started experiencing trading overloads.  Technical glitches, as well as deliberate trading restrictions, ensued.  Not surprisingly, traders impacted by the lapses and restrictions have cried foul, perhaps rightfully so.

Enter the Regulators

Is the phenomenon just a new, but a legal variation of a very old market mania theme?  Did anyone actually violate existing regulations, and if so, whom?  Are new regulations warranted?  Securities regulators are considering these questions, not yet resolved.

Now, to the main point.  Where does this leave YOU as an investor?

You may have noticed:   Continue Reading…

Investing themes in a post-Covid world

By Aman Raina, SageInvestors.ca

Special to the Financial Independence Hub
Update from Author:
Since I posted this in the early days of the pandemic, it’s been quite interesting to see how some of these mind maps have played out. Global supply chains are more stressed creating bottlenecks and driving prices up.  Alternative payment mechanisms and digital currencies are becoming more embraced. The exodus to suburbs has been joined. Curb-side pickup  and other retail distribution channels are being more accepted. There have been struggles in how we educate our kids and social media thanks to the ramblings of a Mad King have now come under the eye of regulatory bodies around the world. Many mechanisms will need to be refined. Even though we’re closer to getting to the other side of the pandemic, many seismic shifts I describe are still in the early days of playing out and as they evolve, investing opportunities will also emerge.  


The COVID pandemic has become the seminal moment in our lives. As of this writing, we are still well into growth phase of the virus but there are signs that the spread may be flattening out. The literal full-stop of our daily lives, socially, economically, and psychologically will be embedded in how we approach how we live, work, trade and invest much in the same way the Depression of the 30’s and the two world wars shaped the people of those generations.

What’s different is those periods were man-made. This episode has been driven by a virus introduced by Mother Nature. Unlike our parents and grand-parents, we are not hunkering in a bunker covering our ears while our countries get bombed or are being drafted to carry a gun and lie in rat infested bunker. We are isolating at home watching Netflix, baking bread, and washing our hands every 30 minutes. It’s different but I feel the impacts could be the same.

The COVID period like the Depression will also shape how we approach investing. Many research studies have delved into the investing behaviour of people living through the 30’s and 40’s and how much it shaped their decision-making and risk tolerances. The generations that are living through this period will have developed a value system, and biases that will shape their attitude, confidence, and ultimately how successful they will be as investors. We are seeing literally millions of people who have lost their jobs and livelihoods overnight. Their approaches to saving and investing will not be the same.

I’ve been thinking about how the events we are living through right now are going to influence our behaviours going forward and trying to map to how society and business will respond, adapt and subsequently mind map out possible new investing themes that could emerge. I haven’t tried to identify specific companies or stocks. In fact some companies probably don’t even exist right now. Times of stress can be viewed as opportunities. In between home schooling my kids, and answering many questions from worried people about how to manage their shell-shocked portfolios, I took a shot and put together some preliminary ideas and mind maps that may trigger some ideas to consider.

We’re not in charge

If isn’t clear now, it should be … we’re not in charge.

Up until now, the narrative regarding our earth and environment has been very superficial and revolved around the premise that the planet is getting hotter and altering our environment in profound ways. There has been an ideological debate about how valid this is. We’ve been conditioned to think that climate change is associated with extreme weather events such as hurricanes, flooding, tsunamis or mass earthquakes that level cities or bleaching of coral reefs. The other narrative that we have overlooked is at the molecular level which as we are discovering that while not as dramatic cinematically (Contagion movies not withstanding) viruses can be just as devastating. These debates are revolved on the premise that we as human beings are in charge and will dictate the rules of engagement with the planet. The planet will do what we tell it.

This is false.

What is incredibly clear is we as humans are not in charge of this narrative. The earth is … and the earth is not happy with us.  It has watched as we fumble and delay and make excuses back and forth about respecting the planet. It has watched as we put a priority over material wealth, living vicariously through Kardashiean and Justin Beiber instagram posts and immediate gratification at the cost of the health of the planet. The earth has sat there politely and taken the abuse we have unleashed upon it.

The earth has had enough of all this. It has decided to give us a timeout and sent us to our homes to isolate and think about we have done.

We’re not in charge. The earth is in charge and if we want to live happy lives, we need to respect the earth. It has called a time-out on us. It is telling us the status quo is unacceptable and that we better get our sh$t together … now. Whatever attempt we have initiated to respect the planet have been superficial and full of platitudes.

Wall Street, Bay Street, Governments of all shapes and stripes are working under a narrative that once a vaccine is created, we’ll get our injections and go back “normal.” The stock market is pricing in this narrative. I think it’s completely wrong.

It’s going to cost us in so many ways …. and it’s going to make us better in so many ways.

Whatever happens, I’m convinced that whatever comes out of this event will be inflationary in the long-term. Everything is going to cost more and it’s going to take longer. The days of being spoiled with low cost of goods made in China, India, and wherever have ended. To live and function under this paradigm will require complete rethinks on how we will exist while respecting our planet and will require significant investment and behavioural changes.   If we can identify these new paradigms then as investors we can participate and profit from these new paradigms. The core performance metric for investment decisions is making decisions that protect our purchasing power of our savings. We need to grow our savings to insulate us so we can afford the necessities we need in our older years to survive. Owning GIC’s won’t cut it. Heck we’re entering a world of negative interest rates! We will need to invest in people, ideas, goods and services. As investors we need to consider what these opportunities will look like in a post-COVID world.

The Earth is breathing better
During this time, as I walked around my neighborhood or went on what has become my more frequent jogs, I noticed how much more quiet the neighbourhood has been. The air has also felt crisper and cleaner. There seems to be less smog in the air. I thought it was just me but apparently in many parts of the world, air quality has dramatically improved as a result of the idling of the economies. For the first time in decades people in India can see the Himalayas, The traffic is quieter and I can drive to downtown in 5 minutes when it normally took 45 minutes. Who would have thought that a virus would create so much beauty in the world.

I don’t know about you but I like this and I suspect that we like this new arrangement and will want to keep it that way as much as possible.

Climate friendly products and services are now a default, not a theoretical concept. We’ve seen the proof of concept and we will want this be the status quo going forward, costs be damned.

It’s funny to watch OPEC countries trying to agree on cutting production as a result of the pandemic. It’s ironic that reduction at some point has a better chance of being permanent. Some of them are aware of it, most notably Saudi Arabia. All the arguing about oil prices is useless. They know the jig is up now. Coal, forget it. We could see a big push into electrical vehicles and solar based/geothermal forms of energy. There could be more willingness to invest in the infrastructure around it now.

Post COVID Theme – How we trade: Globalization gets re-calibrated

We have become dependent on sourcing goods from a few countries or from one part of the world. COVID has shown how risky this is. I suspect we will see a recalibration of how our goods and materials get sourced. Supply chains will become regionalized/localized. Congratulations Mr. Trump, you’re getting what you asked for, just realize that the cost of doing business will go up. With COVID, we may be more comfortable with the concept now. I expect we will be flattening our supply chains.

Post COVID Theme – How we wait: Reacquainting ourselves with time

 COVID introduced or reintroduced us to the most precious and finite natural resource we have…time. When we have time, we think, we relate, we reset, we prioritize and we appreciate what is truly important during our finite personal existence. We reacquainted ourselves with reading, playing board games, talking and sleeping. During this time, I’ve been running 2-3 times per week compared to barely once a week pre-COVID. I’m getting more sleep now, almost 9 hours versus 6, and I’m feeing totally different, more at peace and not in a rush. I like it. I’m loosing weight! Continue Reading…


Checking in on Vanguard’s VRIF

Cutthecrapinvesting: Image by Cris Ramos from Pixabay

By Dale Roberts

Special to the Financial Independence Hub

In September, Vanguard’s VRIF ETF was launched. The ETF is an all-in-one retirement funding solution. It is designed to pay out 4% of the portfolio value in 12 monthly distributions. That level of income is set at the end of each calendar year, based on the year end value. After the Santa Claus rally, it looks like VRIF holders will be getting a modest raise.

Here’s my original review of the Vanguard VRIF ETF. Simple and cost effective asset allocation portfolios can (historically) work very well to provide consistent and generous retirement income. The Vanguard VRIF option does it all for you, from portfolio management to paying out that income each month. Of course, you can also create your own ETF portfolio for retirement funding.

The key message is that simple works. And fees are important. I am a big fan of financial planning at the right cost, but keep in mind that investment fees and advisory fees will reduce the amount that your investments can deliver each year. You would subtract that percentage off the top. That’s why you might consider a fee-for-service advisor. In the end they might provide that retirement funding plan that would include an investment option such as VRIF.

The VRIF payout

The initial monthly distribution for VRIF was set at .083333 cents per unit.

As per the ETF mandate the distribution will stay the same throughout the year. The amount in your pocket includes fees and any withholding taxes within the ETF assets. It’s 4% in the clear. Of course, you would (most often but depending on your tax situation) create taxes payable from receiving the income in an RRSP, RRIF or taxable account. Within your TFSA the income would be tax free.

The performance of VRIF

In addition to paying out the monthly distributions, the ETF has also increased in price by 4.5% from inception. Continue Reading…