Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

What a market decline looks like for a balanced investor


By Scott Ronalds

Special to the Financial Independence Hub

EDITOR’S NOTE: This blog was first published on the Steadyhand site in January and is being rerun today to provide some insights into this week’s severe market downturn.

I have no greater insights than you do on what the markets might do over the next several months. But it’s been a while since we’ve had any kind of meaningful pullback in stocks and we’re due at some point. It may not happen next quarter, next year or even this decade. But as I noted in my last post, declines and bear markets are a normal part of investing. Are you prepared?

I find the best way to test yourself is with real money. Let’s say you’re a balanced investor and your portfolio is worth $400,000, all invested in the Founders Fund. A modest decline in the markets might see the fund fall 3-4% over a few months. This doesn’t sound like much. Put it in dollar terms though, and it takes on a different meaning. $12,000 to $16,000 sounds much greater – and feels much worse – than 3-4%. Still, no big deal considering the gains you’ve likely seen over the last few years.

Now assume markets experience a sharper decline and the fund drops 6% over 6 months. Your portfolio is now down $24,000. What would you do?

Would you really sit tight if things got worse?

Let’s turn it up a notch. Investors have soured on stocks and markets are under severe pressure. We’re officially in bear market territory with stocks down over 20% and the fund is hypothetically down 12% over 10 months (the fixed income component is providing ballast). That’s $48,000. The media and financial pundits are calling for further losses. Your neighbour’s bragging about how he moved to cash a year ago and is telling you to get out of the market and buy gold. Again, what do you do? Continue Reading…
Stop trying to correct for market corrections — revisited

By Steve Lowrie

Special to the Financial Independence Hub

In 2015, I published an extended series of “financial stop-doing” posts, suggesting what investors could STOP doing, if they wanted to START building more durable wealth. Almost three years ago to the day – on September 8, 2015 – my “stop-doing” post began as follows:

“Recently, the market has been playing right into an important addition to our financial “STOP Doing” list: Stop trying to correct for market corrections.”

Time has passed, but one thing has remained the same: As current overall markets have again been ticking upward for quite a while, I’m again hearing investors fretting over when the fall will arrive, and whether they should try to get out ahead of it. Since my response remains the same today as it was then, I’ll reprint it for your re-viewing pleasure, updated to reflect the most current available data.

The subject is not a new one to us. In August 2014 and again in 2015, we posted this Q&A: “Is there going to be a market correction (and, if yes, then what)? In light of current events, we’ve now updated that post with current year-end information.

Just as it takes no special skill to predict some days of sub-zero temperatures this winter, we were not being prescient when we said that we would probably experience a correction sooner or later. One need only consider abundantly available evidence to recognize that, viewed seasonally, the market frequently “corrects” itself, sometimes dramatically. It’s only when we take the long view that we can see the market’s overall upward movement through the years.

For example, consider this Dimensional Fund Advisors slide depicting the US stock market’s gains and losses during the past 35 years. The narrow lines illustrate wide swings of maximum gains and losses in any given year. The blue bars show the year-end gains and losses after the dust has settled. Clearly, far more years ended up than down, for overall abundant growth.

This illustration is substantiated by similar findings from JP Morgan.  According to their data, covering 1980–2017, the average intra-year decline of US stocks (measured by the S&P 500) was 13.8% per year, but the annual returns were positive more than 76 per cent of the time, in 29 out of those 38 years.

But first we’d like to challenge the word “correction.” We prefer to think of price volatility as simply part of doing business in the market to begin with. Ever the individual to tell it like it is, Dimensional Fund Advisor’s retired executive Dan Wheeler had this to say in one of his classic blog posts, “The Spinning ‘Talking Heads’”: Continue Reading…

Investing: An amazing concept that deserves more love

By Scott Ronalds

Special to the Financial Independence Hub

I love Google. Want to know how many grapes are in a bottle of wine? Google it. Need directions from Granville Island to Gastown? Google Map it. Want to watch James Corden’s latest carpool karaoke? YouTube it (Google’s parent company owns YouTube). A world of information is at your fingertips.

A friend of mine adores Nike. He can’t get enough of their shoes, loves their style and innovation, and thinks their marketing is brilliant. He may even have a swoosh tattooed on him somewhere.

Whether it’s Google, Nike, Starbucks, Apple or others, there are a lot of impressive companies out there doing remarkable things. And the really cool thing is that we can own a small piece of many of them. Think about this for a minute. Any individual can buy shares in a publicly-traded company and participate in its growth and success (or failure, as it may be). Investing is an amazing thing. So why do so many people ignore, fear, or just put off investing? (Reports suggest people are sitting on huge amounts of cash.) It’s a question I ask myself all the time.

Investing is simply about owning pieces of companies

I think I know some of the reasons. Investing is risky. But it’s also become confusing and scary: which makes it prime fodder for the media. Corporate and economic figures are dissected with minutiae. Stock prices are updated every millisecond. The lexicon can be baffling (the Steadyhand Dictionary can help you make sense of it). Complex algorithms and trading strategies have emerged. The use of derivatives and leverage have amplified the risks. Unethical practices have been exposed. The whole system has been called rigged. Continue Reading…

What and Who are the Canadian Robo Advisors?

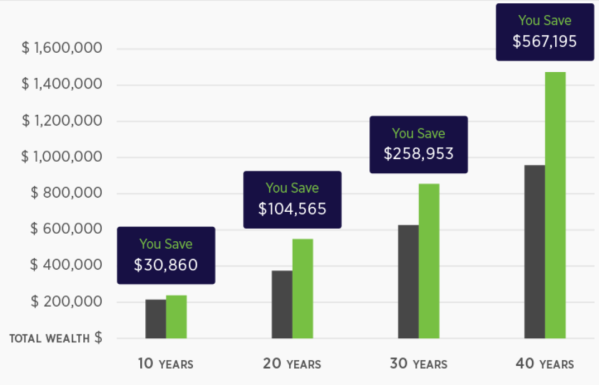
But just because you might need an advisor does not mean you have to pay some of the highest investment fees in the world. And yes the fees are important. We know that the fees typically and greatly impact the returns. From Justwealth the chart at the top is a comparison of the potential portfolio returns impact over longer periods, based on an initial $100,000 investment.

We can see that the effect of high fees paid can become exaggerated over time. Remember you pay investment fees every year, throughout the year, and as your portfolio grows over time you pay more in fees as the fees are based on your portfolio value. That’s a nasty kind of negative compounding.

So just what is a robo advisor?

Yup, just as per the image, a robo advisor is an investment advisor that’s well, not human. But don’t be scared. If you want to talk to a human the companies that offer robo advisory services can also put you in touch with real flesh and blood advisor types.

So if a robo advisor is not human, just what is “it”? A robo advisor is simply an online platform that asks you questions to help you get into the right investment portfolio. A robo advisor will ask the same type of questions as would a human advisor. Based on your answers the robo advisor will put you in the appropriate portfolio.

So what type of questions will the robo advisor ask you?

The robo advisor platform may try and gauge your investment knowledge. There may be questions on your net worth and salary and employment status, basic personal details. Each robo advisor offering has its own nuances and I will dig deeper into that in future articles. But most importantly a robo advisor wants to know …

  1. Your time horizon for the monies that you are about to invest.
  2. Your tolerance for risk (the amount or percentage that the portfolio could decline).
  3. Your objectives for the investment, whether you’re looking for more growth, a more balanced approach or a very conservative approach that might include a lot of bonds and fixed income.

And once again, each robo advisor will have its own methods (robo personality?) for asking those questions and discovering your investment personality and needs. If you want to ‘play around’ with a basic robo question and answer process have a look at Tangerine Investments’ Portfolio Selector Tool. Continue Reading…

Abenomics: A Strong PM, Abe should deliver positive pro-growth policies

By Jesper Koll, WisdomTree’s Head of Japan
Special to the Financial Independence Hub
Japanese prime minister Shinzo Abe was recently re-elected as the ruling Liberal Democratic Party (LDP) leader, winning by a very solid 70-30 margin against his one internal competitor. Abe thus has a very strong internal party mandate and will continue to be Japan’s prime minister for another three years. This bodes well for Japan’s economy in general and Japanese risk assets in particular. From here, two specific forces should combine to allow a Nikkei rally toward the 30,000 level over the next six months:

1. Pro-growth policy surprises

2. A sharp upturn in the momentum of positive earnings revisions

While the bull case for Japan equities recently has become more of a consensus view, much of the investment case rests on extremely attractive valuations: TOPIX price-to-earnings (P/E) multiples appear to be back toward the bottom 5% of the range in the past decade.

The big worry: Is Japan a “value trap” with no added “positive surprises” in store to unlock the value? This is where PM Abe’s third term plays an important role as a catalyst: against very low expectations that Abe will do anything new or interesting, we expect “Team Abe” to deliver new proactive policy initiatives relatively soon, and with a sense of urgency.

Specifically, we look for the following:

1.) A new supplementary budget, adding as much as ¥5 trillion (about 0.9% of GDP) to domestic demand

The need for this stems from the various natural disasters that hit Japan over the past six months. About half of the funds should go toward regional reconstruction, but the other half is likely to be earmarked for nationwide disaster prevention measures. There appears to be broad-based consensus for the need of added spending within the ruling coalition, and projects are basically “shovel ready.” Expected timeline: mid-October at the latest. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.