Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Top 10 Rules for successful Retirement Income Planning

By Doug Dahmer

Special to the Financial Independence Hub

As a Retirement Income Specialist, I have spent the past 10 years helping those transitioning from their savings years to their spending years to discover the secrets of how to optimize their future income streams, while minimizing the amount of taxes they pay. These years of experience have provided me with a great number of valuable lessons. I have reduced this learning to a list of top 10 success rules for retirement income planning.

In a world where (unless you work for a government agency – police, nurses, teachers, government employees etc.) the guarantees of a corporately sponsored retirement income stream have virtually gone the way of the dodo bird. Corporate defined benefit pension plans have been replaced with defined contribution plans and group RRSPs.

Upon retirement, the vast majority of baby boomers are now faced with the daunting challenge of determining how to convert a large lump sum of accumulated retirement savings into a recurring income stream that lasts as long as they do. These risks and responsibilities were previously carried out by disciplined and talented pension plan managers. They have now been quietly delegated to the individual – and this has occurred without providing the adequate tools to perform the tasks.

It is my hope that the following 10 rules are helpful to those who have been left to their own devices to cobble together a safe, secure retirement income.

1.) Take ownership in your future success

A plan is not a plan until, the people who have to live with the choices contained in the plan, have played an active role in crafting these choices. The level of commitment one has toward following the prescribed progression of choices contained in the plan is directly proportional to the confidence you have that these choices will lead to successful achievement of the life outcomes most important to you. By taking ownership in your own plan helps keep you focused on the aspects of your life you have control over — choices — while identifying the need to put protective mechanisms place to mitigate the potential damage of events that are beyond your control.

2.) Your Retirement Income Formula is not a static product

Retirement Income Planning is not a “One and Done” event. It is also not an exact science. Every pilot before leaving the ground files a detailed flight plan knowing full well that no flight has ever gone according to plan. The pilot must constantly monitor where they not only relative to their desired destination but also relative to their original flight plan. Retirement Income Planning, like flying, contains no roads to follow or signs to provide directions. Wondering too far off course can lead to mid-air collisions or running out of fuel. Confidence in your Retirement Income Formula comes from testing it, stressing it and constantly re-adjusting it, as life unfolds. Only by engaging in a planning process that evolves with your life, will you achieve success and security. As daunting as this may sound, like filing a flight plan, when you have access to the right tools this task can be made significantly easier.

3.) Link your life plan to your financial plan

The key to financial success in the second half of life is to directly connect your desired life plan to your investment plan. If your money managers do not have an intimate understanding of your year-by-year cash flow demands or the specific portfolios you plan to source these funds from, you are not getting the level of protection – or service – that you deserve.

4.) Create forward knowledge of how much you need and when

Better financial decisions will always be made when you have advance knowledge of the what, the when, and the how much of your desired lifestyle. People who blindly chase the unknown savings target of “more” are the people who make the most financial errors.

5.) Don’t trust your future to outdated ‘rules of thumb’

Conventional wisdom that served past generations well, is no longer applicable. Baby Boomers are in the process of redefining retirement. Governments are having to respond to the financial implications of a rapidly aging society. Within this state of flux, tremendous new opportunities exist for those who find them. Devastating risks await those who fail to recognize the new reality. Probably the largest mistake baby boomers are currently making is the date they choose to start their Canada Pension Plan. A poor start date choice can frequently cost the average couple well over $100,000 over the balance of their lives.

6.) Embrace variables, not averages Continue Reading…
4 investment strategies every stock investor should consider

By Sia Hasan

Special to the Financial Independence Hub

Portfolio managers and analysts believe that no one investment strategy outweighs the rest. Instead, every game plan has its unique strengths and weaknesses. As such, it’s up to investors to choose the tactic that best works for them. It’s worth taking time to learn to develop strategies if you are considering investing in bonds or stocks. Some of the stock and bond investment strategies include quantitative, algorithmic trading, value investing, growth strategy, GARP investing, and collar options strategy.

Quantitative, Algorithmic Trading

Quantitative, algorithmic Trading involves selection of an investment based on mathematical analysis. In fact, investors don’t need to consider other factors such as how a business operates. All they need is to analyze different variables that correlate with each other to create an algorithm that can help predict how stock or bond prices will change over time. Quantitative, algorithmic trading is one of the newest investment strategies that have become popular in the past few years. It allows investors to engage in different investment styles and come up with a thesis, variables and set of data that they can use to identify and exploit market inefficiencies. It’s up to the investors to develop a model, test it with historical data, and implement it to see if it works. Algorithmic trading is ideal for investors with some mathematical and computer programming background.

Value Investing

Value investing is a strategy where an investor buys stocks that are grossly undervalued. Buying stocks that trade for less value than their net assets and cash profits allows the investor to limit the amount of money he or she could lose on an investment. The strategy is ideal for investors who believe that the market overreacts to emerging trends, resulting in a price decline that doesn’t correspond with an investor’s long-term fundamentals. The stock price could decline beyond its fair value when a market overreacts to bad news. As such, an investor can take advantage and buy stock, and wait for its value to return to its optimal level.

Growth Investing

Growth investing is a more aggressive investment strategy that focuses on capital appreciation. It involves investment in stocks or bonds that exhibit signs of growth even if their current share price seems high. Investors are anticipating that stocks and bonds will grow in value and offset the premium they will pay for the investment. However, this is an aggressive investment approach that investors regard as both highly rewarding and highly risky. Investors have to be confident about the growth and competitive strength of a company to justify that its share value will grow in the future. Growth investing strategy is ideal for futurists who are confident that stocks or bonds will increase in value over time.

Growth at Reasonable Price Investing (GARP)

GARP (Growth at a Reasonable Price) is a hybrid of growth and value investing strategies. However, analysts have often stated that value and growth-based investment strategies are joined at the hip. In fact, there is little difference between growth and value-based investment strategies. The growth of a company will always impact its fair value. It is far better to buy highly valued shares at a fair price than to buy undervalued shares at a lower price. GARP strategies enable investors to identify stocks and bonds that are priced reasonably. As such, they can benefit from the stock’s growth potential as well as enjoy protection against price deviation.

It’s important to note there is no one investment strategy that is best for everyone. What matters is whether the investment tactic is a good fit for your company or not. However, nothing is worse than being inconsistent with each of your investment strategies. You can hardly find the source of error that could be increasing your costs if you invest in different philosophy each time. However, it is vital to minimize your trading costs irrespective of the investment strategy you adopt.


Sia Hasan is a tech entrepreneur by day, and a freelance writer by night. Her passion lies in business technology, efficient and sleek programming, and customer relationship management. When she doesn’t have her nose pressed against her computer screen, you can find her spending time with the loves of her life, her two dogs, Pixel and Vector.

Is it wise to sell in May and go away?

“Sometimes it’s necessary to go a long distance out of the way in order to come back a short distance correctly.” — Edward Albee (1928–2016), American playwright

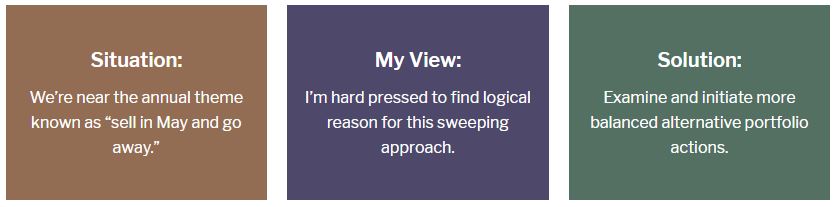
Investing plans that pursue flavours of “sell in May and go away” are not vanishing anytime soon. Simply said, the catchy tune is about to ignite the annual rounds once again. Strategies that believe stock investing from November to April have better prospects than other months.

Keen followers of this practice typically sell their equities around May, such as stocks, mutual funds and ETFs. They then repurchase equity investments near November.

“I don’t recommend clearing the deck willy-nilly. Drastic actions are seldom wise replacements for long-term strategy.”

I’m fully on board with the excitement of getting away to a variety of travel destinations. That is the “go away” part. On the other hand, I just don’t buy into the questionable wisdom of selling the nest egg. For me, the “sell in May” part needs much closer scrutiny. Particularly, outlays of disposition and acquisition. Income tax implications also play a part.

Let’s be clear about the strategy. An investor unloads the entire portfolio, then acquires the new version a few months later. This process is repeated year after year, after year. Sounds like quite a heap of cash to shell out for transactions and tax implications.

Potential pitfalls

If only investing were that simple! Examining these pointers helps assess the prudence of wholesale selling: Continue Reading…

What’s your real Risk Tolerance? Chinese Face Reading tells us Listen to your Ears

By Jane Hawley Edward

Special to the Financial Independence Hub

My Google search for “choosing a financial advisor” yielded more than 30 million hits. It appears to be a popular topic. The recommendations over the first 20 pages were variations on:

Education and Experience

Compensation and potential conflicts of interest

Investment suitability to the client

Yet I propose another characteristic for consideration; one that can quickly help assess one’s risk tolerance and show whether a client and advisor are compatible.

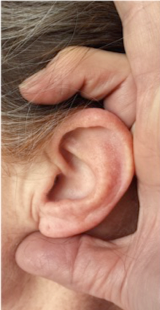
It comes from the ancient Chinese science of Face Reading, where ears are the physical feature that shows how much innate courage and risk-taking ability a person has. The larger the ear, the more comfortable they are gambling physically, in their choice of work or taking risks with money.

To understand the kind of risk-taking you can naturally handle, all you have to do is measure the size of your ear.  Measure it by holding your thumb and index finger in a “C” up to your ear. If it matches in size, you have a small ear.  A large ear is the size of your thumb and middle finger formed into a “C”. A medium ear is between those two sizes.

The broader your ear is across the top, the more comfortable you are with financial and emotional risk.  Chances are that you would be the type who would be more willing to try aggressive growth stocks or volatile markets for potentially larger gains.

In contrast, if your ear is narrow across the top, you’d tend to be a conservative and cautious investor. Your preference would be to invest in safer low-risk vehicles because your main goal is to preserve savings because you feel the pain of losses more intensely than the comfort of gains.

Matching to your financial advisor’s

That’s where matchmaking our ears to our financial advisor’s gets interesting.  A client with cautious, narrow ears may be most comfortable with a similarly narrow-eared, like-minded advisor.  But there’s merit in matching opposite traits; a wide-eared advisor could construct a portfolio that offers protection plus opportunity for moderate growth.  Or a narrow-eared advisor could help curb a high-risk tolerant client from gambling on a poorly diversified portfolio or too speculative an investment.  In either case, together they could temper each other’s risk taking appetite.   The main point is to know what each brings to the equation. Continue Reading…

How Finance Apps & Online Tools will revolutionize Millennial Financial Planning

By Drew Hayles 

Special to the Financial Independendence Hub

When you’re young, you feel like nothing can stop you. You’re in charge of your own destiny.

Things might look different in hindsight, but don’t worry about that now. The most important thing you can do right now is set in motion a plan to achieve financial independence as soon as possible. With the means to do what you want, when you want, you’ll open doors you never even knew existed.

Before you begin in earnest, make sure you have the right digital tools and apps in your corner. These user-friendly resources all have their place in a coherent, comprehensive financial independence plan, provided you use them properly and consistently.

Perhaps you’re using a few already.

 Digital Budgeting Tools: All Your Money in One Place

 This list of the “best simple and free budgeting tools” doesn’t get to actual digital solutions until the third entry, when it calls out the trusty old Excel spreadsheet.

If you’re in the market for something a bit more robust and hands-off than a wall of spreadsheet cells, consider later entries like Mint or PearBudget (which, to be fair, began life as an Excel tool).

These aren’t professional-grade tools by any means, but they’re nevertheless robust enough to accommodate basic household budgeting and ensure that you spend well less than you earn. Remember to download mobile versions and link your bank accounts for automated cash flow tracking.

 Automated Savings Apps: Ditch the Reminders

 Tired of remembering (or forgetting) to make regular savings deposits? Take the uncertainty out of the process with automated savings apps that quietly transfer small sums to your savings accounts without any input on your end.

Tools like Digit exist wholly for this purpose. More robust online banking solutions like Chime Bank typically have built-in automated savings features that round up every debit transaction to the nearest dollar and sock away the difference

 Educational Videos: DIY, But for Money

 Are you a DIYer at heart? You can learn a lot from high-quality investing and financial education videos. After all, there’s no need to pay for entry-level information and strategic advice when you’ve got a YouTube account to your name. If you need help or want to learn more about specific topics, you can always go straight to the source with questions.

Lightweight Accounting Platforms for Entrepreneurs   Continue Reading…