Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

How are robo-advisers any different from global balanced mutual funds?

Depositphotos_6444034_xsBy Jonathan Chevreau

I’ve long been baffled about why the plain-vanilla global balanced mutual fund has not done better in the marketplace.

As I note in my monthly online ETF column at the Financial Post (link below), a global balanced fund (or Global Tactical Allocation Fund) or their ETF equivalents give you exposure to all major asset classes, geographies and industries. You probably have at least two professional managers fretting on your behalf about the underlying stocks and bonds, rebalancing the asset classes, etc.

In short, a global balanced fund should in theory be the mythical “only fund you’ll ever need.” But in practice, and as I note in the column, show me even one investor who has 100% of their portfolio in just one of these funds. Talk about a black swan!

Taking it further, for all the media coverage that robo-advisers have garnered over the past year (and I’ve written a lot about them, both here at the Hub and elsewhere: put robo adviser in the search engine to the right to retrieve them), how exactly is an ETF-based robo adviser different than a global balanced fund?

Just asking! (And if you have the answers, feel free to post comments below.) The first person who can prove to me that 100% of their investment portfolio is in a single global balanced fund will receive a free signed copy of Findependence Day. I’m pretty confident no one will take me up on this offer!

You can find the full FP piece here under the headline (hey, it starts with my name!) Jonathan Chevreau: Where are the ‘robo-like’ Global Balanced ETFs in the Canadian market?

Earlier ETF columns

Links to the two earlier instalments of this new monthly column are highlighted below: Continue Reading…
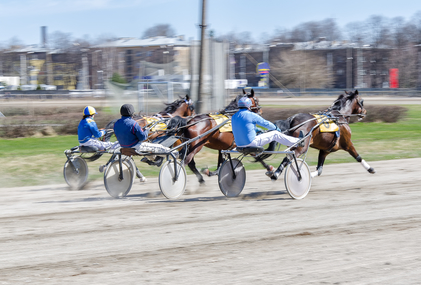
Of harness racing and asset allocation

Harness racing. Racing horses harnessed to lightweight strollers.
Harness racing: go Horse #5!

Here’s my latest MoneySense blog, which bears the headline When dividend investing trumps a balanced portfolio.

That’s an accurate depiction of the content but here at the Hub we’re sticking with the more offbeat headline used above. Because this column really does begin with a true story about harness racing in Florida.

How can that possibly relate to asset allocation and dividend investing? Click the above link to find out, or the Hub’s version below. And yes, the happy winner depicted below clutching a winning ticket is my wife, Ruth Snowden.

She’s known in her industry by that name. When we got married more than a quarter century ago she was concerned I might take offence that she didn’t want to use my surname in business circles. My response won’t surprise those who know us: “Honey, you can call yourself whatever you want as long as you pay half the mortgage!”. Of course, the mortgage has long been paid off, consistent with the Hub’s philosophy that “the foundation of Financial Independence is a paid-for home.” Continue Reading…

What Your Life Insurance Broker May Not Be Telling You

chantal-marr-findependence-hub
Chantal Marr

By Chantal Marr

Special to the Financial Independence Hub

Before you make an appointment with a life insurance broker you may want to educate yourself about how the system works, particularly with regard to the commissions brokers can get. Although extra incentives and bonuses for insurance brokers are getting talked about more in Canada, there is a lot the general public still doesn’t know. You may be interested in finding out exactly what your life insurance broker may not be telling you.

Most Canadians aren’t even aware of insurance kickbacks for brokers; and if they are, they don’t fully understand what they are, or where and when they take place.

The reason for this is because life insurance companies don’t advertise it, and neither do the brokers themselves. In fact, you’ll see that it could be said that the brokers appear to be more in control of the situation than the actual insurance companies.

Bonuses and Incentives for Life Insurance Brokers

The reason for giving kickbacks to life insurance brokers is that the insurance companies give them these extras so they will only promote their policies to their clients. So most brokers end up only offering consumers policies from a couple of insurance companies, not a selection.

Which of course, doesn’t benefit consumers – who in essence are helping to pay for these extra benefits.

Examples of Incentives for Brokers Continue Reading…

Let’s give the word Retirement an early Retirement

Here’s a piece I did recently for Money Magazine, entitled Let’s retire the word Retirement. For the convenience of one-stop shopping and archival purposes, I’ve also reproduced the piece below, with a few changes and links added since it was originally published in the current issue of the magazine.

By Jonathan Chevreau

This magazine, like its sister web site and its competitors, is devoted to the topic of money. That’s an obvious statement but stay with me.

We all need money to live, both in the present and the future. This basic fact has created the entire financial industry, dedicated to the notion of saving for a rainy day so we’ll have enough money both for today’s needs as well as tomorrow’s. And the week after, the year after that and so on, bringing us ultimately to the concept of Retirement.

Retirement is the greatest marketing bonanza ever conceived for the financial industry. If a mutual fund company, bank, insurance firm or ETF maker runs an ad, what is the major concept behind its marketing?

senior couple of old man and woman sitting on the beach watching
How Advertising portrays Retirement

Typically, it features a mature couple frolicking on a beach or golf course, care-free, active, smiling, still in love and doing nothing that resembles work.

I don’t know when work acquired such a bad reputation but I’d venture  to say that in Canada, this phenomenon started to gather steam when London Life popularized its Freedom 55 campaign. Continue Reading…

Weekly wrap: Social Security a House of Cards?, under-saving Americans & workaholic Boomers

at the Netflix "House of Cards" Season 2 Special Screening, DGA, Los Angeles, CA 02-13-14
President Underwood wants to take away your Social Security

By Jonathan Chevreau

If you’ve been binge-watching the new third season of House of Cards on Netflix, you’ll know that the nefarious Frank Underwood — now the fictional president of the United States — has decided Social Security is a luxury the nation can no longer afford, as is Medicare and Medicaid.

Instead, a new program dubbed AmWorks (for America Works) aims to provide a job for anyone who wants one. The Washington Post poses the question Could the House of Cards America Works program actually work?

Probably not, but there’s been a lot of online commentary on the very notion of killing the 80-year old Social Security program, given how many Americans have little retirement savings resources other than it. One is this piece from the Independent Women’s Forum, entitled House of Cards gets Social Security policy right, but messaging wrong.

If the prospect of losing Social Security doesn’t frighten you, maybe this will:  New York Times reports that many Americans will run out of money in retirement unless at least two things happen: one, they need to save more, and two, what money they do need to save needs to be invested more wisely, which means avoiding high-fee mutual funds. It blames mutual fund expense ratios of 1.12% of assets and that’s in the United States. Canadian mutual fund MERs are roughly twice that high.

So the solution is to just keep working, perhaps in an Underwoodian variation of AmWorks? Not so fast! Personal finance author and columnist Helaine Olen writes an insightful piece in Slate on what she calls the “Semi-Retirement Myth.” As the online site puts it, “Don’t buy the tales of meaningful work into your 70s. Your retirement is inevitable — and bleaker than the last generation’s.”

Better hope for “Freedom Six Feet Under.” Unfortunately, as the Hub’s Longevity & Aging section continually reminds us, odds are we’re all going to be living longer and healthier than we once may have imagined. Perhaps the canary in the coal mine is Irving Kahn, who passed away last week at age 109. One of the world’s oldest active investors, Kahn was around to experience the crash of 1929. Here’s the obituary from the Telegraph.

On the same subject, sadly comes news of the death of Thomas Stanley, co-author of the groundbreaking bible of personal finance, The Millionaire Next Door. Here’s a good tribute on him from the New York Times.

Globe & Mail on Reforming Retirement

North of the border, the Globe & Mail has been running a series on reforming retirement. Last week it weighed in to the TFSA debate. Continue Reading…