Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Don’t mix Politics & Investing but financial community thinks a Trump victory more positive for Stocks

Top investment executives told a webinar held Wednesday morning that investors should not mix Politics and Investing. Even so, while market observers at Franklin Templeton view the upcoming U.S. election as essentially a “toss-up” they seem to believe that a victory or sweep by the Republicans’ Donald Trump would be more positive for stocks than a Kamala Harris win.

Grant Bowers, portfolio manager and Senior Vice President for Franklin Equity Group, said “it’s a 50/50 tossup for the presidential winner. Both candidates are well known so it’s not surprising” there’s been little market volatility in the runup to the November 5th election. Generally, he’s bullish no matter the outcome.  The economy did well in Trump’s first term while a Harris victory would be a continuation of Biden policies. The real differences are on tariffs, fiscal policy and regulation. “The most likely outcome is a split government” but there would be more volatility if there is a sweep by either party.

Of course, it’s quite possible that investors won’t know the official outcome for several weeks. If the process of counting votes drags on and there are legal challenges like there were in 2020, investors can expect more protracted volatility.

Sonai Desai, Chief Investment Officer for Franklin Templeton Fixed Income said the U.S. economy is set to do “quite well. I agree there’s a reduced probability of Recession: that’s not our baseline for a while.” If there’s a Republican sweep and broader tariffs measures introduced by Trump, “that might limit the Fed’s appetite for massive rate cuts.”  Her baseline is that even with a Republican sweep, there won’t be a literal imposition of tariffs: that didn’t happen in 2016, so “I don’t think we will get the full range of cross-the-board tariffs.”  Either way, the mighty U.S. consumer will “continue to consume and I don’t see that changing with the Election.”
Clearbridge’s Jeffrey Schulze

In the very long run, of course, any short-term market volatility from elections is likely to be a blip, which is why Franklin Templeton tells clients not to mix investing and politics.

In an analysis released early in October, Clearbridge Investments Head of Economic and Market Strategy Jeffrey Schulze, CFA, showed the following annual returns for the S&P500, all positive for equities no matter which party wins and whether or not they get full control or are in a divided government. Based on that, the best outcomes for investors would be a Democratic president with a Divided Government or Full Control by a Republican president.
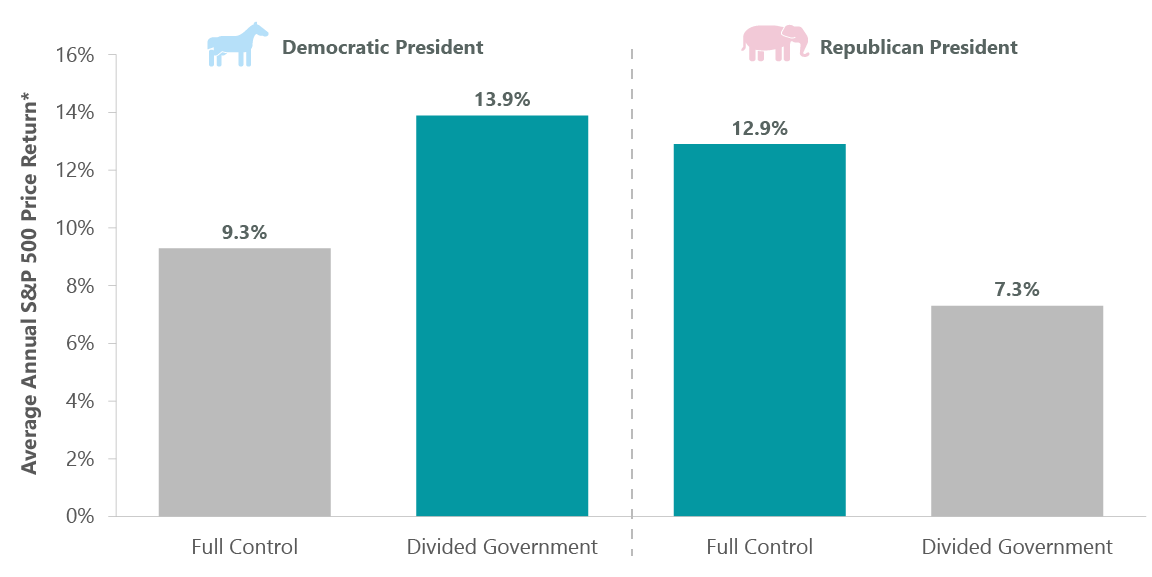
“We view a Trump win, likely coming in a sweep scenario, as net positive for equities as it preserves favorable corporate tax treatment and builds on tax elements that expired,” Schulze wrote in the October 1st update, “A Harris win, likely coming with a divided Congress, would be mildly negative due to fewer provisions of expiring tax legislation getting extended due to political gridlock.”

Trump win likely positive for Stocks

“In aggregate, we view a second Trump presidency under a sweep scenario as net positive for equities. The expectation is for a more favorable corporate tax regime and less of a regulatory burden, both of which should boost corporate profits. Conversely, there is the potential for increased tariffs and retaliation from U.S. trade partners … We view U.S. stocks as best placed under Trump, with banks and capital markets, as well as the oil and gas complex, well positioned due to lighter regulation. Aerospace and defense is also likely going to benefit as well as biopharmaceuticals. Areas that could see pressure are restaurants and leisure, due to the less availability of labor, as well as EVs, autos and clean energy producers.”

Harris win might be “mildly negative” for Stocks

A Kamala Harris win would be less positive for U.S. stocks, Schulze writes: “We see a Harris win as mildly negative to equities should she preside over a divided Congress. It will be more of a headwind to the markets should we see a Democratic sweep as she will then be able to implement higher taxes on corporations and high-income individuals, as well as push a more ambitious regulatory agenda. However, tax credits for low-income individuals would provide an offset, creating an economic boost to this segment of the economy.Tighter regulation could weigh on biopharmaceuticals, banks, capital markets, energy as well as mega cap technology. But again, we caution against basing investment or portfolio positioning solely on the regulatory environment. Areas to be bullish about under Harris would be consumer discretionary, specifically restaurants & leisure, home building and building products.”

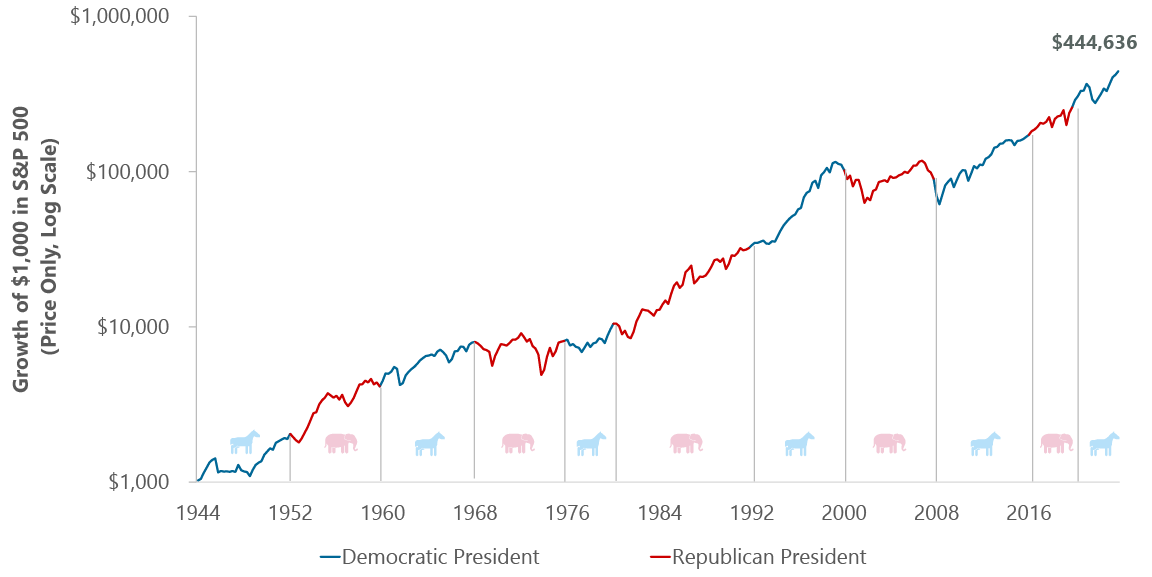
Generally, Franklin Templeton continues to advocate a “stay the course” stance for investors geared to the long term. The chart below shows that going back to 1944, the U.S. stock market has risen steadily over time regardless of which political party is in the White House.


Stephen Dover, chief market strategist and Head of Franklin Templeton Institute, acted as Moderator in Wednesday’s webinar, fielding audience questions. He also wrote a U.S. election update earlier this month, headlined “Uncertainty Reigns.”
He concluded back then that the election remains  “too close to call. A divided government in Washington, DC, with no single party controlling the White House, Senate and House of Representatives is likely … Investors should gird themselves for uncertainty and potential bouts of volatility preceding and following election day. It is quite possible that the outcome for the presidency will not be settled until the December 17 certification deadline.”

Dover expects market uncertainty to continue well past November 5th, if not until January’s inauguration of the ultimate winner.”Legal challenges, some of which have already commenced, add to uncertainty. Re-counts, delays and disputes over certification of results, alongside courtroom litigation are virtually assured if state election outcomes are close. Various legal and procedural challenges are likely to endure until at least December 17, which is the deadline for state certification of the presidential election results and the official nomination of state electors to the Congressional certification on January 6, 2025.”

However, Dover says his basic investment conclusions remain unchanged. They are as follows: Continue Reading…
What are Canadian Depositary Receipts (CDRs) and should you invest in them?

Are CDRs the better way to hold U.S. investments? What are the pros and cons?

TSInetwork.ca

Canadian Imperial Bank of Commerce (CIBC)’s Canadian Depositary Receipts (CDRs) give investors the opportunity to buy shares and/or fractions of shares in any of a number of U.S. or other foreign companies, in bundles that start out trading at a price of about $20 Cdn. each.

CDRs come with a built-in hedging feature that reduces exchange-rate fluctuations. This feature costs you 0.60% of your investment yearly.

CDRs let you invest small sums in U.S. or other foreign stocks, some of which have exceptionally high per-share prices. (For instance, Nvidia recently was trading for $475.06 a share.) Note, though, that with highly liquid stocks like Nvidia, or the other shares underlying CIBC’s CDRs, investors can easily buy, say, just one or two shares if they want.

CDRs represent shares of U.S. or other foreign companies but are traded on a Canadian stock exchange in Canadian dollars.

CIBC currently offers about 47 CDRs that trade on Cboe Canada (formerly NEO Exchange). Here’s just a few of them:

  • Alphabet Canadian Depositary Receipts – GOOG
  • Amazon.com Canadian Depositary Receipts – AMZN
  • Apple Canadian Depositary Receipts – AAPL
  • Meta Platforms Canadian Depositary Receipts – META
  • Microsoft Canadian Depositary Receipts – MSFT
  • Netflix Canadian Depositary Receipts – NFLX
  • Nvidia Canadian Depositary Receipts – NVDA
  • PayPal Canadian Depositary Receipts – PYPL
  • Starbucks Canadian Depositary Receipts – SBUX
  • Tesla Canadian Depositary Receipts – TSLA
  • Visa Canadian Depositary Receipts – VISA
  • Walt Disney Canadian Depositary Receipts – DIS

Cboe Canada is recognized by the Ontario Securities Commission.

An individual CDR is not intended to equal the cost of a single share. Instead, each new CDR started out trading at around $20 Cdn., representing ownership of one or more shares and/or a fraction of one share of the underlying stock, depending on the stock’s price. As mentioned, shares of many of the largest companies in the world trade at significantly higher prices, although some trade much lower as well.

Dividends paid on the shares underlying CDRs will be passed through to CDR investors in Canadian dollars when received, based on the current foreign exchange rates.

The main negative about CDRs is the Fees

CIBC charges no direct management fees for CDRs. However, the CDRs are hedged against movements of the U.S. dollar relative to the Canadian dollar. That means the Canadian-dollar value of the CDRs rises and falls solely with the movements of the underlying stock.

Of course, hedging has costs: and hedging against changes in the U.S. dollar only works in your favour when the value of the U.S. dollar drops in relation to the Canadian currency. If the U.S. dollar rises while your investment is hedged, that reduces any gain you’d otherwise enjoy, or expands any loss. Continue Reading…

Smart tips to Recession-Proof your Household Finances

Image by Pexels

By Jim McKinley

Special to Financial Independence Hub

With economic uncertainty looming, taking control of your household finances is more important than ever. Preparing for potential downturns doesn’t mean drastic lifestyle changes: it means implementing smart, practical strategies that safeguard your financial well-being. By making a few savvy adjustments, you can create a solid buffer that shields your household from the effects of a recession while keeping your long-term financial goals on track.

Launch a Side Business

 Starting a side business can be a powerful way to add extra income and recession-proof your finances. Whether you’re leveraging a hobby, tapping into a specialized skill set, or exploring new opportunities, a small business can provide a flexible, low-risk way to diversify your income. Consider ventures that align with your interests, such as freelancing, consulting, or offering home services, which tend to remain in demand even during tough times. By starting small and focusing on industries that offer consistent value, you can gradually build a side income that provides financial stability when it’s most needed.

Pay Down your Debt

Paying down debt is one of the most effective ways to strengthen your financial position ahead of a recession. High-interest debt, such as credit-card balances or personal loans, can quickly eat into your budget, making it harder to manage everyday expenses when the economy tightens. Focus on prioritizing payments to reduce or eliminate this kind of debt, starting with the highest interest rates. This not only frees up more of your income but also reduces financial stress. By becoming less reliant on borrowed money, you can better weather potential income fluctuations and maintain greater control over your finances.

Organize your Financial Records

Organizing your financial records can have many benefits, such as improved efficiency, better decision-making, and easier access to important information. Digitizing your documents can help you keep track of them more easily, save space, and add an extra layer of security to protect against theft or damage. After digitizing your records, try the process of splitting PDF content to break  a document into smaller, more manageable files. Continue Reading…

Preparing your Successors for Continued Financial Success

Discover essential strategies and insights into succession planning to ensure a smooth transition and ongoing financial success for your small business.

Adobe Stock: Prostock-studio

By Dan Coconate

Special to Financial Independence Hub

 As small business owners approach early retirement, ensuring the continued financial success of their business becomes a top priority. The journey of building a business is filled with hard work, passion, and dedication.

To ensure that successors are prepared to carry on the legacy and achieve ongoing financial success, delve into these essential strategies.

Succession Planning

Succession planning is a critical part of preparing for retirement. Identifying potential leaders within the team early on and providing them with opportunities to grow is key. This includes offering challenging projects, exposing them to various aspects of the business, and involving them in key decision-making processes. An effective succession plan ensures a smooth transition and continuity when the time comes for new leadership to take the reins.

Financial Literacy Training

Financial literacy is indispensable for any leader aiming to drive business success. Investing in comprehensive financial training programs that cover budgeting, financial analysis, risk management, and strategic financial planning is crucial. Developing a strong grasp of financial principles equips future leaders to make informed decisions that positively impact the business’s bottom line.

Executive Coaching

Executive coaching plays a significant role in developing leadership skills and ensuring alignment with business goals. There are several benefits to offering personalized executive coaching sessions, whether led by you or a third party. It’s an easy way to help potential leaders enhance their decision-making abilities, improve their emotional intelligence, and refine their leadership style. Continue Reading…

The verdict is in: Canadian investors value financial advice

Image: Deposit Photos

By Mario Cianfarani, Vanguard Canada

Special to Financial Independence Hub

We recently conducted a “Value of Advice” survey of Canadian investors that reinforced to us how important financial advice really is. We found that while advisors enjoy high levels of client satisfaction and loyalty, younger investors are increasingly opting to manage their assets themselves through online discount brokerages and digital services.

Among Canadian investors, 44% feel their advisor provides high value, and 74% believe their financial advisor is worth every dollar they pay. Additionally, 71% say they plan to remain with their current advisor, with that figure rising to 80% among those aged 55 and over.

While these results were not surprising, the level of trust that financial advisors enjoy is changing with a cohort of younger investors. Among those aged 18-34, 40% use online platforms for investment management, while only 38% rely on financial advisors. By contrast, 70% of those over the age of 55 use a financial advisor, with only 17% turning to online platforms.

A Tale of 2 Investors

It’s clear that Canadian investors highly value financial advisors and the guidance they provide. However, there is a tale of two investors split by age in terms of the duration, method and frequency of financial advice they receive.

This presents both a challenge and opportunity for financial advisors to provide more holistic wealth management services and relationship-oriented advice to younger investors.

While younger investors are more inclined to go digital with investing, they also show a significant level of hesitation. Among younger investors, 35% report not fully trusting their financial advisor. When asked whether they can manage their own investments, many admitted to lacking the time (47%), knowledge (39%), or confidence (42%) to do so effectively.

The study highlighted that financial advisors remain the preferred source of advice for most Canadians, regardless of age. In fact, 89% of investors report that their go-to source for financial information and advice is their financial advisor or bank. Moreover, human advisors are perceived to deliver better investment returns, with 44% of respondents believing that human advisors generate higher returns, compared to only 9% who hold the same view of robo-advisors.

Almost half in regular touch with advisors feel optimistic about their financial future

The data revealed that frequent communication with clients is shown to make a significant difference in client satisfaction and optimism. Among those who communicate with their advisor monthly or more, 46% feel optimistic about their financial future, compared to just 18% of those who communicate only once a year. Additionally, 40% of those who have a financial plan created by an advisor express a high level of optimism about their financial future, compared to only 22% of those without a formal plan.

We have been looking at the impact of financial advice for more than 25 years and the utility and benefits are the same.

As the investment landscape evolves, financial advisors will need to focus on building trust, maintaining regular communication, and emphasizing the value they provide in an increasingly digital world. Doing so will enable them to serve both traditional and younger investors more effectively, today and in the future.

Mario Cianfarani is head of distribution for Vanguard Canada. Most recently, Mario was head of national accounts & institutional sales and was previously head of ETF capital markets. Before joining Vanguard in June 2015, he was a portfolio manager at First Asset Investment Management, responsible for domestic and global equity ETFs and sector-based, North American covered call ETFs. Mario has held senior sales and trading positions with a number of Canadian capital markets teams. His experience includes trading equity derivatives and marketing derivative-related risk management solutions to a broad range of clients.

Mario earned a BA in applied mathematics from York University and is a CFA® charterholder.