Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

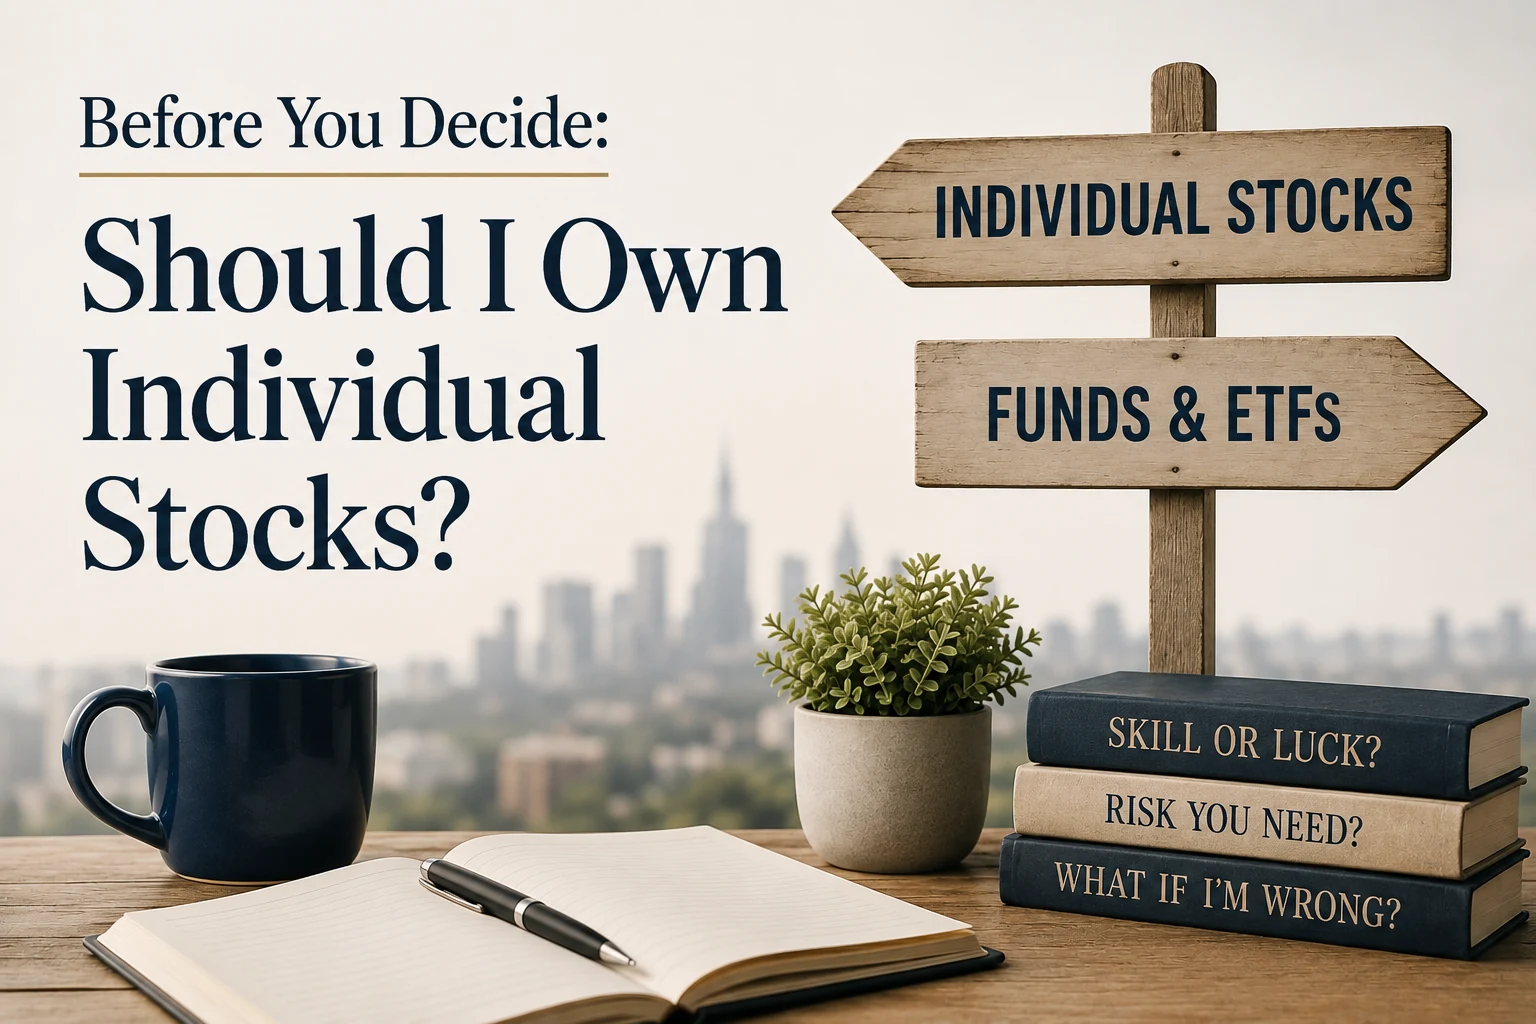
Before you Decide: Should I own Individual Stocks?

Image created with ChatGPT by Lowrie Financial


By Steve Lowrie, CFA

Special to Financial Independence Hub

The first investment I ever made was an individual stock. At that time, there were no apps or online accounts available to make this purchase. Instead, I walked into a local brokerage office, opened an account in person, sat across a desk from a stockbroker and asked him to place the trade. By the time I received the confirmation slip in the mail, roughly half of my money was gone.

What stays with me is not the loss. It is that nobody asked me anything. Nobody asked why I believed that company would do well, what would happen to my plans if I were wrong, or how much of my savings I was prepared to put behind a single idea. The order was placed, the confirmation arrived in the mail, and that was the whole of the advice. I am not certain I would have welcomed those questions at the time, since I was young and overconfident, but I have thought about them for more than thirty years and I have asked many people those same questions.

The reason they still matter is that the conversation itself has never changed. It is hard to get through a dinner or a business event without someone describing a stock they bought years ago that has gone up substantially, and what we rarely hear about is all the other stocks they bought that went nowhere. That is not because anyone is being dishonest. It is simply how memory works. We keep our winners close, we enjoy talking about them, and the disappointments quietly fall out of the story.

The stock name changes. The story never does.

There are good reasons to own stocks. Over long periods they have been one of the most effective ways to grow wealth and protect purchasing power from inflation. So the more interesting question is not whether to own stocks, but how to own them. Should you try to identify a handful of winning companies, or own a broadly diversified pool of them through mutual funds or ETFs? After more than three decades of watching Canadian families succeed and fail at this, my answer is direct: for almost every investor, there is no financial planning reason to own individual stocks. I am not saying you should never own an individual stock. I am saying the decision deserves a good reason. In my experience, most investors have never been asked to supply one.

Why is Picking Winning Individual Stocks so Difficult?

The challenge is not recognizing great companies after they have succeeded. It is identifying them beforehand, when their future is still uncertain and their share price already reflects everything millions of other investors know and expect.

Research by Arizona State University professor Hendrik Bessembinder shows just how difficult that is. In Do Stocks Outperform Treasury Bills? published in the Journal of Financial Economics, he examined the lifetime returns of every U.S. common stock since 1926 and found that the best-performing 4 per cent of listed companies accounted for the entire net wealth creation of the U.S. market above one-month Treasury bills. Slightly more than four out of every seven individual stocks did not even match the return of a Treasury bill over their lifetimes. That deserves a second read, because it means most individual stocks are not merely disappointing. Most individual stocks did worse than holding cash. Nor is this only an American phenomenon. Bessembinder and his co-authors extended the work to more than 64,000 companies worldwide and found the same pattern outside the United States.

The point is not that the stock market is a bad place to be. Over the long run it has rewarded investors generously. The point is that the reward has been concentrated in remarkably few places, which changes what you are actually attempting when you buy a handful of companies. You are not making a modest bet with slightly unfavourable odds. You are trying to locate a very small number of names inside a very large field, in advance, with a share price that already reflects everyone else’s best guess. Bessembinder tested exactly that by simulating single-stock selection repeatedly, and the single-stock strategy underperformed the broad market in 96 per cent of those simulations.

So why does anyone keep doing it? Because nothing ever tells them to stop.

You do not have to lose money for stock picking to fail. You only have to earn less than you would have earned by owning the broad market. An investor can make money every single year, comfortably ahead of any fixed-income alternative, and still be quietly falling behind the entire time. The statements look fine. There is no line item for the return you did not earn, no alert when the gap widens, and nothing that ever prompts a review. It is the most expensive kind of loss precisely because it never announces itself.

A broadly diversified portfolio removes the guessing. You will own plenty of disappointing companies along the way, but you will also own the small number of extraordinary ones, because you own all of them.

If an Individual Stock I bought went up, does that mean it was a Good Decision?

Not on its own, and this is where the first article in this series does the most work. There I made the case that a good decision can produce a bad outcome and a bad decision can produce a good one, and I offered a test for telling skill from luck: could you lose on purpose? In a game of skill you can deliberately play badly and reliably lose. In a game of chance you cannot.

Apply that test to stock picking. If you set out tomorrow to deliberately choose the worst-performing stocks in the market, could you reliably do it? Almost nobody can, and that tells you a great deal about how much skill is actually available in the activity. The answer is the same whether your last pick went up or down. So if you put a significant portion of your portfolio into one company and watched it appreciate, you may well have seen something other investors missed, or you may equally have taken a risk you did not need to take and been lucky enough to have it work out. The return by itself cannot tell you which one happened.

This matters because success changes behaviour. A winning stock reinforces our belief that we have some ability to spot winners, and once we believe that, there is no reason to change what appears to be working. I have watched that sequence more times than I can count, and it almost always runs in the same direction. The winner is rarely the last decision. It is the decision that funds the next, bigger one.

Am I taking a Risk I do not need to take?

Concentrating wealth in a few companies introduces company-specific risk, which we call uncompensated risk in investment jargon. In plain English, it is a risk that can largely be diversified away, so there is no reliable reason to expect a higher return simply for bearing it.

Concentrated portfolios can certainly outperform diversified ones, sometimes by a great deal, and that has never been in dispute. The question I would ask is a different one: do you need to take that chance to get where you are going? If a diversified portfolio already gives you a reasonable probability of accomplishing your goals, then any additional risk that could jeopardize them should clear a very high bar. In my experience, very few of them do.

Is a Canadian Portfolio as Diversified as it looks?

There is a second concentration problem that most Canadian investors never notice, and it sits underneath the first one. The Canadian market is not a balanced market. It is dominated by financial services, meaning the large banks and insurers, and by resources. Rocks and trees, as it is often described. Entire sectors that make up a large share of global markets, including technology, health care and consumer businesses, are only lightly represented here. So a portfolio invested entirely in a Canadian index is already a concentrated bet, even though it holds hundreds of companies and carries the word diversified on the label. Continue Reading…
Gold or Silver? How to prepare for what comes next

By Andrew Sleigh, Sprott Money

Special to Financial Independence Hub

When people ask me whether they should start with gold or silver, my answer depends largely on where they are financially. If you’re dealing with tens or hundreds of millions of dollars, you’re generally going to come in heavily with gold, although I still think you need silver.

For the average Canadian or American with less than one or two million dollars in assets, I would establish a position in silver coins first and then supplement that with gold. There’s no perfect percentage. You can fine-tune your gold and silver allocation as you become more educated and understand what each metal is supposed to accomplish. The important thing is building the position before everybody suddenly decides they want physical precious metals at the same time.
⠀⠀
Why I would Start with Silver Coins

People ask why I recommend silver coins instead of 100-ounce silver bars, especially when bars can have lower premiums. My answer is transactability. If all you own are large bars, how are you going to handle smaller transactions if silver ever needs to function as money? I made this mistake myself. When I started buying physical silver, I bought seven 100-ounce bars. I knew I wanted physical metal, but I didn’t yet understand which products made the most sense. After listening to people who had been stacking for decades, I exchanged those bars for coins.

My basic approach for somebody starting today would be:

  • Establish a position in recognizable silver coins first.
  • Add physical gold as the overall position becomes larger.
  • Move into 10-ounce or 100-ounce silver bars after you’ve accumulated enough coins.
  • Don’t concentrate everything into denominations that could be difficult to transact with. The objective isn’t simply getting the most ounces for the lowest premium. It’s owning precious metals in forms that could actually be useful when you need them.

Not every Ounce of Silver is Equal in the Real World

I used to believe an ounce was an ounce and bought whichever silver product was cheapest. Then I realized it’s not only about what I understand about silver. It’s about what the person on the other side of the transaction understands. I’ve encountered people who were only comfortable with Canadian Silver Maple Leafs because they recognized and trusted them. An experienced precious metals owner may happily accept a generic one-ounce round, while somebody less familiar with silver may want a Maple or, in the United States, a Silver Eagle.

That’s why I want a mixture that gives me options:

• Recognizable sovereign silver coins for people who want something familiar.
• Generic rounds for people who understand silver and simply care about weight and purity.
• Larger bars only after I’ve established enough smaller denominations. If precious metals ever become more commonly used for barter, recognizability could become almost as important as the silver itself.
⠀⠀
Why I’m concerned about the Financial System

I see substantial risk in the conventional financial system, particularly in currencies and long-duration bonds. As interest rates rise, older bonds paying much lower yields become less attractive and can lose significant market value if they need to be sold. At the same time, governments across the West continue running enormous fiscal deficits. Canada has this problem, the United States has it, and Europe has it. To me, we’re watching currencies compete in a race to the bottom.

When gold and silver rise in dollar terms, I don’t necessarily look at that as the metals suddenly becoming more valuable. I also look at what is happening to the currency they’re measured in. You can see declining purchasing power every time you go grocery shopping. If governments continue expanding deficits and pursuing inflationary policies, I believe protecting purchasing power becomes increasingly important. That’s a major reason I want physical gold and silver rather than relying entirely on paper assets and currency.
⠀⠀
Why Silver Demand could become Enormous

Silver is particularly interesting because it has both monetary and industrial demand. There are already numerous industries competing for physical silver, including

• Electrification and renewable energy.
• Electronics and advanced technology.
• Automation and robotics.
• Global manufacturing.
• Defense and military applications.

Then you add investors who want physical metal because they’re increasingly concerned about the financial system. It doesn’t take the entire population buying silver to create shortages. If even a relatively small additional percentage of people suddenly wants physical bullion, retail inventories can tighten very quickly. We’ve already experienced periods when dealers struggled to source products such as Silver Maples and 100-ounce bars. The public tends to assume they’ll always be able to buy physical metal whenever they decide they need it. I don’t make that assumption. I’d rather accumulate gradually while it’s readily available.
⠀⠀
Physical Metal isn’t a Short-term Trade for me

If your objective is trading gold and silver price movements, physical bullion probably isn’t the most efficient vehicle. Premiums and spreads can eat into short-term trades. That’s not why I own physical metal. For me, physical gold and silver are first and foremost about wealth preservation.

I think people need to separate two completely different objectives:

• Trading precious metals: Trying to profit from short-term movements in gold and silver prices.
• Owning physical precious metals: Protecting purchasing power and keeping tangible wealth under your control.
If silver substantially outperforms and you sell everything to lock your gains back into dollars, you’ve put yourself back into the currency you were trying to protect yourself from. Physical metal gives me wealth already in my possession or under my control. I don’t have to sell a financial product, receive currency, and then hope I can convert that currency into something tangible during a crisis.
⠀⠀
Gold and Silver still have Monetary Value

I’ve talked to people who have already used precious metals for barter in private transactions. I once asked a gentleman shining my shoes at the Toronto airport whether he would accept silver as payment. He immediately said yes. One silver coin represented too much value for the shoe shine, but the point was that he recognized the value and was willing to accept it.

You’re probably not walking into a major grocery chain today and paying for groceries with Silver Maples. But that doesn’t mean precious metals have lost their monetary characteristics. If confidence in conventional currencies or payment systems deteriorates significantly, I think recognizable gold and silver could play a much larger role in private transactions. That’s another reason I want smaller-denomination silver rather than having everything concentrated in large bars.
⠀⠀
How I would prepare with Gold and Silver today

Physical precious metals aren’t completely risk-free. Prices fluctuate, premiums matter, and bullion needs to be stored securely. That’s why I believe in nibbling away rather than trying to perfectly time one enormous purchase.
If I were building a position today, my priorities would be:

• Build a foundation of recognizable physical silver coins.
• Gradually add gold as the amount of wealth being protected increases.
• Add larger silver bars once enough smaller denominations are already owned.
• Keep some physical cash available for immediate expenses.
• Think carefully about secure storage.
• Don’t advertise what you own or where you keep it.

I’m not trying to perfectly trade every move in gold and silver. I’m trying to preserve purchasing power and maintain tangible wealth under my control. Financial problems can develop inch by inch and then seemingly happen all at once. I’d rather prepare incrementally while gold and silver are available than wait until everybody else reaches the same conclusion at the same time.

Andrew Sleigh is a Sales Representative at Sprott Money with over 32 years of financial industry experience. After beginning his career as an insurance broker in 1991, he became an independent financial broker, providing financial planning, investment, insurance, and benefit solutions. In 2017, Andrew shifted his focus to bullion and precious metals, helping individuals and businesses understand how hard assets can play a role in wealth preservation.

Canadian Kids picking up on their Parents’ Money Stress, new Vanguard Survey finds


Even when parents try to shield their children from financial worries, a new study suggests kids are hearing more than parents realize.

As the cost of living continues to squeeze Canadian households, a new survey from Vanguard Canada suggests the strain isn’t confined to parents’ bank accounts; it’s also shaping how their children think and feel about money too.

The survey of just over 1,000 Canadian parents of children under 18 found that households that talk openly about money raise more financially literate kids, while households that avoid the subject may be doing more harm than good.

The Instinct to Protect backfires

Many parents try to keep financial stress away from their kids. Among parents who describe themselves as financially stressed, more than two thirds said they feel pressure to hide their worries from their children, and roughly a third said they avoid discussing money at home altogether.

But the survey suggests that instinct doesn’t work the way parents hope. Seven in ten financially stressed parents said their children overhear money conversations anyway. In fact, those children were found to be nearly five times more likely to feel anxious about money than their peers.

Sal D’Angelo, Head of Vanguard Investments Canada, said children pick up on far more than parents assume, even when adults try to keep financial matters private. He framed early financial education as key to helping the next generation build healthy money habits.

 A Literacy Gap that starts early and closes late

The survey also points to a timing problem. Households where money is discussed regularly produce children with markedly stronger grasp of core concepts like banking, debit and credit, which is nearly three times higher comprehension according to the findings.

Yet the majority of parents said substantive money conversations don’t begin until their child is between 15 and 18 years old, well after attitudes toward money have already started to form. Continue Reading…

How to tell what a Stock is actually Worth: A Beginner’s Value Checklist

Run this checklist automatically on any stock at travisvaluation.ca

By Curtis Travis

Special to the Financial Independence Hub

Nearly a century ago, Benjamin Graham — the man who taught Warren Buffett — put the whole game in one sentence: “Price is what you pay; value is what you get.”

The trouble is that your brokerage app shows you the price in giant letters and says nothing at all about the value. So, most of us end up buying the number that’s flashing, not the business behind it.

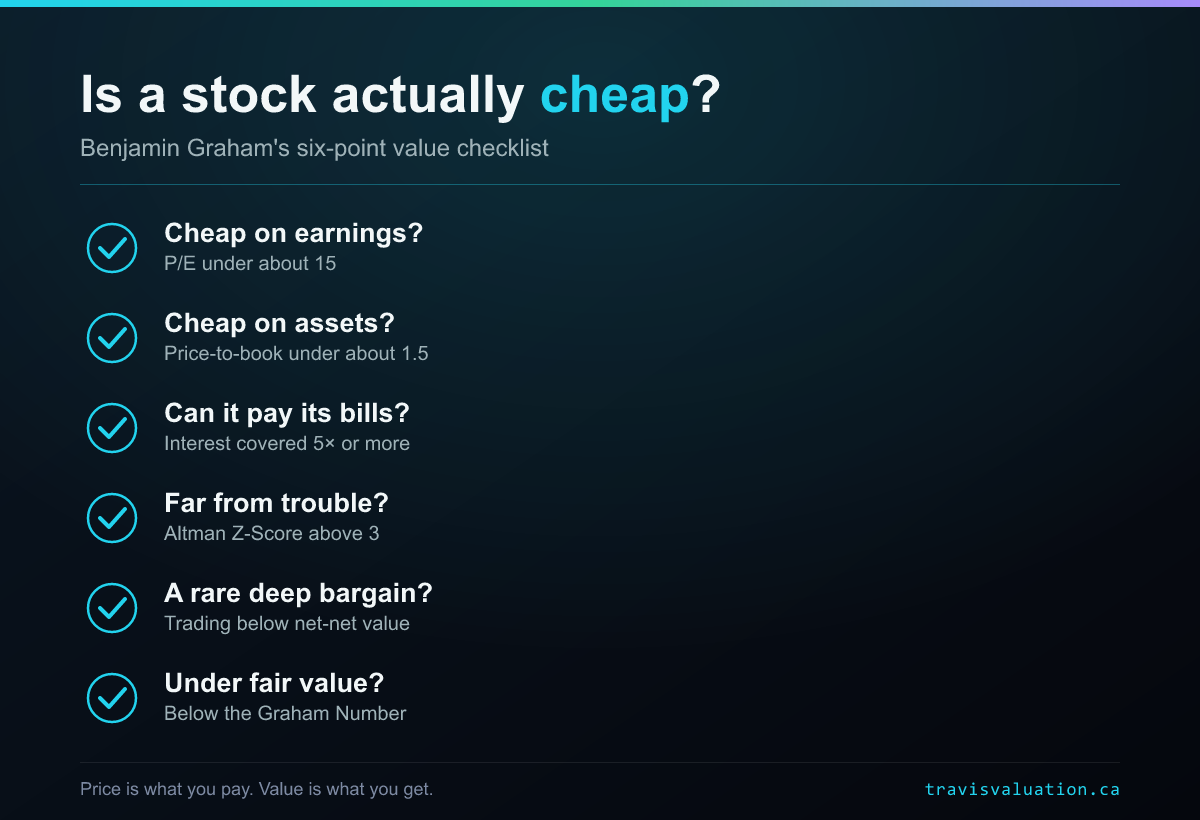
The good news is that estimating what a business is worth doesn’t require a finance degree, a Bloomberg terminal, or a spreadsheet the size of a bedsheet. Graham built his reputation on a handful of simple, repeatable checks that any patient investor can run. What follows is a beginner’s version of that checklist: six questions to ask before you buy. To keep the math clean I’ll use one example company with rounded figures: a fictional-but-typical Canadian retailer trading at $60 a share. (Real numbers move daily, so when you do this for keeps, pull the current figures first.)

Price is what you pay; value is what you’re hunting for

Before the checks, one mindset shift. A $500 stock isn’t “expensive,” and a $5 stock isn’t “cheap.” Cheap and expensive only mean something relative to what you get: the earnings, the assets, and the safety behind the share. Every check below is really the same question asked five different ways: am I paying less than this business is worth?

Check 1: Is it cheap relative to its earnings? (the P/E)

The price-to-earnings ratio is the first thing to look at. Take the share price and divide by earnings per share (EPS). Our retailer earns $5 a share, so at $60 its P/E is 12.

Graham liked to see a P/E under 15. A P/E of 12 means you’re paying $12 for every $1 of annual profit: or, flipped around, an “earnings yield” of about 8%. That’s a reasonable starting point. Anything north of 25–30 means the market is pricing in a lot of future growth, and you’re paying today for profits that may or may not show up.

Check 2: Is it cheap relative to what it owns? (the P/B)

Earnings can be lumpy, so Graham cross-checked price against the company’s book value:  roughly, what would be left for shareholders if the company sold its assets and paid off its debts. Divide price by book value per share. Our company’s book value is $40 a share, so its price-to-book is 1.5.

Graham considered 1.5 a sensible ceiling for a defensive investor. Below 1 means you’re buying the assets for less than their stated worth: rare, and worth a closer look. Well above 3 means little of what you’re paying is backed by tangible assets; you’re buying expectations.

Check 3: Can it actually pay its bills? (interest coverage)

A cheap stock that can’t service its debt isn’t a bargain:  it’s a trap. Interest coverage tells you how comfortably a company covers its loan payments: take operating earnings (EBIT) and divide by annual interest expense. Our retailer covers its interest 8 times over.

As a rule of thumb, above 5x is comfortable, and below 2x is a flashing yellow light: a bad year could put the company in a squeeze. This one check quietly eliminates a lot of “value traps” that look cheap only because they’re fragile.

Check 4: How close is it to trouble? (the Altman Z-Score)

In the 1960s, professor Edward Altman combined five financial ratios into a single distress-predictor called the Z-Score. You don’t need to compute it by hand, but you should know how to read it:

Above 3.0 — financially healthy. 1.8 to 3.0 — a grey zone; tread carefully. Below 1.8 : elevated risk of serious financial distress.

Our example lands around 3.2: solid. The Z-Score is a wonderful “sniff test” precisely because it’s hard to fool: a company can dress up one ratio, but rarely all five at once.

Check 5: The rare, deep bargain (net-net / net current asset value)

This is Graham’s most famous trick, and his most demanding. Add up only a company’s current assets — cash, receivables, inventory — then subtract all its liabilities. Divide by shares outstanding. If the stock trades below that “net current asset value,” you’re theoretically buying the ongoing business for less than nothing. Continue Reading…

A different take on the Active vs Passive Debate: Can’t we all just get along?

Image via Outcome/Shutterstock

By Noah Solomon,

Special to Financial Independence Hub

There’s something happening here
What it is ain’t exactly clear

I think it’s time we stop
Children, what’s that sound?
Everybody look what’s going down

  • For What It’s Worth, by Buffalo Springfield


Over the past two decades, the asset management industry has witnessed a massive transformation during which assets have migrated from active to passive approaches.

Notwithstanding the obvious appeal of passive investing, I believe that most of the debate between active vs. passive management misses some critical points. This month, I discuss why active vs. passive is not an either/or proposition and how the two approaches are not mutually exclusive. I will also discuss what I refer to as the three pillars of active management: the characteristics that determine whether an active manager can add value to investors’ portfolios.

The Trend is your Friend …. Until the End when it Bends

In 16 of the past 35 years, the majority of active large-cap U.S. managers outperformed their benchmark. However, there have been environments when active managers clearly dominated passive portfolios,  such as the period from 2000 to 2009, when more than 50% of active large-cap U.S. managers outperformed the index in nine out of ten years.

Passive investing is not a panacea. Capitalization-weighted indexes are price momentum-based strategies that are forced buyers of overpriced assets during bubble scenarios. As a result, they tend to do well in rising markets dominated by a few sectors or individual securities. However, this concentration can be very costly during market downturns. There is no built-in buffer or margin of safety and no risk management: just full participation, up or down.

By contrast, active managers are often constrained by individual stock and sector weighting constraints and/or valuation discipline. It is not coincidental that the majority of active managers outperformed during the post tech-bubble bear market of the early 2000s when unreasonably valued technology stocks which were heavily weighted in indexes suffered severe price declines.

Pillar #1: Dare to be Different

Many so-called active funds closely mirror their benchmark indices. These “closet indexers” offer no real value. The math is cruelly straightforward: if an active manager holds a portfolio that is not materially different from their benchmark, then their performance will approximate that of the index less fees (near-guaranteed underperformance). Moreover, such portfolios are almost perfectly correlated to their benchmarks, which renders them utterly incapable of providing diversification vs. benchmark indexes. and providing downside protection in bear markets.

Academic studies have shown that funds which differ materially from their benchmark indexes were more likely to outperform. Make no mistake: holding a portfolio that differs materially from the benchmark doesn’t guarantee outperformance, but it shows that at least you’re trying!

The issue of closet indexing has been particularly pervasive in Canada. A 2013 paper titled “The Mutual Fund Industry Worldwide: Explicit and Closet Indexing, Fees, and Performance” analyzed the prevalence of closet indexing in different countries. Out of the 20 countries which the study analyzed, Canada ranked highest in terms of the percentage of its actively managed funds that were not truly active, with over 40% identified as closet indexers. This is not surprising given the relatively small size of the Canadian markets and the associated scarcity of highly liquid stocks. Once a fund gets to a certain size, it has little choice but to hug the index unless the manager is willing to sacrifice liquidity and flexibility.

Pillar #2: Downside Protection

From a long-term investing perspective, avoiding losses is more powerful than capturing every last basis point of upside. It takes a 43% gain to recover from a 30% loss. In the past 25 years, the S&P 500 has fallen 30% or more three times. Preserving capital in such environments makes it easier to recover and better compound wealth over the long term. All outperformance is not created equal: outperformance in bear markets is of greater value than outperformance in bull markets. Active managers who can preserve capital in bear markets offer significant value for their clients.

Pillar #3: Consistency

Assessing a manager’s performance across a full market cycle is imperative for understanding the advantage of their approach and their ability to navigate challenging markets. Consistency is essential: a manager who almost always lands in the top half of their peer group offers better long-term results than one who places in the top quintile in one year and falls to the bottom the next. Importantly, managers who consistently protect on the downside are better positioned to deliver outperformance over the long term. Continue Reading…