Mini retirements challenge one of society’s most accepted ideas: work nonstop for 40 years, then finally start living at age 65.
But there’s one major flaw in that plan.
Your money may still be there at 65, but your body may not.
You probably won’t be surfing in Portugal, climbing mountains in Peru, scuba diving in the Caribbean, or salsa dancing until 2:00 a.m. in Iceland with the same energy and physical capacity you had in your 30s or 40s.
Life experiences have an expiration date.
That’s why more people are embracing the idea of mini retirements: taking intentional breaks throughout life to travel, recharge, learn, and experience the world while they are still physically capable of fully enjoying it.
What are Mini Retirements?
Mini retirements are extended breaks from work taken throughout your career instead of postponing all freedom until old age.
They can last:
Three months
Six months
One year
Even several years
Unlike traditional retirement, mini retirements are not about stopping work forever.
They are about redistributing leisure and adventure across your lifetime.
Instead of saving all your freedom for the end, you enjoy pieces of it along the way.
Why Mini Retirements make sense
Your Health Is Temporary
Money compounds over time.
But physical ability declines over time.
There are experiences that simply feel different when you are young enough to fully enjoy them.
Walking through the steep hills of Lisbon at age 35 is not the same experience at age 75.
Sleeping in hostels, hiking volcanoes, learning to scuba dive, backpacking through Southeast Asia, or dancing all night requires energy, mobility, and stamina.
Those things are not guaranteed forever.
The Compounding of Life
Financial advisors often talk about the compounding of money.
But there is another kind of compounding that matters just as much: the compounding of experiences.
In his book Die with Zero, Bill Perkins introduces the idea of “memory dividends.”
When you have an incredible experience while you are young, you continue receiving emotional returns from that memory for decades.
A six-month adventure at age 30 may give you:
Stories you tell forever
Friendships that last decades
Confidence and personal growth
Memories that enrich your entire life
That experience continues paying dividends emotionally long after it ends.
An incredible trip at age 65 may still be meaningful, but it produces fewer years of memory dividends.
A Career Break is not Career Suicide
For decades, workers feared gaps in their résumés.
Today, that mindset is changing.
Modern work is increasingly digital and sedentary. Millions of people now earn income from laptops, consulting, remote work, freelancing, or flexible schedules.
Many people in their 60s and 70s can continue working comfortably from home long after physically demanding jobs would have forced retirement in previous generations.
That changes the equation completely.
A mini retirement in your 30s or 40s is no longer necessarily a setback.
It can be:
A strategic reset
A mental health investment
A creative recharge
A period for reinvention
A chance to reconnect with life
Ironically, many people return from mini retirements more energized, focused, and productive than before.
Is it Okay to use Retirement Savings?
For many people, the answer is yes: within reason.
Of course, withdrawing money early means sacrificing some financial compounding.
But life is not only about maximizing spreadsheets.
Millennials, those born roughly between 1980 and the year 2000, face a different future than Baby Boomers did at their same age. In terms of Wealth Building and saving for Retirement their challenges are wage stagnation, unemployment, underemployment and a seeming sense of entitlement. Because they came of age during the Great Recession, their faith in brokerage firms, Wall Street and global banks has been bruised.
Being optimists, we believe the financial future of this generation can still be bright, but with loads of student debt and lack of investment understanding they need to get started learning about finances and money management now.
Time is on your side and is your greatest asset
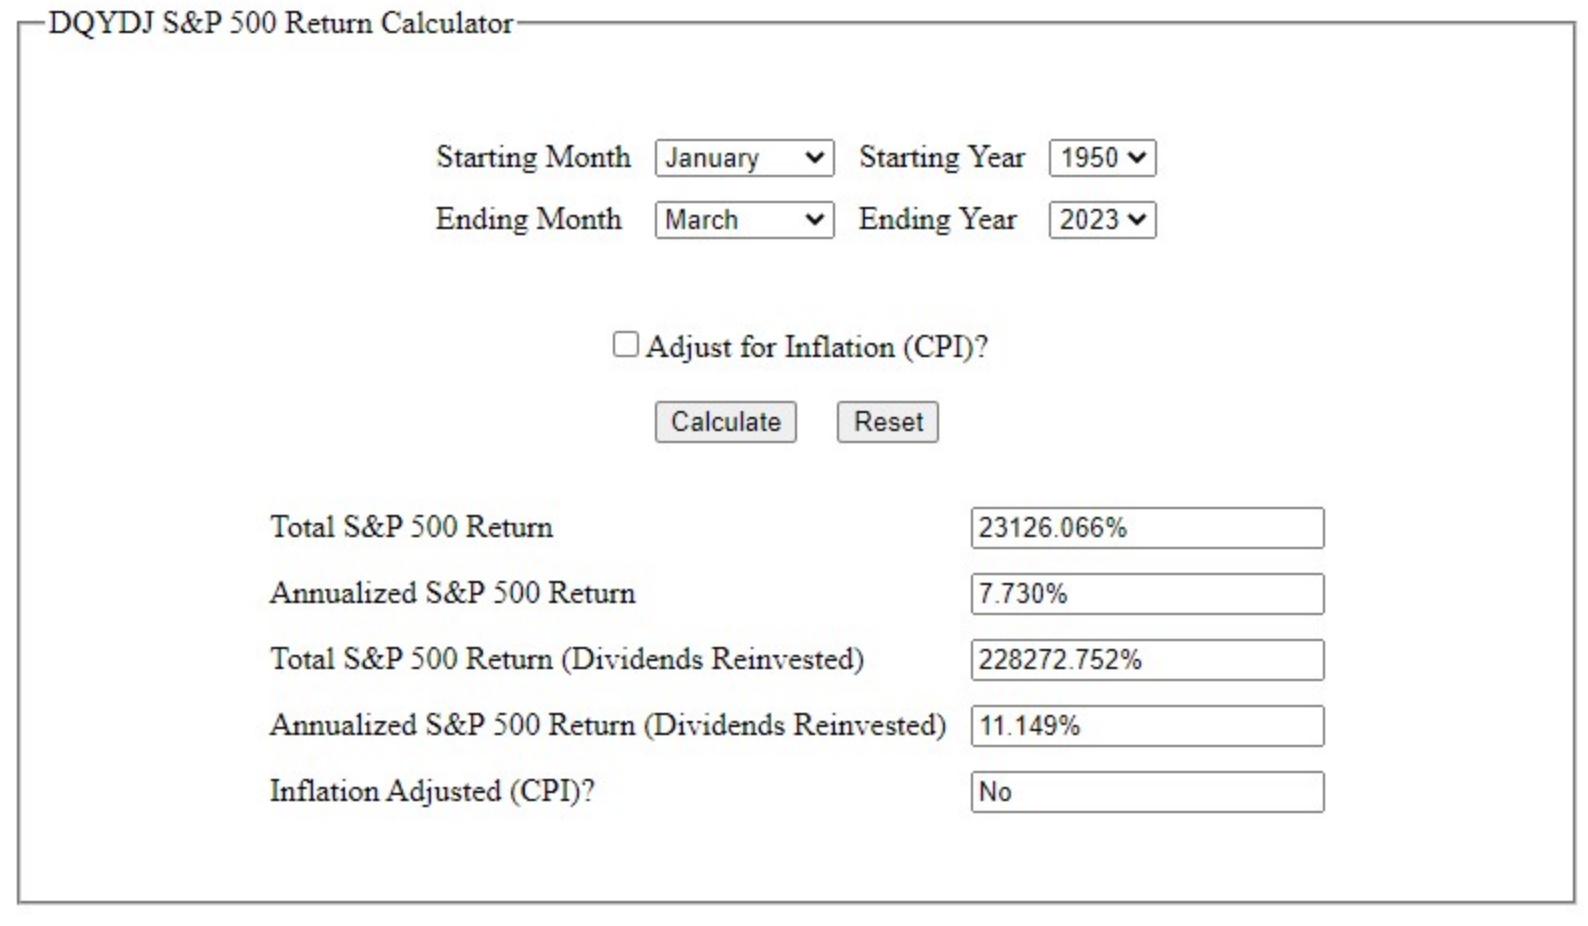
One thing Millennials have today that Boomers don’t is great stretches of time before Retirement. It is their greatest resource and this fact needs to be made clear to them. Time cannot be replaced, and if you are a Millennial, then knowing about the power of compounding will change your financial life. $10,000 – the cost of a used car – invested today in the S&P 500 Index and based on market historical returns from 1950 to March 2023 could grow to US$1,000,000 or more throughout your career, thereby building a solid foundation for your retirement needs. This return is without adding another dollar to your investment.
S&P Market Return Chart
If you do nothing else for your retirement, scrape and scrap to make this investment into SPY (S&P 500 Index ETF) or VTI (Vanguard Total Stock Market ETF) and you will be handsomely rewarded, since you have this time on your side.
Just get Started
A new investor with limited funds can utilize an online, no-frills brokerage account and — depending on which brokerage you pick — you can open an account with less than $1,000. Not every house requires initial investments of more than $2,500, and as of this writing, Fidelity is offering a no minimum for opening an account. Continue Reading…
My latest MoneySense Retired Money column looks at a handful of FIRE bloggers who should be familiar to readers of this site, Findependence Hub: notably Mark Seed of myownadvisor and Bob Lai of Tawcan.
As you can see by clicking on the column headline, How are FIRE adherents making out?, Seed recently announced he has reached his Financial Independence in his early 50s. Bob Lai, meanwhile, is still working in his 40s but blogged on how he hopes to reach Findependence before 2030.
The MoneySense column also updates the status of veteran personal finance columnist Rob Carrick, who ended full-time employment at the Globe & Mail last year, the subject of an earlier Retired Money column. And we mention a good blog by The Retirement Manifesto’s Fritz Gilbert about the 12 Good Years between age 60 and 72. As I ironically close the column with, it seems I have just used up my own 12 good years!
The real focus of the MoneySense column is however Mark Seed, just as it was Carrick last summer. In both cases, we exchanged views in Zoom or GoogleMeets over the course of an hour or so.
By now, it’s hardly necessary to remind readers that the FIRE acronym stands for Financial Independence Retire Early, as the image above illustrates.
Note that our FIRE subjects in the column span four decades: Lai his 40s, Seed his 50s, Carrick his 60s and I am in my 70s, evidently still running this website and writing for MoneySense, a former employer.
The end of Salaried Employment does not mean no more Working
The observant reader will note that none of the bloggers mentioned here have actually begun the traditional “Full-Stop Retirement.” When FIRE proponents describe Early Retirement, they usually mean leaving the comfort of full-time salaried employment and all that it entails: commuting, bosses, endless meetings, tax deducted at source, annual performance reviews and so on. Continue Reading…
That blog inspired me to reach out to multiple financial experts and business owners, with the assistance of Linked In and Featured.com, which has been supplying this site with quality content for several years.
Here’s how we posed the question:
Can you pursue Financial Independence (or Retirement or Semi-Retirement) without giving up Travel? See this blog for one opinion on this topic:
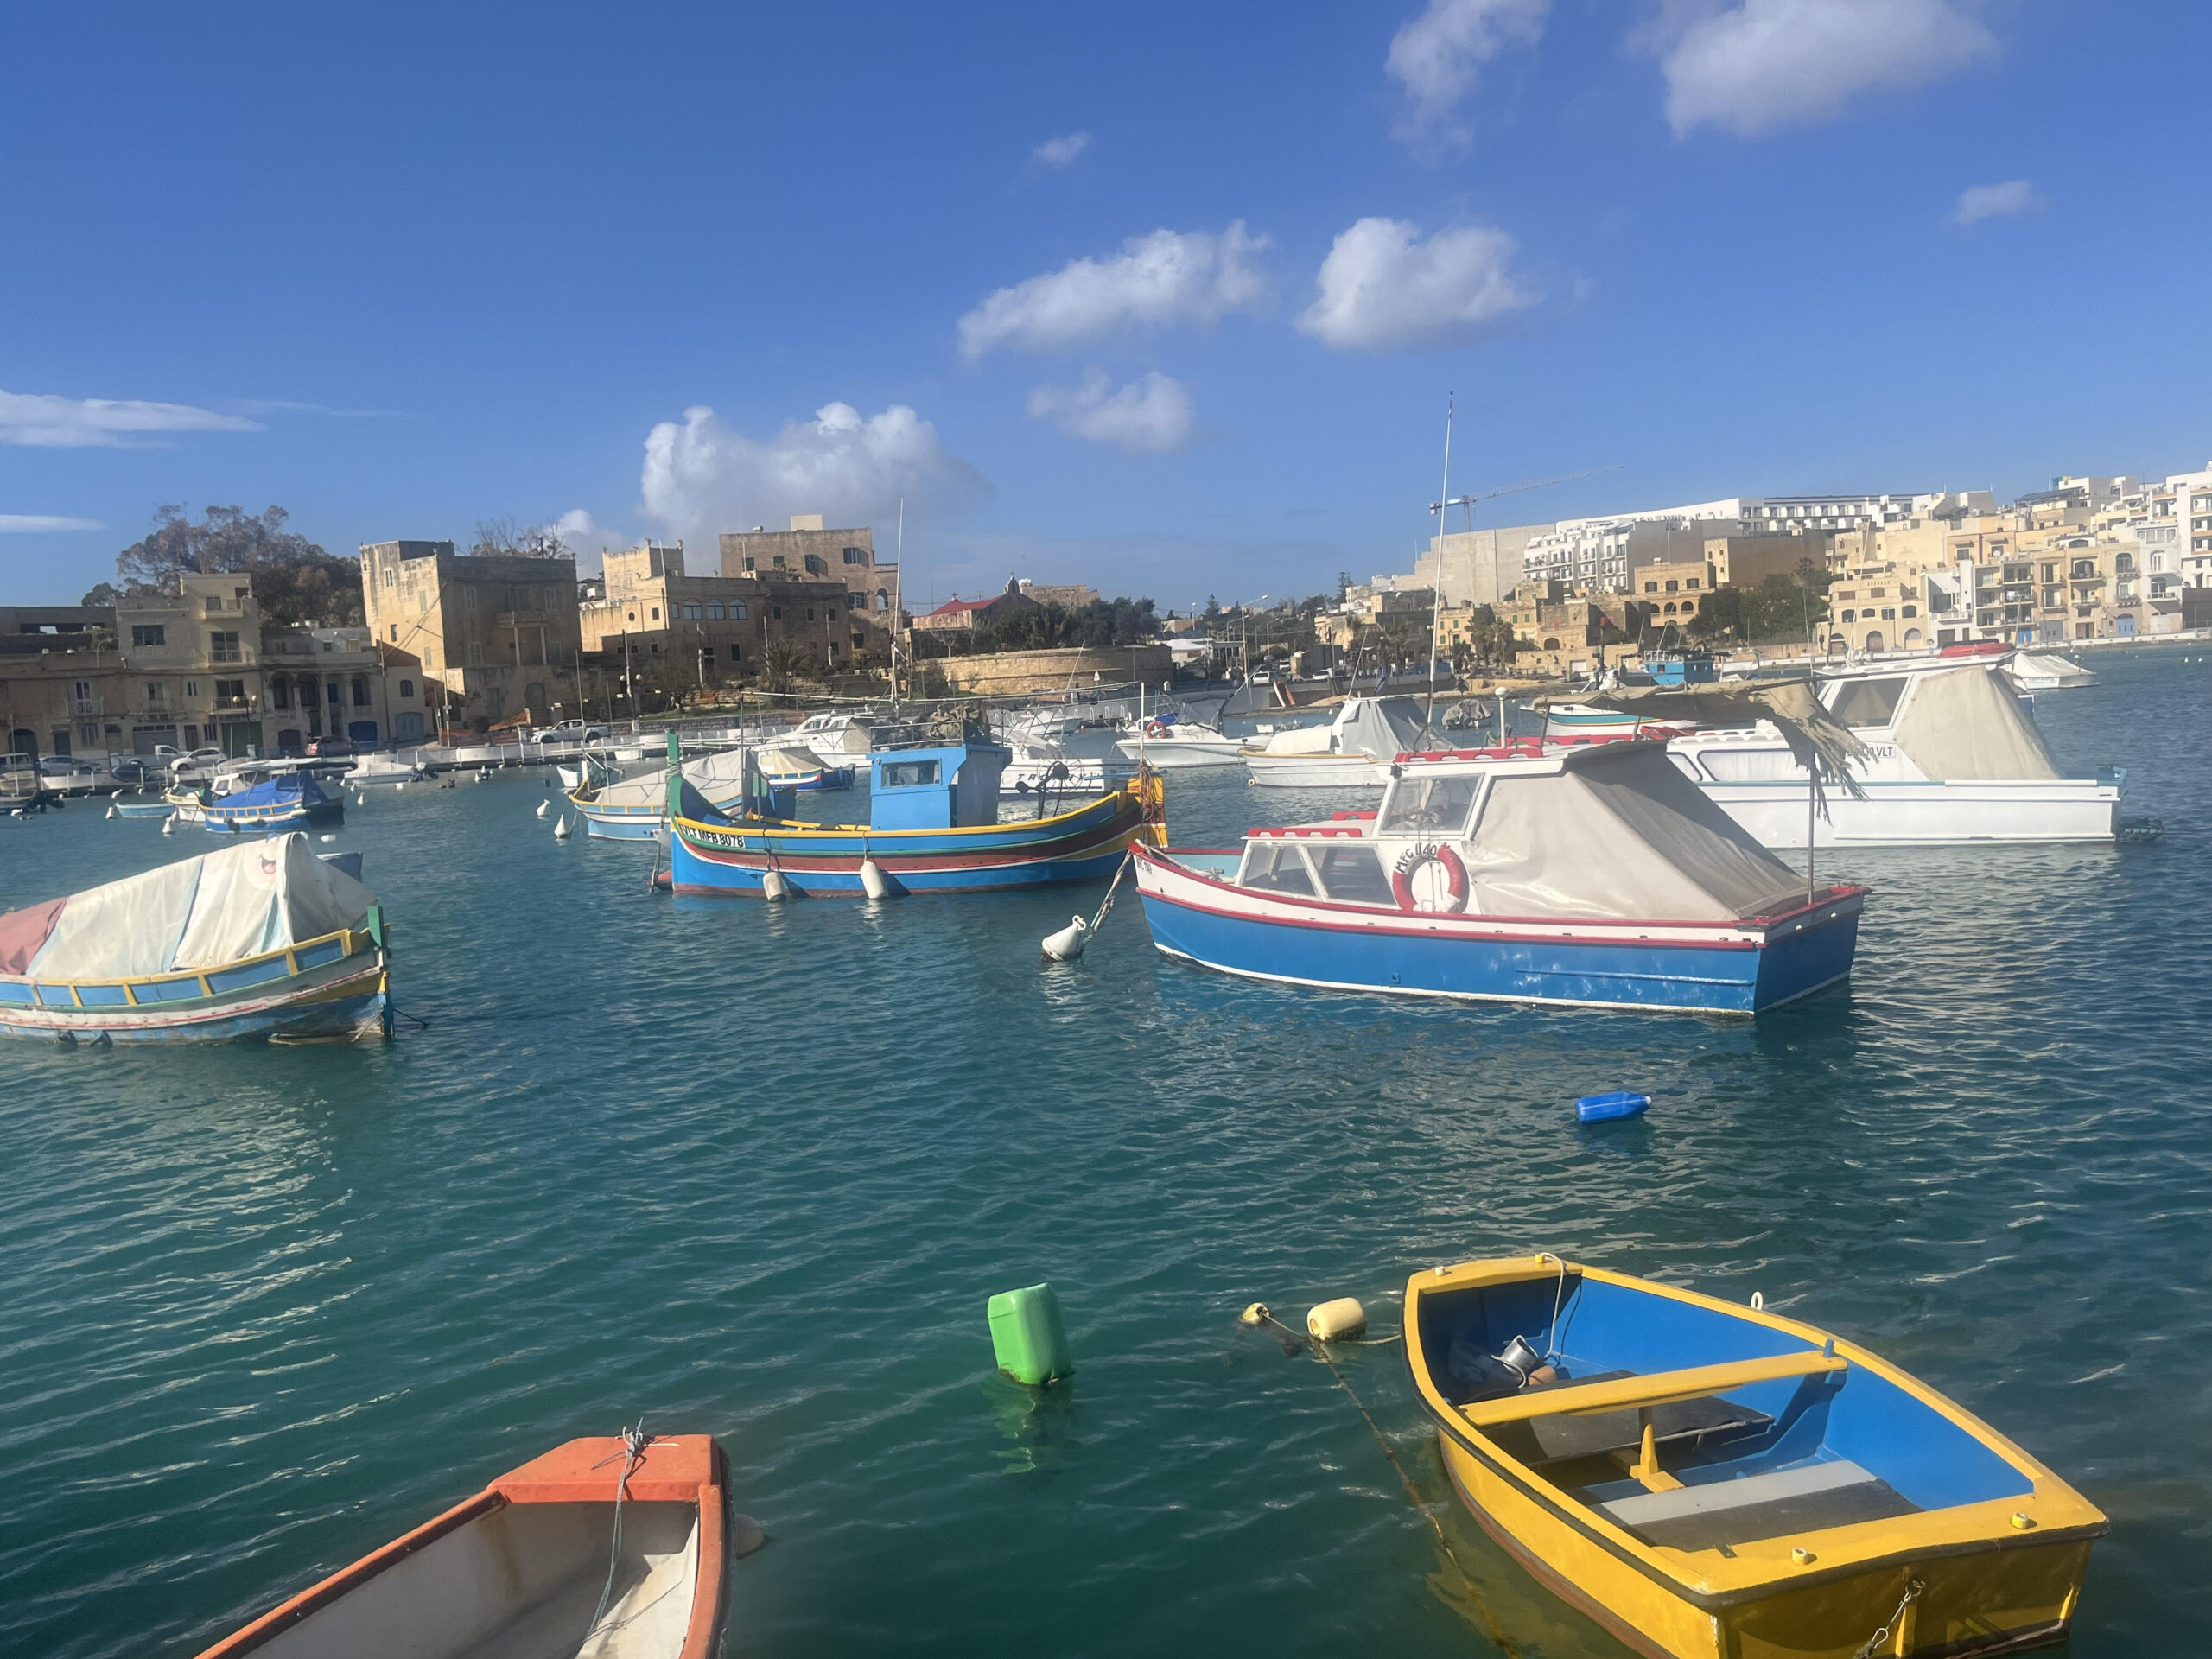
Malta: where we spent most of February this year. Photo by J. Chevreau
This particular topic attracted 84 comments by the April 20th deadline: this blog presents 25 or so that I selected. It’s long so I’ve summarized the main points with subheadings.
Note also that my latest MoneySense Retired Money column summarizes some of the main points, more succinctly as there is limited space for that column (about 1300 words, compared to the nearly 6,000 words that appear in the particular blog you are now reading).
To ease the reading burden, I’ve added subheads, some of which include:
Geoarbitrage: Live where cost of Living is lower
Renting RVs for Extended Travel Stretches
Make Travel a regular fixed expense you plan on incurring every month
Treat Travel as a budget category, not a luxury to eliminate
Embrace slow travel, house-sitting, points travel hacking and off-season destinations
Buy property in tourist spots to fund Travel
Majority of Professionals can now work remotely
The “goal isn’t to eliminate travel, but rather to make it more intentional.”
“Bleisure”: Let your career fund your transit
As President of Safe Harbors Travel Group, I’ve spent decades helping organizations use strategic logistics and “Bleisure” to explore the world without draining the bottom line. You can reach Financial Independence by letting your career fund your transit; we often help clients integrate vacation days into business trips to eliminate personal airfare and lodging costs.
A key strategy for the budget-conscious traveler is utilizing “humanitarian airfares,” a specialized airline product Safe Harbors provides that offers significant savings for anyone doing charitable, religious, or mission-based work. These fares are a powerful hack for those pursuing a purpose-driven life while keeping their personal travel expenses at a minimum.
By leveraging our elite tech partnerships for data-driven booking, you can ensure “duty of care” and response speed that prevents the costly emergencies often associated with unmanaged travel. This structured approach allows you to focus on wealth building while Safe Harbors handles the complexities of your global footprint. — Jay Ellenby, President, Safe Harbors
Build Travel into the system, not just a later Reward
Yes: you can chase FI or semi-retirement and keep travelling if you build travel into the system instead of treating it like a reward you “earn later.” I’ve run logistics/transportation businesses for years and now my wife and I host 15 furnished units in Detroit/Chicago, so I’m used to designing operations that still run when I’m not physically there.
What made it work for us is shifting travel from “big expensive trips” to “repeatable, planned mobility.” We use our Detroit-focused blog as a planning engine: when we travel, we test neighborhoods, transit (Q-Line/SMART/MoGo), and local routines the same way a guest would: then we bake that learning back into listings and guest guides so travel time also improves the business.
The practical FI move is making your income less dependent on your daily presence. Guest reviews told us people wanted clearer walkthroughs, so we added walkthrough videos to each property page and saw a 15% increase in booking conversions: less back-and-forth, fewer preventable questions, more freedom to be away while keeping standards consistent.
If you want one tactic you can copy: record a 5-8 minute “first night in the unit” walkthrough (lockbox – thermostat – Wi-Fi – parking – trash) and reuse it forever. That single asset cuts support load while you’re on the road, and it’s the difference between “I can travel” and “travel breaks my cashflow.” — Sean Swain, Company Owner, Detroit Furnished Rentals LLC
Geoarbitrage: Live where cost of Living is lower
Geoarbitrage allows you to live in an area with a lower cost of living for your family while allowing your investment portfolio to grow. The combination of using travel rewards on credit cards and traveling during less expensive times reduces your travel costs. This approach to finding money saving ways to see the world makes international exploration a viable way to maintain your lifestyle versus making it a luxury. — Zack Moorin, Founder, Zack Buys Houses
Geoarbitrage and the Second Act Advantage
In The Second Act Advantage, I show how geoarbitrage lets anyone achieve financial independence without sacrificing travel: in fact, it makes travel the strategy. By earning in strong currencies while living and exploring more affordable parts of the world, everyone can enjoy a richer, more adventurous life while actually spending less. The book teaches readers how to design a life where freedom, fulfillment, and financial efficiency all work together. — Jay Samit, Bestselling Author, The Second Act Advantage
Transitioning from Vacationing to Geo-arbitrage
The Travel-First Strategy: Designing FI Without Sacrifice
A common misconception in the FIRE (Financial Independence, Retire Early) community is that travel is a luxury to be deferred until the finish line. However, in my experience advising lifestyle-focused entrepreneurs, pursuing financial independence without giving up travel isn’t just possible it’s often a more sustainable strategy for preventing burnout.
Shifting from Consumer to Global Resident
The key is transitioning from vacationing to Geo-arbitrage. Traditional travel involves paying retail prices for short-term stays, which can cripple a savings rate. A strategic traveler focusing on FI prioritizes medium-term stays in regions where the cost of living is lower than their home base. By spending months in hubs like Portugal, Mexico, or Southeast Asia, you can often live a high-quality lifestyle for 40% less than in major Western cities. In this model, travel actually accelerates your path to financial independence by lowering your monthly burn rate.
Leveraging Credit Strategy as an Asset Class
From a PR and financial positioning standpoint, we should treat travel rewards not as points, but as a shadow asset class. A sophisticated FI seeker uses strategic credit card optimization to ensure that their transportation and lodging line items remain near zero. When flights and hotels are covered by systemic spending, travel stops being a drain on investment capital and becomes a tool for lifestyle maintenance.
The Semi-Retirement Pivot
The all-or-nothing approach to retirement is becoming obsolete. We are seeing a rise in Coast FIRE, where individuals reach a baseline of savings and then transition into remote-first or consulting roles. This allows for perpetual travel while the core nest egg continues to compound undisturbed. By integrating travel into the pursuit of FI rather than viewing it as a reward for the end of it, you create a life you don’t feel the need to escape from. This ensures that when you finally reach full independence, you already possess the global literacy to enjoy it. — James Tech, SEO Marketer, TripFrog
58% of Millennials and GenZ prioritize Travel over Material Accumulation
Financial Independence and travel are not mutually exclusive; in fact, they increasingly reinforce each other when approached strategically. A growing body of research highlights the rise of “geo-arbitrage,” where professionals leverage remote work or location flexibility to reduce living costs while continuing to explore new destinations.
According to a 2024 report by Deloitte, nearly 58% of Gen Z and millennials prioritize experiences like travel over material accumulation, reshaping traditional financial planning models. At the same time, the World Tourism Organization notes a steady increase in long-stay and work-from-anywhere travel patterns, indicating that travel is no longer viewed as a luxury pause but as an integrated lifestyle choice.
From a workforce perspective, continuous upskilling and digital proficiency — particularly in areas like project management, agile practices, and cybersecurity — enable professionals to maintain income streams while remaining location-independent.
Financial independence, therefore, is less about restriction and more about intentional design: aligning income strategies, skill development, and lifestyle priorities in a way that sustains both economic security and personal fulfillment. — Arvind Rongala, CEO, Invensis Learning
Renting RVs for Extended Travel Stretches
Absolutely yes: and I’ll tell you why from an angle most people overlook: your cost of living on the road can actually shrink dramatically while you’re building toward FI.
I run DFW RV Rentals, placing travel trailers for displaced families and insurance claims. What I see constantly is people discovering — often during the worst moments of their lives — that a well-equipped travel trailer is genuinely livable, comfortable, and cheap compared to a mortgage or apartment lease.
Here’s the FI angle nobody talks about: renting an RV for an extended travel stretch eliminates storage fees, maintenance headaches, depreciation, and insurance costs that crush RV owners. I’ve watched people romanticize ownership, buy a unit, and watch it become a financial anchor: whereas someone renting strategically keeps capital free and mobile.
If you’re pursuing FI and want travel woven in, think of RV rental as a variable living expense you control, not a lifestyle luxury. A few months on the road in a rented trailer can cost less than your fixed housing back home: and that gap is real money compounding toward independence. — Jonathan Dies, Owner, DFW RV Rentals
Maintenance-free Retirement communities
As Executive Director of The Village at Mint Spring and Stuarts Draft Retirement Community for over 16 years, I’ve guided hundreds toward maintenance-free retirement living that supports financial goals without homeownership burdens.
Yes, financial independence or semi-retirement pairs perfectly with travel when you eliminate upkeep costs like repairs, lawn care, snow removal, and property taxes: freeing budget and time for trips.
Our residents use the shuttle for local outings while traveling afar, knowing onsite care partners like Visiting Angels handle needs back home.
Fall incentives like up to $3,500 moving allowance make the shift easier, letting you lock in FI sooner and explore without stress. — David Brenneman, Owner, The Village at Mint Spring
Adopt a “Cash Rules Everything” mindset
As an advisor to business owners earning $400K+, I’ve found that financial independence is about aligning your strategy with your personal values rather than following generic industry models. I build plans for my clients that prioritize clarity and lifestyle flexibility, ensuring travel is a core component of the strategy rather than a sacrifice.
When the April 2025 market volatility caused equities to waver due to new tariffs, clients with high-liquidity strategies avoided the “dash for cash” and kept their travel plans intact. I focus on a “cash rules everything” mindset during periods of uncertainty to ensure market jitters don’t interrupt your personal milestones or global adventures.
I use the Altruist platform to give my clients a technology-driven, transparent view of their wealth from any location. This allows entrepreneurs to monitor their progress toward retirement and make confident decisions via mobile tools without being tethered to an office.
True financial guidance starts with understanding your long-term vision so your portfolio serves your life, not the other way around. By creating a practical action plan focused on stability and growth, you can pursue financial freedom while maintaining the lifestyle you have already worked to build. — Daniel Delaney, Owner, Seek & Find Financial
Make Travel a regular fixed expense you plan on incurring every month
Many people misunderstand the idea of being financially independent as a way to have nothing but austerity during their time of independence; however, the reality is that it’s just about allocating your money in a conscious manner. Too often, people will make travel an ‘additional’ expense that must be eliminated in order to achieve their savings goals: this can lead to burn out and a living arrangement that does not continue.
The problem is that travel is often treated as an item that has been paid for with ‘loose change’ after all of the other ‘necessary’ expenses have been paid each month; therefore when budgeting, travel should be included as a regular fixed expense you plan on incurring every month.
To have travel as part of your work-life balance, you will need to establish your savings plan with this in mind. Business places do this as well; you do not build a business just by lowering your cost structure, you have to build a company based on what gives you the highest return on your investment for the long-term. The same should be true for any travel related goal that you desire to achieve. One of the pitfalls that many individuals fall into when comparing their way of saving to the ways that people in the ‘lifestyle’ mode of saving demonstrate is that they fail to establish their own pace and their definition of ‘enough.’
Finding that work-life balance about not simply doing the math correctly, but making certain to build a lifestyle in which you would prefer to ‘Get up and do it!’ every single day. — Abhishek Pareek, Founder & Director, Coders.dev Continue Reading…
So you’re retired — now what? Many would say congratulations, but it doesn’t end here.
Actually, this period is the beginning of another phase of your life, and it can be as exciting as anything else you’ve done in the past. How you choose to spend your time once you no longer need the income from an ordinary job is something you seriously need to consider. Sitting around to reward yourself for work well done might be appealing at first, but once the novelty of retirement wears off, you may find yourself itching for something more gratifying. This is where the real payoffs of life come from.
When our lives are filled with work-related challenges, household duties, or health and family needs, we often have tunnel vision. Barely are there moments for conversation, and people can blur through our lives without much fanfare. We’re running on the treadmill, catching up with the TV news, and talking on the cell phone simultaneously. Hobbies take a back seat, sometimes for years. There is no down time.
The pace of retirement is less rigid. This fresh approach toward life allows us simply to sit quietly in a park or relax, leisurely having a latte in the newest coffee shop. We flip through a weekly event newspaper and notice a whole landscape of attractive options for self-expression. Discovering that there is no adequate recycling program for our town, we resolve to start one. The local school needs a drama coach, the city’s garden club wants a speaker, or the animal rescue facility is looking for a volunteer twice a week. We check our personal planner, and for the first moment in years, there’s room on our calendar.
We find this fact thrilling, and one thing leads to another.
If you are at all computer-savvy, you could help people become familiar with how to operate a computer, tablet or phone. This is a life-changing skill to those afraid of moving into the cyber world. You could coach Little League teams and discover the power and influence of service, or learn to paint on canvas and auction your work for your favorite charity.
Once you no longer need a job to pay your bills, opportunities to contribute or make extra cash will appear where you never saw them before. For instance, we’ve traded our skills as former restaurant owners to help open a Four Seasons Resort Hotel in the Caribbean Islands in exchange for dinners in their exclusive restaurant. Management then asked us to use our expertise to critique the meals and service, helping the management to prepare for soon-to-arrive tourists.
While in Mexico, as in the style of the Peace Corps, we taught the owners of a neighborhood photography shop how to make and market photos into note cards. The many travelers who visited the area eagerly bought these up, creating a side business and generating much-needed income for this local family. Continue Reading…


 Posted By
 Posted By