Tag Archives: Financial Independence

4 Retirement Planning mistakes and how to avoid them

By Patricia Campbell, Cascades Financial Solutions

(Sponsor Content)

Retirement planning used to be less complex. People would spend their career working for a company, retire after 25-30 years, receiving a watch and a pension that would be enough to live on. With people changing jobs every 2.7-4.5 years, more individuals becoming self-employed or freelancing, retirement has gotten a lot more complicated.

Unfortunately, it’s all too easy to make mistakes when planning for retirement. Here are 4 mistakes to avoid:
1.) Expecting the government to look after you

If you’re at least 60 years old and have contributed to CPP, you’re eligible to receive the Canada Pension Plan (CPP) benefit. The payments won’t start automatically, you would need to apply to the government to start receiving it. The Old Age Security (OAS) pension amount is determined by how long you have lived in Canada after the age of 18. As of July 2022, seniors aged 75 and over will see an automatic 10% increase of their Old Age Security pension.

The Canada Pension Plan (CPP) and Old Age Security (OAS) are guaranteed incomes for life but not necessarily enough to live securely in retirement. Assuming you’re 65 today and are starting payments for both, the combined total is $1,345.32 every month.

For the CPP, the maximum amount is $1,253.59 (2022), although most individuals don’t qualify to receive the full amount. The average amount for new beneficiaries (October 2021) is $702.77.
2.) Applying for government benefits too early

You could receive 8.4% more every year when delaying your CPP payment beyond age 65. That’s a 42% increase if deferred to age 70. For OAS, you receive 7.2% more for each year of deferral beyond age 65. That’s a 36% increase if deferred to age 70.

It seems like a good idea to wait, but before you decide, consider this: If you compare 3 individuals who are the same age, where Mark takes the CPP at age 60 and Tonya takes it at age 65 and Natasha at age 70. The break-even point where Mark and Tonya will both have received the same amount of money is age 74. Natasha, on the other hand, will not catch up until age 80. At this point, Natasha will begin to outpace the others considerably. But keep in mind, she would need longevity to actually use and enjoy the money. With this being said, the later you start, the higher your monthly payments will be.
3.) Spending Too Much Money Too Soon

Do you really know how much you spend each month? Unlike working, you will have a fixed income in retirement. Therefore, it’s important to plan your retirement including any vacations or large purchases. An important part of retirement income planning is knowing how much income you can achieve based on your savings. Cascades Financial Solutions is an excellent tool to use when determining your after-tax income.

Continue Reading…

Tips for moving out of your Parents’ House

Photo via Pixels/Ketut Subiyanto

It’s about that time in your life when you feel like you need a change of pace and want to move out of your parents’ house. Now, this isn’t as simple as just moving out. There are a lot of steps you need to take in order to be prepared for this new venture in life. Taking on these few tips can help with a smooth transition when moving out of your parents’ and into your new home.

Finding a New Place

Once you’ve decided to move out, you’ll next have to decide if you want to rent or buy a place of your own. Many people lean toward renting since it’s a much quicker and easier way to get a place. Although renting may be easier, buying is typically the more financially responsible route to take.

As a potential new home buyer, you’ll want to do some research on tips for buying your first home. Although there are more hoops to jump through, you’ll be investing your money into real estate and a place to live, instead of throwing your money away by renting someone else’s place.

Before starting your home hunt, ask yourself “how much house can I afford?” Establishing this ahead of time will allow you to know exactly how much you have available to go toward a payment for your new home. Consider working with a real estate agent to help with your home search. They will know the ups and downs of the market and help you find the home that’s right for you.

Decluttering and Reorganization

Many people could agree that moving out of your parents’ house is when the most decluttering needs to happen. You have clothes from all different points in your life, trinkets, and memory boxes galore. Prioritize a day or two to declutter and get rid of the things you no longer need. Then once you start packing you’ll need to move a lot less.

Decluttering prior to your move will also ease the reorganization process in your new place. Researching organization tips can help you find the best ways to do this. Buying organizational cubes, stackable containers, and any storage-type product can help keep all your items in the right place and avoid new clutter.

Developing Financial Independence

Moving out on your own means being financially independent. You’re not relying on your parents to buy the groceries or pay the utility bill. Most expenses are now on you to deal with, and you’ll want to know how you can find your financial independence. Continue Reading…

Canadian Financial Summit 2022 (Virtual)

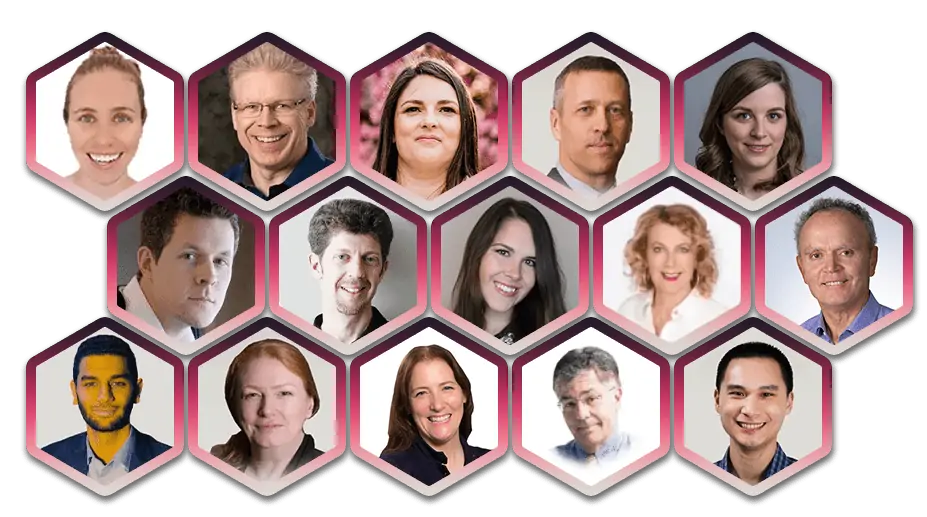
This week a veritable who’s who of Canadian financial personalities and personal finance bloggers will be featured at the 2022 (and virtual) edition of the Canadian Financial Summit, starting this Wednesday. Hub readers will recognize several guest bloggers, including (pictured above) Robb Engen of Boomer & Echo; Bob Lai of Tawcan; Kyle Prevost of Million Dollar Journey and MoneySense; myself; as well as well-known media commentators like Robb Carrick of the Globe & Mail, Peter Hodgson of the Financial Post, Fred Vettese of the G&M, financial planner Ed Rempel and many more. There will also be MoneySense colleagues Dale Roberts (of Cutthecrapinvesting) and MoneySense executive editor Lisa Hannam

The online summit runs from Wed., Oct. 12 to Saturday, Oct. 15th, 2022.

To register, click on the home page here.

Here are just some of the topics that will be covered:

  • How to plan your own retirement at any age
  • How to save money on taxes by optimizing your RRSP to RRIF transition
  • What cryptocurrencies like Bitcoin actually are – and if you should be investing in them
  • How to maximize your Canadian Child Benefit (CCB)
  • How to efficiently transition your investing nest egg to a steady stream of retirement income
  • What Canadian real estate investments looks like in 2022
  • How to deal with inflation on your bills and in your investment portfolio
  • How to avoid crippling fees and terrible advice
  • When to take your OAS and CPP
  • How to buy your own pension – income for life!
  • Why Canadian dividend stocks might be the right fit for you
  • How to use your housing equity to maximize your retirement lifestyle

Here’s what MillionDollarJourney had to say about the conference:

I’m proud to say that MDJ’s own Kyle Prevost is co-hosting the event alongside MDJ writers Kornel Szrejber and Dale Roberts – so I can speak firsthand to the quality of the product!

One thing I always appreciate about this Summit each fall is that it is produced by Canadians – for Canadians.  Too much of the money-related content we see is American-based in nature – but you won’t have to translate any talk about 401Ks or American private health insurance at this event!

Together, the roster of All Star Speakers have authored more than 100 personal finance books, hosted 1,000+ podcast episodes, written 20,000+ blog posts and newspaper columns, and have been featured in thousands of media articles and interviews from every news and financial publication in Canada.  

Needless to say – you will not find this elite group in one place anywhere else!

And it’s free!

Here’s a sampling of the event’s FAQ:

Is the Canadian Financial Summit really free?

Yes. The videos are completely free to view for 48 hours. After that you need the any-time, anywhere All Access Pass.

What’s the catch?

There. Is. No. Catch.  We believe you’ll think the information presented by our 35+ Canadian experts is so solid, so actionable, so lacking in fluff and sales jargon – that we think you’ll pay for it after already seeing it for free.

How do I watch The Summit?
Simply click here to claim your free ticket. You should immediately get an email confirming your registration – just follow the directions in that email and you will get a link sent to you 24 hours before The Summit goes live. You can view The Summit on any phone, tablet, or computer.
I signed up for the 2017,2018, 2019, and 2020 All Access passes, but am not sure how to access those membership pages.

Click here, and simply fill in your info.  You will be be taken to a page that allows you access the 2017, 2018, 2019, and 2020 content. If you have forgot your Canadian Financial Summit password, simply click here to re-set it.

A sampling of the sessions

Rob Carrick

Where is Housing Headed?

In a drastic change from past years, we’re seeing some major pull backs in the Canadian housing market. Join Rob and I as we break down how this is affecting Canadians’ net worth, who is getting hit the hardest, and where we go from here. We also discuss if renting is still an option that we’re recommending and what we think could happen in regards to the long-term trends of immigration and housing stock within Canada now that the pandemic is in the rearview mirror.

Ellen Roseman

Addressing Canadians’ Inflating Sense of Worry

Longtime Canadian consumer advocate Ellen Roseman is back and wants to help Canadians weather the recent storm of inflation and rising costs of living.  Her personal experience with Canada’s last bout of quickly rising prices have given her some hard-won wisdom in practical ways to deal with modern inflation issues.  We talk about what to pay attention to, watch out for, and some top tips in this high-price environment.  We wrap by speculating on what all of this will mean for Canadians’ investment portfolios. Continue Reading…

Beware the Retirement Risk Zone

I often recommend deferring CPP until age 70 to secure more lifetime income in retirement. It’s also possible to defer OAS to age 70 for a smaller, but still meaningful, increase in guaranteed income.

While the goal is to design a more secure retirement, there can be a psychological hurdle for retirees to overcome. That hurdle has to do with withdrawing (often significant) dollars from existing savings to fill the income gap while you wait for your government benefits to kick in.

Indeed, the idea is still to meet your desired spending needs in retirement – a key objective, especially to new retirees.

This leads to what I call the retirement risk zone: The period of time between retirement and the uptake of delayed government benefits. Sometimes there’s even a delay between retirement and the uptake of a defined benefit pension.

Retirement Risk Zone

The challenge for retirees is that even though a retirement plan that has them drawing heavily from existing RRSPs, non-registered savings, and potentially even their TFSAs, works out nicely on paper, it can be extremely difficult to start spending down their assets.

That makes sense, because one of the biggest fears that retirees face is the prospect of outliving their savings. And, even though delaying CPP and OAS helps mitigate that concern, spending down actual dollars in the bank still seems counterintuitive.

Consider an example of a recently divorced woman I’ll call Leslie, who earns a good salary of $120,000 per year and spends modestly at about $62,000 per year after taxes (including her mortgage payments). She wants to retire in nine years, at age 55.

Leslie left a 20-year career in the public sector to work for a financial services company. She chose to stay in her defined benefit pension plan, which will pay her $24,000 per year starting at age 65. The new job has a defined contribution plan to which she contributes 2.5% of her salary and her employer matches that amount.

Leslie then maxes out her personal RRSP and her TFSA. She owns her home and pays an extra $5,000 per month towards her mortgage with the goal of paying it off three years after she retires.

Because of her impressive ability to save, Leslie will be able to reach her goal of retiring at 55. But she’ll then enter the “retirement risk zone” from age 55 to 65, while she waits for her defined benefit pension to kick in, and still be in that zone from 65 to 70 while she waits to apply for her CPP and OAS benefits.

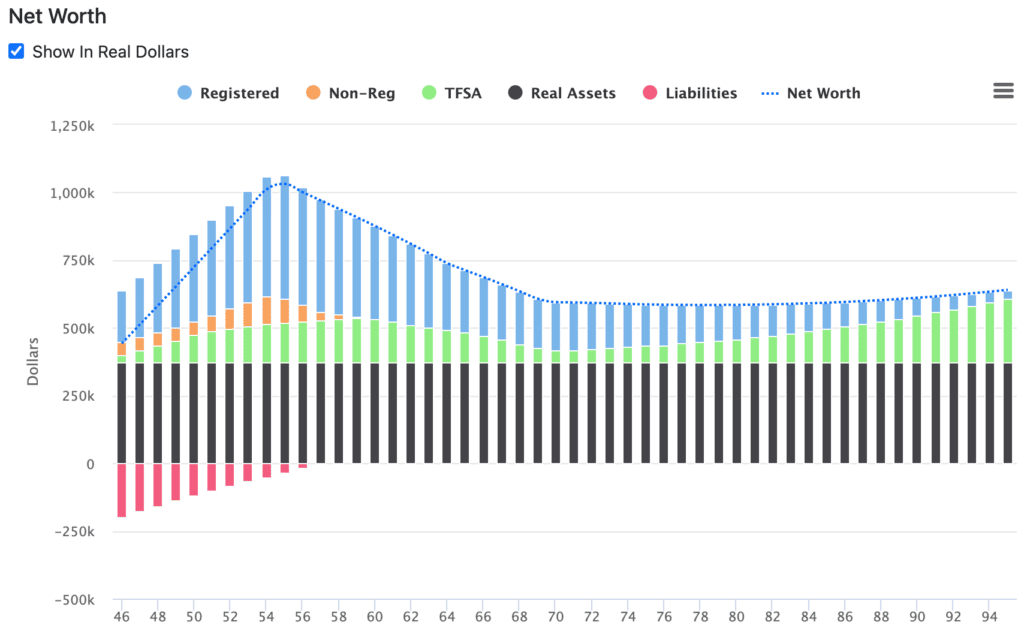
The result is a rapid reduction in her assets and net worth from age 55 to 70:

Retirement risk zone example 55-70

Leslie starts drawing immediately from her RRSP at age 56, at a rate of about 7.5% of the balance. She turns the defined contribution plan into a LIRA and then a LIF, and starts drawing the required minimum amount. Finally, she tops up her spending from the non-registered savings that she built up in her final working years.

When the non-registered savings have been exhausted at age 60, Leslie turns to her TFSA to replace that income. She’ll take that balance down from $216,000 to about $70,000 by age 70. Continue Reading…

How to avoid your own retirement crisis

By Myron Genyk

Special to the Financial Independence Hub

The Canadian working population feels anxiety about retirement. Numerous surveys have shown that Canadians lack knowledge about how to save for retirement and stress about it. And for good reason – it’s difficult for someone with no personal finance background to know where or how to start. Canadian workers recognize that retirement investing is becoming increasingly important, as 75 per cent of Canadian employees believe there’s an emerging retirement crisis.

So how can you avoid your own retirement crisis? What do you need to do to get started? Generally, the first step is to open an investment account, and to do what is commonly referred to as “self-directed investing” or “DIY investing.”  Once set up, here are five tips to ensure you are successfully investing for retirement:

1.) Start early

Compounded returns work their magic over longer periods of time, so it’s crucial to invest for retirement as early as possible.

For instance, if you invested $1,000 at age 25 and earned a return of 5.00% over 40 years, you would have $7,040 at age 65 (in today’s dollars). If you invested that same $1,000 at age 45, you would need to realize annual returns of 10.25% to have that same amount at age 65. This percentage only increases as you age. Starting early lowers your hurdle rates.

2.) Be consistent

Create a realistic savings plan. Whether it’s setting aside $20 or $200 of your paycheck, it’s important to set the amount and stick to it.

Avoid trying to time the market. So much has been written about how nobody can time markets; some people can be lucky over short periods, but nobody can do this consistently – not a fund manager, not your brother-in-law, not your neighbour.

You might also be enticed to put off saving for a couple of months, putting that money towards a vacation or something.  Deviating from your savings plan could lead to forgetting to resume with your plan, or believing that you don’t need to continue with it.

3.) Keep fees low

Most people might not think much about a 1% or 2% difference in fees.  After all, whether you tip 15% or 16% at your local breakfast diner might be the difference of a few dimes.  However, when incurred over years and decades, these fees can substantially eat into your investment portfolio. Continue Reading…