Tag Archives: Financial Independence

5 sensible steps to improve your 2018 game plan

“Your future depends on many things, but mostly on you.”
—Frank Tyger (1929–2011), cartoonist, columnist and humourist
Designing the investment plan for the long haul requires much serious thought. Unfortunately, investors shortchange themselves on two fronts. Firstly, they spend far too much time selecting investments. Secondly, and more important, they spend too little time researching and establishing their investment policies and strategies. The ones that the plans should put into effect to reach personal goals.

In my experience, few investors actually have a sensible game plan that is being followed. Too often, this results in a collection of “flavour of the day” investment selections. Designing the appropriate investment plan is essential, particularly the asset mix targets.

“Understanding the major investment risk factors brings perspective to the plan. The ability, willingness and need to take risks are your top three.”

Happily, this situation is easy to rectify. A new year is about to make its grand entrance. Let us take a breather to contemplate a few improvements.

Stewarding the finances is truly a long journey. If you were my client, I would start with this question, “What is important about investing to your family in 2018 and beyond?”

My observation is that many investors opt for preservation of capital. Others focus on portfolio growth. The rest concentrate on the retirement income stream. Lifestyle needs are also high on the pecking order.
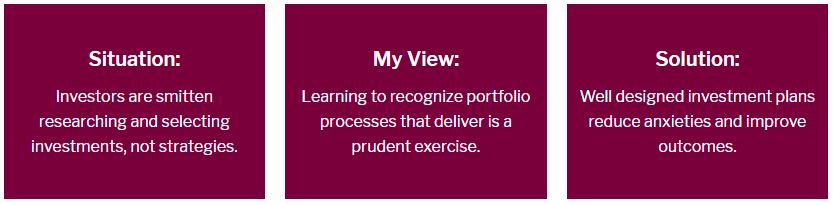
I touch on a handful of key steps in designing your game plan:

1.) Retirement prospects

Determine the family’s desired retirement income goal in today’s dollars. Calculate the size of portfolio to reach and sustain the goal. This provides portfolio direction and purpose. Estimate the personal rate of return required to achieve the retirement nest egg ballpark. Then treat that rate of return as the “investment benchmark” for the game plan.

Once the personal rate of return is identified, there is likely no need to incur higher investment risk than necessary. This is especially important to retired investors. Consider all the investment accounts owned as part of the big picture, not in isolation. Revisiting your “asset location” best practices helps fine tune the game plan.

2.) Investor profile

Analyze which type of investor profile suits and feels best. The most familiar ones are labeled as preservation, income, balanced, growth and aggressive. In my experience, investor profiles change infrequently.

The majority of investors are comfortable within 40% to 60% allocated to stocks and the remainder to cash and bond selections. For example, a balanced profile typically allocates about 50% to stocks, 40% to bonds and 10% to cash instruments.

3.) Asset mix 

Asset mix decisions have the greatest impact on portfolio outcomes than any other factor. Studies show that these decisions explain a substantial amount of variations in total portfolio returns. Continue Reading…

How to graduate debt-free from College

By Steve Barker

(Sponsored Content)

Many high school students are faced with the prospect of going into tens of thousands of dollars in debt or foregoing higher education. Today’s young people are having to look at a college education as an investment and to weigh the value of that investment against potential returns.

There are ways to stay out of debt and still earn a college degree: it just requires a little planning and patience.

Advantages of Going to College

The cost of tuition is steadily rising without the accompanying rise in income. Although there are many paths to success, a college degree does greatly increase job options, teach valuable skills, and create lifelong networks of friends and colleagues. Here are some reasons why college is still worth the cost.

  •       Increased pay: Even though incomes aren’t rising with tuition costs, college graduates still tend to make more than their non-schooled friends. College grads earn an average of 56 per cent more than high school graduates.
  •       Higher rate of employment: The job market is extremely competitive. Anything that gives you an edge should be considered. Some studies show that only 3.8 per cent of college grads are unemployed compared to 12.2 per cent of individuals with only a high school diploma.
  •       Networking opportunities: You are likely to make a lot of valuable connections while attending school. You are introduced to people with new ideas who have the potential to inspire, encourage, and challenge you. Your professors and peers may become vital connections as you enter the workforce.

Staying Out of Debt

There is more than one way to earn a diploma. Taking out student loan debt is not the only way to finance your education. Continue Reading…

Do men and women have different Savings Habits?

By Danielle Kubes

Special to the Financial Independence Hub

In an online survey about savings habits, financial comparison site Ratehub.ca reports that although Canadian men and women save almost the same amount of money, men have a greater level of confidence in their financial planning.

Inspired by 2014 Statistics Canada data that says Canadian women have lower financial literacy scores than men and were less likely to consider themselves “financially knowledgeable” (31% of women versus 43% of men), Ratehub.ca set out to discover if there truly is a gender divide. 

The company digitally surveyed a random sample of 1,087 Canadians in November, with respondents self-identifying their gender.

“Our survey revealed that while men and women differ in aspects of their financial planning, at the core, their personal finance goals and concerns are nearly identical,” the report says.

Both genders have similar financial goals

Indeed, both genders report almost the exact same financial goals. At the top of list of priorities is retirement, followed by travel and then having an emergency fund.

Both men and women prefer to save and invest in registered accounts, especially the registered retirement savings plan (RRSP) and tax-free savings account (TFSA). What they choose to invest in within these accounts — guaranteed income certificates (GICs), exchange traded funds (ETFs), stocks, or other products — is unknown.

Yet men and women diverge most in how confident they are that they’ll have enough money to retire: less than half of women, 41%, say they’re confident compared to over half of men surveyed, at 56%.

Odd, because both genders save almost the same amount of their salaries, with women saving 26% and men 29%.

The gap could potentially be explained in how able they are to grow those savings through investing. Eighty-five per cent of men invest their money, while only 76% of women do.

Of those that do invest, less women than men self-manage their investments, potentially indicating another worrisome lack of confidence in their financial knowledge.

This is supported by the original Statistics Canada data, which found women were less likely to state they “know enough about investments to choose the right ones that are suitable for their circumstances.”

Confidence doesn’t mean financial knowledge

But does confidence translate to actual financial knowledge? Apparently not. When Statistics Canada quizzed Canadians who rated themselves financially literate, one in every three women failed, while one in every four men failed. Continue Reading…

What is Personal Finance and why is it necessary?

By Brenda Cagara

Special to the Financial Independence Hub

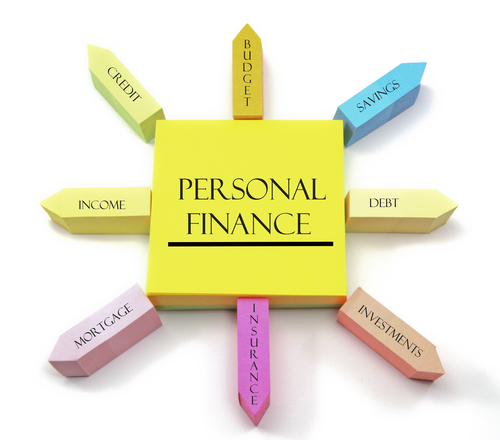
Personal finance is the art of managing finance individually or for household purposes.

Why would I call it an art? As there are several factors that need to be taken into consideration, the word may seem simple but it is not.

These factors may include purchasing of financial products example, home and life insurance, credit cards mortgages, investments and vehicles: In other words, handling budget, savings, and spending monetary resources over time, taking into account various financial risks and benefits for future life events.

Nowadays, personal finance is regarded as a specialty on its own. Historically, it was taught as a part of home economics or termed as “consumer economics,” which was included as a curriculum in various schools, colleges and university. In 1947, Herbert A. Simon, a Nobel laureate, suggested a decision maker did not always make the best financial decision because of limited educational resources and personal inclinations.

In 2009, Dan Ariely suggested the 2008 financial crisis emphasized the fact human beings do not always make rational financial decisions, and the market is not necessarily self-regulating or corrective of any imbalances in the economy.  Therefore, it is crucial to obtain some basic information about this topic to help an individual or a family to make rational financial decisions throughout his or their lifetime.

Planning Personal Finance

To understand personal finance, one should first have at least a vague idea of financial planning. Financial planning can be defined as a process that requires regular monitoring and re-evaluation of income and expenses. It includes five components: assessment, goals, planning, implementation, monitoring and re-evaluation.

  1. Assessment. Financial position can be assessed by making a balance sheet or personal statement. A balance sheet includes value of all the personal assets and liabilities. A personal statement personal income and expenses.
  2. Setting up small targets acts as an incentive for a person to work hard enough to achieve a financial position is a smart idea. These goals can be divided into short term and long term. Long-term goals may be being retired at the age of 60 with a net worth of $15,00,000, whereas an example of short-term goal may be saving up to buy a new house, a car or a new television.
  3. Once we’ve decided our aims and objectives, we need to have a plan as to how we are going to go about it to achieve it. An ideal plan should include a road map to decrease expenses and a way to enhance earning.
  4. This is the most crucial part of the five steps and in fact the most difficult of all. Once a person comes up with an ideal plan, there should strict implementation of it with discipline and perseverance.
  5. Monitoring and reassessment. With time there are changes in every individual’s life, family and priorities. In order to accommodate these changes the plan will require some alterations over the period of time, making monitoring and reassessment very important.

Personal Finance Tips

1.) A budget is a financial roadmap allows you to live within your means, while having enough left over to save for long-term goals. A simple example of budget can be as follows:

Continue Reading…

Financial planning should be a Parallel, not Serial, process

By Darren Coleman

Special to the Financial Independence Hub

In a serial circuit when one light bulb goes out, all the lights go out. Each light is wired to the next and all of them have to work for each one to work. In a parallel circuit all the lights are wired together but independently from each other, so when one light goes out, the other lights still stay on.

This concept is important and comes into play in my book ‘RECALCULATING – Find Financial Success and Never Feel Lost Again’. The book applies the analogy of driving to investing and financial planning. (See earlier Hub blog on the book).

I have spent almost a quarter of a century counseling clients about their money and assets, and often see people who believe their financial planning should look like a serial circuit. They think they must achieve one goal before moving on to the next. They have constructed an order or sequence that must be strictly followed for them to feel comfortable about achieving their plan.

This is the view Marvin and Jesse had when I met them. A successful, professional couple, they had young children and a list of goals. No. 1 on the list was that they wanted to be mortgage-free by age 45. They also wanted their kids to go to a private school, and vacations every year with the family. In addition, they wanted a comfortable retirement by their late fifties. They had great jobs, were disciplined savers, and figured they should be able to achieve all these goals. But they didn’t know how to put all the pieces together and make it happen.

I reviewed the situation to gain an understanding of their current state, and discovered that almost all their uncommitted cash flow went to pay down the mortgage. There were only token amounts being saved for their children’s education, family vacations, and retirement plans.

A couple that used serial financial planning

When I asked about this, they said paying down the mortgage as quickly as possible was the central assumption – the core pillar – of their financial planning. In short, this couple looked at all their desired destinations as if they were part of a serial circuit. Once they had paid off the mortgage, they would move on to the other plans.

I told them they could do this, but achieving that milestone of being mortgage-free by age 45 meant they could not put their children in private school, take annual holidays with the family, or make tax-advantaged contributions to their retirement plans. So, while they could be mortgage-free at an early age, they would not accomplish their other goals. And, of course, they couldn’t get the time back.

None of us can.

Shift to financial planning in parallel

I showed them that changing the picture from a serial circuit to a parallel circuit might be the answer. Continue Reading…