Tag Archives: Financial Independence

Boomer & Echo’s Review of Victory Lap Retirement (+ a giveaway)

There’s a growing body of evidence that suggests postponing retirement – even by just one year – can lead to a longer, healthier life. The reality is that we’re living longer and saving less. Something has to give. But another year or two spent pushing paper in a cubicle is probably not the holy retirement grail we’ve been searching for.

Related: Growing older in America – The Health and Retirement Study

Indeed, if you’re healthy and can afford to stop working, the idea is to find something else you’re passionate about and do that instead – whether it’s switching to a new career in an unrelated field, writing a book, starting a blog, or simply volunteering at your favourite charity. Call it your work-optional years.

Victory Lap Retirement

Authors Mike Drak and Jonathan Chevreau call it your Victory Lap Retirement. The authors argue that the idea of retirement has to change in the sense that going from 100 percent work mode to 100 percent leisure mode is boring and fraught with risk.

The fact is we might be retired, in the traditional sense, for thirty or forty years – as long, or maybe longer, than we spent during our working lives. That’s too long to spend in an armchair watching Seinfeld reruns.

How do we find purpose and meaning in this third stage of life? More importantly, for some, how do we finance it?
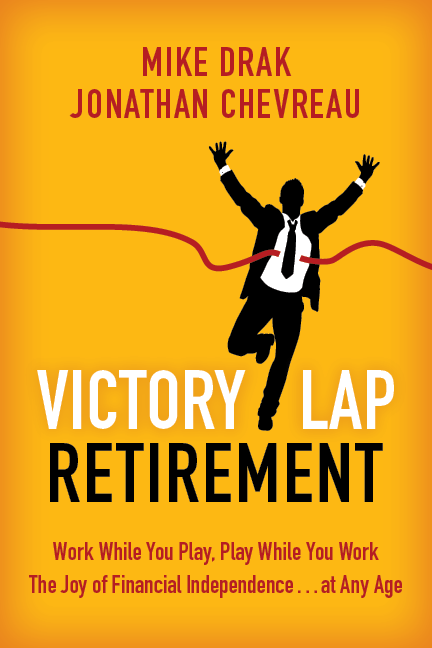
 In Victory Lap Retirement, Drak and Chevreau describe a post-employment lifestyle designed with a unique blend of work and play that allows you to live life to the fullest, on your terms, while you’re young enough to enjoy it.

Financial Independence


Continue Reading…

Simplifying Investing for Financial Independence

By Billy and Akaisha Kaderli

Special to the Financial Independence Hub

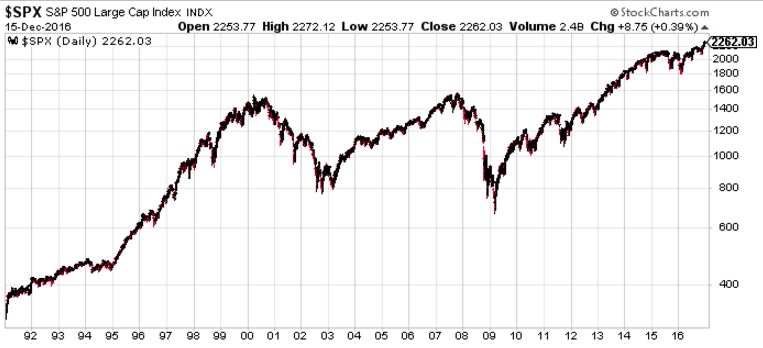
As 2016 comes to a close, we thought we would look back financially to where we started this adventure, from January of 1991. The chart below shows the ascent of the S&P 500 Index over our 26 years of retirement.

On our retirement date of January 14, 1991, the S&P 500 index closed at 312.49. It has recently closed at 2262, making roughly an 8% annual gain plus a couple per cent counting dividends. Hard to imagine, right? With all of the market ups and downs, global turmoil, governments coming and going, businesses expanding and failing, and still producing roughly a 10% annual return.

But is this really a one-off period and not the norm? Continue Reading…

How to create financial sustainability for yourself

Billy & Akaisha Kaderli, RetireEarlyLifestyle.com

By Billy and Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

These days, no matter what the topic, the talk is all about sustainability.

In regards to financial sustainability, there are three legs to the stool: income, spending and Investments.

1.) Income

Income is derived from money you make through your job using physical or mental labor or both. Passive income can be created through property rentals, bond interest, dividends and or capital gains from investments.

Increasing income can be done by learning a new skill, getting a promotion, or taking on a better or second job. Maximizing your skills and continued education either formal or on your own is a valuable asset. This could be as easy as teaching yourself about investments in your down time. There are plenty of online tools available to learn this.

Also, don’t rule out that Social Security [or in Canada, CPP and OAS] will be available once you become eligible.

2.) Spending

How much you spend and the debt you carry are two areas that are completely manageable by you. The categories of largest spending in any household are housing, transport, taxes and food/entertainment. Depending where you live, it may make more sense to rent instead of buying a home, or rent out a room in the home you already own, or rent out a subsection of your home in order to help with the mortgage. Putting off that remodel of the bathroom or kitchen, or the re-do of the back yard will also allow you extra money to put into investments.

Regarding transportation, you could walk or bicycle to work, take public transportation instead of owning your own vehicle, car pool or use Uber or a ride sharing service. The cost of car ownership is over $8,000 per year, roughly $650 per month, or $22 per day according to AAA’s 2016 Your Driving Cost Study. How much of your day is spent covering your car expenses, which according to Fortune is parked 95% of the time?

Continue Reading…

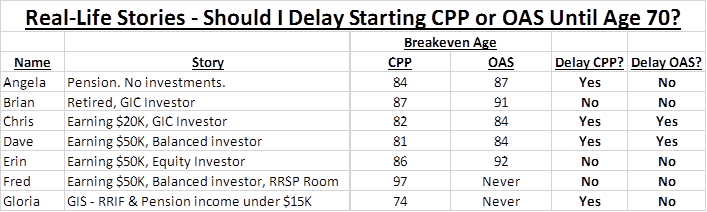
Delay CPP & OAS until 70? – Some case studies

By Ed Rempel

Special to the Financial Independence Hub

Planning the income for seniors often has the coolest opportunities to increase after-tax income.

The government pensions, CPP [Canada Pension Plan] and OAS [Old Age Security], are full of opportunities, because:

  • Seniors often have flexibility in taking taxable and non-taxable income.
  • OAS is subject to several “clawbacks” in addition to income tax.

To see these opportunities, you need to think creatively about pensions, tax and investments.

For example, in my recent article “Should I start my CPP early? – Real-Life Examples,” I found the single most important factor in whether to take CPP early before age 65 is how you invest.

Here you will see that the single most important factor in deciding whether to delay CPP after age 65 is: Will you withdraw more from your investments if you delay starting?

A quick review of the facts:

Delayed CPP Rules

  • The maximum CPP benefit in 2016 at age 65 is $1,092.50 per month, or $13,110 per year.
  • You can delay starting up to age 70 and you get 8.4% more for every year after age 65. If you start at age 70, you get 42% more for life, so the maximum is $18,616 per year.
  • New rules in 2012 allow you to start CPP even if you are still working.
  • If you are over 65 and still working, you can choose whether or not to pay into CPP.
  • Your 8 lowest earning years since age 18 (plus years when you had kids under age 7) are “dropped out” in calculating how much CPP you get.

Delayed OAS Rules

  • The maximum OAS benefit in 2016 at age 65 is $578.53 per month, or $6,942 per year.
  • You can delay starting up to age 70 and you get 7.2% more for every year after age 65. If you start at age 70, you get 36% more for life, so the maximum is $9,442 per year.

Continue Reading…

How to be wealthy & healthy, starting this Holiday Season

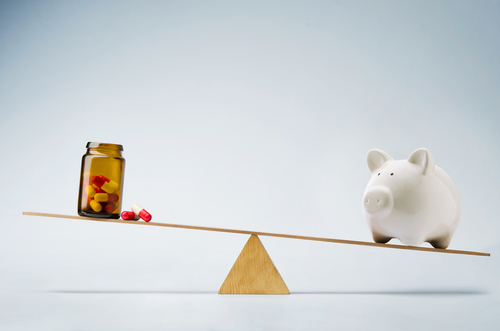
Piggy bank balancing on seesaw over a bottle of pills
You can balance Health & Wealth with advisors on both

By Sandy Cardy

Special the Financial Independence Hub

The Holiday season is a very personal balancing act.  Every year we experience the same thing – multiple events featuring gut-bloating menus and Boxing Day blow outs followed by crash dieting for both your waist-line and your bottom line. How do you find that sweet spot between making the season joyful and memorable while avoiding the perils of two to three weeks of over-eating and spending followed by a blizzard of credit card debt?

It’s no secret that Canadians, particularly Baby Boomers in their sixties, are doing a poor job of managing their retirement savings, falling well short of amassing enough retirement funds. Canadians still find it difficult to apply one of the simplest financial planning principles: pay yourself before you pay for anything else.

If, like many boomers, your retirement plan is increasingly looking like harnessing yourself to a full-time job as long as possible, what happens if you fall sick? And when you gaze with furrowed brow at your bloated credit card balances in January, not only are you even further from any savings goals, the sheer shock of the amount owing can add an unwelcome dollop of stress to already overtaxed minds and bodies.  Never knowing when enough is enough, there aren’t any checks and balances on our impulse to over-consume.

Here are some tips to get re-balanced for 2017:

Every money decision you make, even the little ones, will have an impact on your retirement. Perhaps what you need now is a qualified advisor to help you achieve your goals: someone you trust wholeheartedly. A good advisor will ensure you are realizing all cost savings, and applying tax minimization strategies to build your net worth. Put it this way: it’s much more difficult to neglect simple investment principles when a financial planner is looking over your shoulder.

Healthcare advisors as important as financial advisors

Similarly, having one or more health care advisors available is essential. Whether you encounter a health crisis or want to pursue preventative health,  it’s key to find  nurturing and optimistic healers, either conventional or alternative, ones that involve you in your health care discussion.

Continue Reading…