Tag Archives: Financial Independence

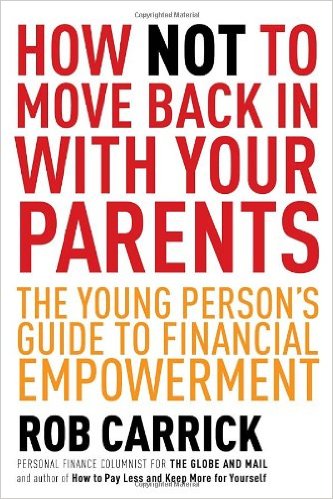
Review: How NOT to Move Back in with Your Parents

51UopHxeZ+L._SX331_BO1,204,203,200_You’re a millennial. You’ve recently graduated from university and are beginning your career. You aren’t making quite as much as you’d hoped for, and as it turns out, rent is crushingly expensive.

Okay, you’ll just put off moving out for six months, save some money, live at home. Everyone’s doing it these days. You’re sure that before you know it you’ll be on track to success, living it up in homeowner-ville, sitting pretty. You’re not quite sure exactly how you’ll get to homeowner-ville, but it can’t be that hard, right?

If any of this sounds plausible, I would seriously consider reading this wonderful book called How Not to Move Back in With Your Parents – The Young Person’s Guide to Financial Empowerment by Globe and Mail personal finance columnist Rob Carrick. I don’t want to be dramatic and say it will be your new finance bible, but it’s definitely a book you’re going to be referencing time and time again throughout those first few post-graduate years.

Something I really love about this book is that it’s broken down into great detail. Not only that, but it’s organized according to when in life you should be needing the advice.

Covering all the financial bases

Continue Reading…

Working part-time in Semi-Retirement a boon to finances

Man Hand writing Work Part Time with black marker on visual screen. Isolated on sky. Business, technology, internet concept. Stock PhotoI predict that many aging Baby Boomers will — either by preference or financial necessity — delay traditional full-stop Retirement and instead embrace Semi-Retirement.

My latest Retired Money column, which has just been published at MoneySense.ca, explores the positive effect on retirement nest eggs of working at least part-time after the traditional retirement age of 65. For full article and chart, click on Should you work part-time in retirement?

It’s based on an analysis by ETF Capital Management, which showed the powerful impact of earning just $1,000 in part-time income each month between the age of 65 and 75; or in the case of couples $2,000 a month between them.

Not working at all after the traditional retirement age of 65 has financial implications, never mind boredom and lack of social interaction. In the case of a retiree with lifestyle expenses of $60,000 who undertakes a full-stop retirement at 65, and earns no extra income, there is a sharp fall in a $500,000 (combined registered and non-registered) portfolio starting at age 65. By the time they reach their early 80s, the nest egg is depleted to zero.

But a couple earning just $2,000 a month between them part-time after 65 and going until 75 will find the extra income delays the portfolio’s drop below zero beyond their early 90s. Not only does the nest egg not decline the first ten years, but it actually rises! By the time you reach 75 and finally stop working even part-time, the portfolio declines from a higher level and much more gradually.

Of course, the more you work, the better: for a couple earning $3,000 a month between them, the portfolio still has more than $200,000 by their 90s!  Similarly, the analysis also shows what happens if you work extra hard, which many might argue wouldn’t even qualify as retirement. At $4,000 a month the portfolio is barely depleted at all by the time they reach 100!

Isn’t this really Semi-Retirement?

Continue Reading…

Millennials can learn from Boomers’ reinvention of Retirement

dcitizen2
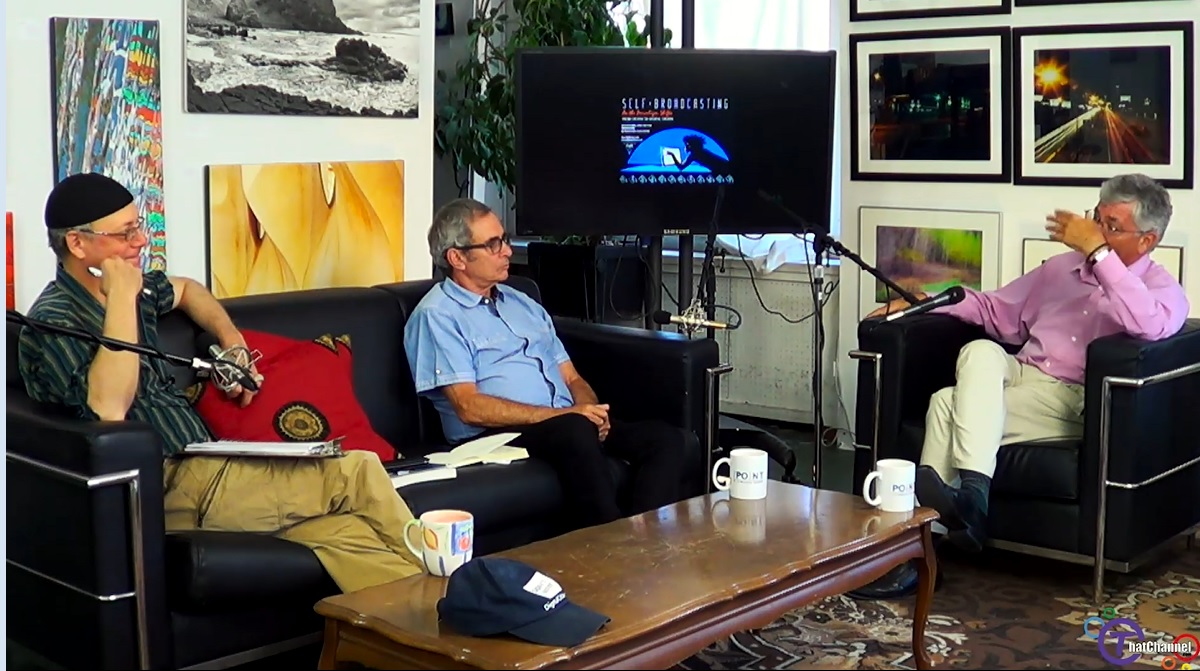
Digital Citizen Show. Left to right: Hugh Reilly, Norman Evans, Jon Chevreau

By Kollin Lore, Hub Staff

We are edging nearer to 2031, the year when all Baby Boomers will be age 65 and above, and most will at least be contemplating some form of Retirement or Semi-Retirement.

It will also be a time when the millennials will have pretty much all grown up and taken over the workforce.

Next month Jonathan Chevreau and Mike Drak’s Victory Lap Retirement will be published, a perfect time considering the age we are headed towards. However, though the book concerns the older generation, there is much to learn for millennials too.

Earlier in July, Chevreau discussed his upcoming book on Digital Citizen’s ThatChannel with creative director, Norman Evans, Laura Tyson, and host, Hugh Reilly. Click on the highlighted link to access the YouTube video: Get Ready to Earn Your “Playcheque.”

“The Boomers have reinvented every stage in life they have gone through,” said Chevreau. “Now they are going to reinvent retirement, by starting with the word ‘retirement’ because they are not ready to stop … That’s why Mike and I created the phrase Victory Lap.”

This titular ‘Victory Lap’ concerns finding that balance between stress and boredom following retirement. It means staying active and can include anything from travelling the world, to part time jobs, to volunteering to more time with family.

Of the many activities in which to partake during the Victory Lap, volunteering is an especially valuable past time to consider. Continue Reading…

Canada ranks 10th in global Retirement Security

Global investments and international finance business symbol with four blue eggs with the maps of the world in a nest as a concept of savings and money management in many regions as Asia North America Europe and Latin America.While it ranks ahead of the United States and the United Kingdom, Canada ranks in tenth place in a global retirement security survey being released today (Tuesday).

Several countries in northern Europe and Scandinavia rank higher in the study by Natixis Global Asset Management. Norway is number one, followed by Switzerland and Iceland. However, because of a revised methodology, Canada’s 2015 ranking is two spots higher than under the 12th place spot it had under the survey’s older methodology. The Natixis Global Retirement Index was introduced in 2013, and bases its overall retirement security scores on four factors affecting the lives of retirees.

A central component is of course finances but three sub-indices measure well being, health and quality of life, providing a more holistic view of retirement than mere financial considerations.

Low interest rates a drawback for Canadian retirees

Continue Reading…

Young, saving, and hopefully one day buying a house

IMG_7264By Helen Chevreau

Hub Staff

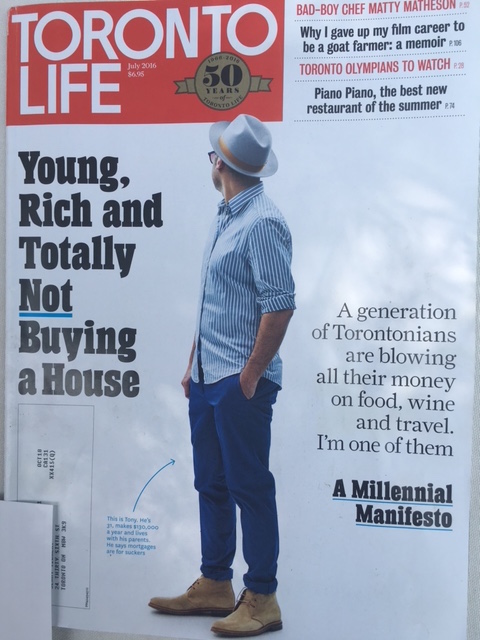
The cover story of this month’s Toronto Life magazine caught my eye straight away. “Young, Rich, and Totally Not Buying a House” it boldly claims.

As a young, not-yet-rich millennial who has no immediate plans to get into the housing market, I was intrigued. The article is written by 31-year-old Tony; a pharmacist who lives with his parents and eschews the traditional rites of passage of his peers, like home ownership.

Before I actually read the article, I was sure I wouldn’t like Tony, wouldn’t relate to him. Growing up in Toronto I’ve seen his type countless times. Money is no object, and he’s not shy to show it. A common defence from this kind of person is that ‘normal’ or ‘rational’ people who are judging him are jealous or boring (or both).

What I found interesting about this piece is that Tony seems very self-aware about his spending and lifestyle choices. He’s accepting of his friends who do choose to be “shackled to a monstrous mortgage for the next 30 years,” and he understands that sometimes it just isn’t possible to have it all.

Though much of what Tony talks about in this article is out of reach for most normal millennials (last minute trips to Asia, $200 bottles of wine), I appreciate the sentiment. Continue Reading…