Tag Archives: Financial Independence

Book Review: Ernie Zelinski’s Look Ma, Life’s Easy is a primer on Success

ZelnskicoverErnie Zelinski is a successful Edmonton-based author who has sold more than 900,000 books in 29 countries around the world. He has just published his latest book, titled Look Ma, Life’s Easy, which passes on his secrets for success, primarily to the millennial generation. .

Zelinski is best known for writing The Joy of Not Working and How to Retire Happy, Wild And Free, both of which sold hundreds of thousands of copies.

The new book takes a pseudo-fictional approach like the one famously used by David Chilton in The Wealthy Barber (or less famously, in my own Findependence Day!).

Zelinski’s subtitle is “How Ordinary People Attain Extraordinary Success and Remarkable Prosperity.” The story revolves around two characters, a young adult named Sheldon and his soon-to-be mentor Brock, described as a successful middle-aged man.

The Easy Rule of Life

Over the 200-plus pages of the book Brock imparts to Sheldon his secret of success, which he calls The Easy Rule of Life.

This is the main takeaway, which has a certain amount of paradox in it: Continue Reading…

What every woman needs to know about Retirement

what_every_woman_needs1
Akaisha Kaderli

By Akaisha Kaderli

Special to the Financial Independence Hub

The other day I read an article about women and retirement. In this piece, the number one premise for motivation was that we should be afraid. Very afraid. It said that for the most part, men did the planning for retirement and that we as women rely on them blindly.

I dislike reading articles such as this, first, because it is fear-based but second, it doesn’t take into consideration the talents women contribute to the mix of partnership and planning. While it might be true that men are “wired to provide for the household,” women have moved into professions which pay grandly. Many marriages today are a different blend of partnership than what our own parents or grandparents enjoyed. Along with their jobs, many women still run the household, so why not get involved in retirement planning in a proactive manner?

Retirement is a boring word

The word “retirement” conjures up images of old people on pensions or perhaps pictures of those who no longer contribute powerfully to society with their expertise and knowledge. I prefer the description “financially independent” for the freedom, influence and self-reliance it implies.

One can choose financial independence at any stage of life and it’s an exciting and worthy goal. The younger a person begins on this path, the more you have in your favor.

Women, listen up

Continue Reading…

Review: The Procrastinator’s Guide to Retirement

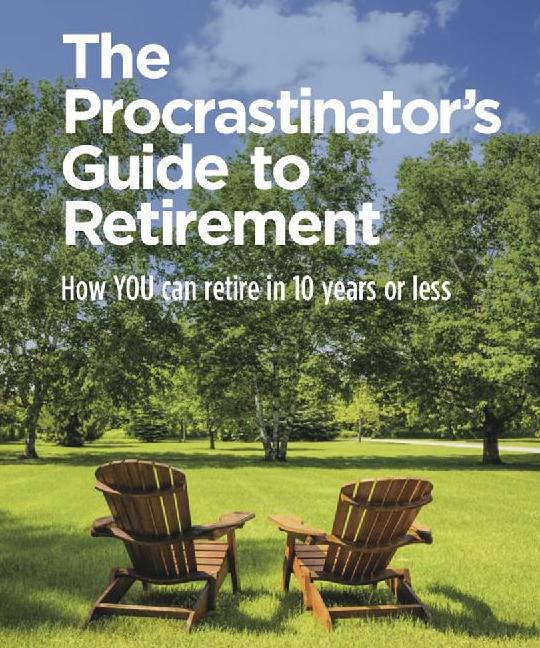
TPGTRI have to hand it to financial author David Trahair. He and his publishers have come up with a catchy title that’s bound to sell a few copies of his latest (sixth) book. It’s titled The Procrastinator’s Guide to Retirement and sports an equally alluring subtitle: How YOU can retire in 10 years or less.

You can find a Q&A I conducted with Trahair about the book here at MoneySense.ca.

When I perused the book initially, my first impression was that there seemed to be relatively little about procrastination and the critical last ten years of Retirement. The book doesn’t have an index but my initial perception was that the book is a standard-issue retirement guide covering all the good things you should do throughout your working career, not just the final ten years.

Which came first, the book or the title?

Continue Reading…

Debt is more than a four-letter word during your drawdown years

_MG_4309
Doug Dahmer

By Doug Dahmer, Emeritus Financial Strategies

Special to the Financial Independence Hub

 The month of April is always a particularly busy time for Retirement Income Specialists. One of our key roles is to provide each of our clients with a year-by-year draw-down recipe: outlining how much and where to source their annual cash flow needs.

The ultimate goal is not to minimize the amount of income tax they pay on any given year, but instead to minimize the amount of tax they pay over the balance of their lives. (Please note these two goals are frequently confused, and seldom accomplished simultaneously as often you will need to pay more tax sooner in order to pay significantly more later.)

One of our many sources of insight for the guidance we provide is found within our clients’ annual tax returns. At the same time our clients’ previous year’s tax returns act much like a report card, keeping them informed as to how well we performed our role over the previous year, as we endeavor to accomplish this important long term goal.

Debt can more than offset taxes

Continue Reading…

How much do you REALLY need to retire?

MarieEngen
Marie Engen, Boomer & Echo

By Marie Engen, Boomer & Echo

Special to the Financial Independence Hub

I’ve given you the challenge of thinking about what sort of retirement lifestyle you want to have. You’ve also determined, as well as you can, what income you may be likely to receive when you retire.

It’s quite frustrating to try to figure out how much money you will need for your desired retirement. How can you decide without having some idea of how much it will cost? Is dreaming of exotic vacations and travelling around the world on a 13-m yacht realistic? Or should you be thinking about reading a book on your deck? Many people have no idea what they’re even aiming for.

Since we all like to compare ourselves to others to see where we stand, here’s what the average retiree spends for three different levels of retirement lifestyles:

(Sources: BMO retirement survey and the Government of Canada).

Basic – Low Budget

Canada makes sure that seniors don’t live in extreme poverty. A 65-year-old couple who each receive average CPP payments ($640.23 per month) as well as Old Age Security and Guaranteed Income Supplement would receive a little over $32,000 per year. A single 65-year-old would get just over $19,000.

Also read: Continue Reading…