Tag Archives: Financial Independence

5.8 million working Canadians will see 20% drop in income in Retirement

benjamin-tal
Benjamin Tal (CIBC)

Almost 6-million working Canadians risk losing the “retirement of their dreams,” according to a CIBC report getting lots of attention today at the Globe & Mail website. CIBC deputy chief economist Benjamin Tal (pictured) says some 5.8 million working-age Canadians will suffer at least a 20% drop in their standard of living once they leave the full-time work force.

The short article is listed as one of the most popular today on the site and has attracted dozens of comments and social media mentions.

Stop me if you think you’ve heard this before but it seems the bank believes the country’s retirement system needs to be reformed as quickly as possible. The most recent move in this direction came from an apparent about-face by the Conservative Government, whose apparent refusal to consider an expanded or “Big” CPP motivated the Ontario government to launch a new retirement system of its own, the ORPP or Ontario Retirement Pension Plan. Then last week, Finance Minister Joe Oliver floated a trial balloon for a “voluntary” expansion of the CPP, which the Hub reprised on the weekend.

Younger middle-income workers with no DB plans at risk

Mr. Tal told the Globe that “it’s not just CPP,” but expressed concern that Canadians still aren’t saving enough money. While many Canadians close to the traditional retirement age of 65 are “on a path to the retirement of their dreams,” Tal’s data also shows millions others, especially younger workers in the middle-income brackets, “are headed for a steep decline in living standards in the decades ahead.”
Continue Reading…

Conscious Clients don’t put Retirement plans at Risk

dougdahmer
Doug Dahmer

By Doug Dahmer, Emeritus Retirement Income Specialists

Special to the Financial Independence Hub

One of the most exciting and rewarding aspects of my job is working with my clients as they learn what I call ‘Conscious living.’ It’s a skill that has tremendous impact on their quality of life and their retirement plan.

My ‘Conscious’ clients have a retirement plan and clearly defined goals. They know what they want to do, when they want to do them and how big they want to do them. They also have the tools to explore the implication of each financial decision or potential alteration to their plan. And they understand the future impact that an ill-considered, near-term expenditure will create – in most cases putting some element of their goals and retirement plan at risk. Continue Reading…

The 6 stages of Financial Independence

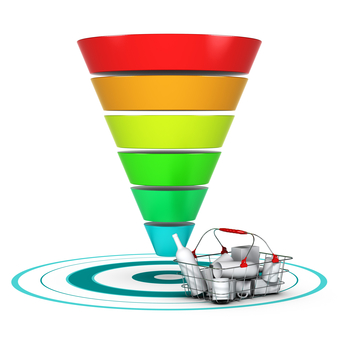
Sales funnel. Marketing or Business ChartBy Jonathan Chevreau

The Financial Independence Hub

I’ve been doing lots of reading lately about a new stage of life between MidLife and traditional Retirement. You can read the details in Marc Freedman’s The Big Shift, which confirmed what I’ve been slowly piecing together since my career change this time last year.

The  Financial Independence Hub organizes blogs in six categories that are quite similar to the Ages & Stages that MoneySense has long espoused, both in its articles and in its Special Interest Publication, Guide to Retiring Wealthy. You can find these six blog categories in the horizontal grey band that appears below the horizontal blue band at the top of the Hub’s home page.

Ages & Stages: The Life Cycle approach to Investing

Continue Reading…

Re-introducing Tontine Annuities Might Shave Years Off Your Findependence Day

013__C1A2178
Moshe Milevsky

By Moshe A. Milevsky

Special to the Financial Independence Hub

Here is a non-surprising fact. Most retired individuals do not choose to voluntarily annuitize their accumulated wealth or savings at retirement. They prefer the lump sum. This has been christened by financial economists: “the annuity puzzle” and has been the topic of Ph.D. theses for decades. I am guilty of supervising a few of these myself.

Sadly, life annuities are relatively unpopular – especially compared to stocks and bonds — in a large part of the world and simply unavailable in most others. Indeed, the few jurisdictions and countries in which there is a sizeable market for annuity products – such as Canada or the U.S. — it is often driven by tax-advantaged treatment and/or government “nudging and defaults” as opposed to an intrinsic consumer appreciation for longevity insurance. Like most insurance products, they are ‘sold’ but rarely purchased.

Could the past hold the key to Longevity Insurance?

Continue Reading…

Crashing Through The Retirement Barrier

A green word Freedom crashes through the walls of a maze to break through the barriers of oppression

By Michael Drak,

Special to the Financial Independence Hub

On May 6th 1954, Roger Bannister became the first person in the world to run a sub-4 minute mile. At the time no one believed the human body was capable of going that fast and although many had tried none had succeeded up to that point. Then along came Roger Bannister, who ignored the nay-sayers and posted a mile of 3 minutes 59.4 seconds.

The interesting thing is that after the sub-4 minute mile limitation was broken many other athletes posted sub-4 minute times, starting almost immediately after Roger Bannister proved it could be done.

Self-imposed mental barrier

So what happened, why the sudden success? Continue Reading…