Tag Archives: investing

Investing in the Cannabis Market

Five months into the legalized marijuana market, it’s a good time to remind ourselves of basic investment principles. Get good advice you trust.
 

By Kevin Greaves, MyResolver.ca

Special to the Financial Independence Hub

Perhaps not since the dot com boom of the 1990s have we seen the kind of investor interest in a sector that we’re now seeing in the marijuana market.  Seasoned investors and newcomers alike are excited by the prospects of this nascent market and risk is rampant.  In the months leading up to, and the four months following legalization in Canada, there has been huge volatility in stock prices for some of the major players and the valuations of many of these companies is often characterized as ‘out of whack’.   For instance, market leader Tilray (TSX:TLRY) was valued greater than American Airlines Group in September 2018.  That is high! (Pun intended)

So, if you’re looking to add marijuana stocks to your portfolio, there’s a lot to take in at the moment.  It’s not easy to keep on top of the news of mergers, partnerships, earnings reports and growth forecasts in an emerging sector, and you could find yourself caught up in the hype.  So first and foremost, it’s good to work with a trusted investment advisor.  An advisor can help to put disclosure documents in perspective and assist in choosing an investment that suits your financial goals. Even if you are an experienced investor, accustomed to doing your own research and trades, having an advisor to confirm or correct your strategies, even just initially, could help you avoid some costly mistakes.  There are plenty of articles on the value of an advisor, and how to find one, so that’s not a topic we will cover in depth here.

Investor or Speculator?

Warren Buffett’s mentor, Benjamin Graham believed it was crucial to determine whether you are acting in the market as an investor or a speculator.  The distinction is fairly simple.  As an investor, you buy a stock in a company you believe will be successful and that stock represents ownership in the company.  You have a stake in the future of that company.  As a speculator, your only concern is what someone will pay for that stock down the line.

Some would argue that all investment is a combination of the two but it’s an important differentiation to make when you are working with an emerging market sector.  It allows you to clarify your expectations and often, the timeline for your ROI and the amount of risk you are prepared to take.

It’s important to remember that marijuana is a commodity: plain and simple.  And as a commodity it is subject to the same booms and busts as other commodities.  As an agricultural commodity it holds additional risks.  Think of all the uncertainties of growing any crop:  the introduction of a single pest can wipe out an entire harvest.

Consider ancillary products and players

There are opportunities beyond investing in producers of marijuana and if you’re considering investing in this sector, you may want to look beyond the obvious.  Certainly, Biotech stocks have been around for decades but with more and more information available regarding the medical uses of cannabis, there will be expanded opportunities for companies to develop drugs and treatments for various diseases, conditions and illnesses.  For instance, creams and oils derived from CBD, the non-intoxicating compound of the marijuana and hemp plants, have shown great promise in the treatment of epilepsy and arthritis.
Continue Reading…
U.S. Economy Watch: Searching for Clues


By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

After at least a month-long delay, fixed income investors have finally been receiving economic data. With a number of government agencies closed due to the recent shutdown, 2019 began with a data vacuum, but now it looks like we are making up for lost time. Unfortunately, these “data delays” render some of the economic information potentially old or stale. Nevertheless, the data still offers insights as to how 2018 ended and can provide clues on any possible springboard effects for the current year.

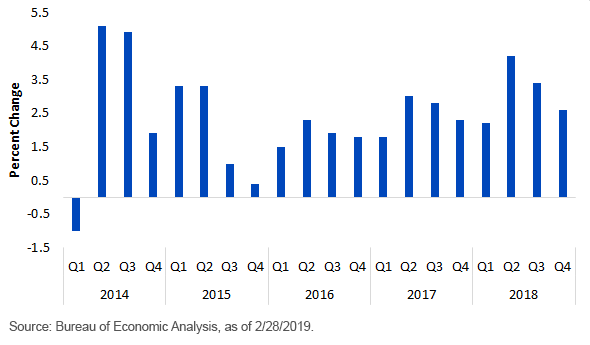
A perfect case in point is last month’s release of the Q4 2018 real GDP report. Yes, the data is three months old, but the underlying components in this release can offer insights for the future. First, let’s go high level and look at some headline numbers. For Q4, the Bureau of Economic Analysis’ (BEA) initial estimate for growth was pegged at +2.6%. While this was a drop-off from the Q3 pace of +3.4%, it beats consensus forecasts by nearly half a percent. For 2018 as a whole, real GDP came in at +2.9%. This rate of expansion has been reached only two other times since 2005. On a Q4/Q4 basis, growth was pegged at +3.1%, finally eclipsing the elusive 3% threshold.

U.S. Real GDP

US Real GDP q4 2018

While recession fears have been a part of the economic dialogue, the ongoing debate seems to be more centered on what type of slowdown we should expect in 2019. The accompanying graph illustrates that growth has trailed off a bit after reaching its most recent high-water mark of +4.2% in Q2. Some further deceleration is likely. In fact, Q1 2019 real GDP will likely be held down by the aforementioned shutdown, but then snap back in Q2 as those negative effects are reversed. Overall, real GDP in the area of +2¼% is my base case for this year.

Let’s take a look at the GDP engine cylinders:

Personal consumption expenditure (PCE): Household spending rose at a +2.8% annual clip in Q4, which translated to a 1.9 percentage point (pp) contribution to growth. This component should continue to be a positive force for the economy this year. Continue Reading…

10 surprises for Japan in 2019


By Jasper Koll, WisdomTree Investments

Special to the Financial Independence Hub

2019 is likely to be a good year for Japan. While worries about U.S. and China recessions create global headwinds and uncertainty, domestic Japan is well placed to decouple from the global cycle and deliver rising employment and increased purchasing power for its people. However, there are bound to be surprises: that is, scenarios not captured by experts’ current quantitative models or the crowd’s consensus opinion. For Japan in 2019, here are the outlier scenarios that I personally worry about. Improbable as they may seem, any movement toward their far-out direction will force a true about-face in the current consensus. That’s why surprises are so powerful. Enjoy, and best wishes for a prosperous and happy new year 2019.

1.) The 2019 shunto wage negotiations result in a 4% pay raise, up from the 2% delivered last year

Japan’s economy needs a more powerful engine to drive domestic consumer spending. After years of wage restraint and company unions preferring long-term job stability over short-term wage gains, the labor market is now so tight that wage growth should start to accelerate. If I am right and the 2019 shunto results in a de facto doubling of the pay base, consumption-led growth could become a reality. The higher the shunto, the greater the chances of Japan decoupling in a positive way from a global downturn.

2.) Prime Minister Abe convinces China to join the new Trans-Pacific Partnership (TPP)

2019 is likely to see a turning point in Japan-China relations. After their successful summit in October 2018, Prime Minister Shinzo Abe and President Xi Jinping are committed to not just improved bilateral relations but also to assert a more credible joint leadership role in Asia. For China, nothing would demonstrate a true commitment to accountable Asian leadership better than joining the new multilateral TPP free trade agreement. For Japan, bringing China into the new TPP would irrevocably elevate its status as global leader and protector of multilateral rulemaking. Moreover, Abe would go down in history as the statesman who built a positive buffer for all Pacific nations against their fears of the unilateral rise of China: cooperative engagement, not unilateral submission.

3.) The United States moves from trade war to currency war as the Federal Reserve (Fed) is forced to cut U.S. interest rates

As U.S. recession risks rise, the probability of a U-turn in U.S. interest rate policy goes up: after four rate hikes in 2018, the Fed could actually start cutting rates by next summer. In turn, U.S. rate cuts will forcefully push down the dollar. Unfortunately, neither China nor Europe is in a position to tolerate this. China in particular is already very outspoken in its opposition to a new Plaza Accord (where Europe and Japan agreed to a U.S.-imposed weak-dollar policy in 1985). Make no mistake: the next U.S. recession is likely to trigger a global currency war (i.e., competitive devaluations). Importantly, it is no longer the U.S.-Japan but the U.S.-China exchange rate that will dictate global fortunes in 2019 and beyond.

4.) A Japanese mega-bank buys a major U.S. bank

Some good news for Japan: The fall in the U.S. stock market has lowered the price to buy American companies. Japanese banks have been eager to expand in the U.S. but were put off by the high prices and valuations of U.S. banks in the past couple of years. Now that the U.S. cycle has turned, Japanese bank CEOs may finally get their chance to act out their strong global ambitions and buy a “cheap” U.S. bank in 2019.

5.) The Bank of Japan (BOJ) and the Finance Ministry cooperate to sell the BOJ’s exchange-traded fund (ETF) equity holdings to Japanese savers

The BOJ owns almost 6% of the Japanese equity market through its buying program for ETFs. While justifiable as an emergency measure to help overcome deflation, the central bank’s de facto nationalization of equity capital has become counterproductive for many reasons. Continue Reading…

Vanguard announces the passing of founder John C. Bogle

The investment industry is saddened to learn of the passing of Vanguard founder John C. Bogle today. A true giant of the industry, Bogle was virtually the creator of index mutual funds and ETFs, and passive investing in general. Below is the press release issued today by Vanguard, which we reprint in full. I have added a few subheads and made only very minor edits.  

VALLEY FORGE, PA (January 16, 2019) — Vanguard announces the passing of John Clifton Bogle, founder of The Vanguard Group, who died today in Bryn Mawr, Pennsylvania. He was 89.

Mr. Bogle had legendary status in the American investment community, largely because of two towering achievements: He introduced the first index mutual fund for investors and, in the face of skeptics, stood behind the concept until it gained widespread acceptance; and he drove down costs across the mutual fund industry by ceaselessly campaigning in the interests of investors. Vanguard, the company he founded to embody his philosophy, is now one of the largest investment management firms in the world.

“Jack Bogle made an impact on not only the entire investment industry, but more importantly, on the lives of countless individuals saving for their futures or their children’s futures,” said Vanguard CEO Tim Buckley. “He was a tremendously intelligent, driven, and talented visionary whose ideas completely changed the way we invest. We are honored to continue his legacy of giving every investor ‘a fair shake.’”

Mr. Bogle, a resident of Bryn Mawr, PA, began his career in 1951 after graduating magna cum laude in economics from Princeton University. His senior thesis on mutual funds had caught the eye of fellow Princeton alumnus Walter L. Morgan, who had founded Wellington Fund, the nation’s oldest balanced fund, in 1929 and was one of the deans of the mutual fund industry. Mr. Morgan hired the ambitious 22-year-old for his Philadelphia-based investment management firm, Wellington Management Company.

Mr. Bogle worked in several departments before becoming assistant to the president in 1955, the first in a series of executive positions he would hold at Wellington: 1962, administrative vice president; 1965, executive vice president; and 1967, president. Mr. Bogle became the driving force behind Wellington’s growth into a mutual fund family after he persuaded Mr. Morgan, in the late 1950s, to start an equity fund that would complement Wellington Fund. Windsor Fund, a value-oriented equity fund, debuted in 1958.

In 1967, Mr. Bogle led the merger of Wellington Management Company with the Boston investment firm Thorndike, Doran, Paine & Lewis (TDPL). Seven years later, a management dispute with the principals of TDPL led Mr. Bogle to form Vanguard in September 1974 to handle the administrative functions of Wellington’s funds, while TDPL/Wellington Management would retain the investment management and distribution duties. The Vanguard Group of Investment Companies commenced operations on May 1, 1975.

The “Vanguard experiment”

To describe his new venture, Mr. Bogle coined the term “The Vanguard Experiment.” It was an experiment in which mutual funds would operate at cost and independently, with their own directors, officers, and staff—a radical change from the traditional mutual fund corporate structure, whereby an external management company ran a fund’s affairs on a for-profit basis.

“Our challenge at the time,” Mr. Bogle recalled a decade later, “was to build, out of the ashes of major corporate conflict, a new and better way of running a mutual fund complex. The Vanguard Experiment was designed to prove that mutual funds could operate independently, and do so in a manner that would directly benefit their shareholders.”

First index mutual fund in 1976

In 1976, Vanguard introduced the first index mutual fund — First Index Investment Trust — for individual investors. Ridiculed by others in the industry as “un-American” and “a sure path to mediocrity,” the fund collected a mere $11 million during its initial underwriting. Now known as Vanguard 500 Index Fund, it has grown to be one of the industry’s largest, with more than $441 billion in assets (the sister fund, Vanguard Institutional Index Fund, has $221.5 billion in assets). Today, index funds account for more than 70% of Vanguard’s $4.9 trillion in assets under management; they are offered by many other fund companies as well and they make up most exchange-traded funds (ETFs). For his pioneering of the index concept for individual investors, Mr. Bogle was often called the “father of indexing.”

1977: Direct to investors

Mr. Bogle and Vanguard again broke from industry tradition in 1977, when Vanguard ceased to market its funds through brokers and instead offered them directly to investors. The company eliminated sales charges and became a pure no-load mutual fund complex—a move that would save shareholders hundreds of millions of dollars in sales commissions. This was a theme for Mr. Bogle and his successors: Vanguard is known today for maintaining investment costs among the lowest in the industry.

A champion of the individual investor, Mr. Bogle is widely credited with helping to bring increased disclosure about mutual fund costs and performance to the public. His commitment to safeguarding investors’ interests often prompted him to speak out against practices that were common among his peers in other mutual fund organizations. “We are more than a mere industry,” he insisted in a 1987 speech before the National Investment Company Services Association. “We must hold ourselves to higher standards, standards of trust and fiduciary duty. Change we must—in our communications, our pricing structure, our product, and our promotional techniques.”

Mr. Bogle spoke frequently before industry professionals and the public. He liked to write his own speeches. He also responded personally to many of the letters written to him by Vanguard shareholders, and he wrote many reports, sometimes as long as 25 pages, to Vanguard employees — whom he called “crew members” in light of Vanguard’s nautical theme. (Mr. Bogle named the company after Admiral Horatio Nelson’s flagship at the Battle of the Nile in 1798; he thought the name “Vanguard” resonated with the themes of leadership and progress.)

In January 1996, Mr. Bogle passed the reins of Vanguard to his hand-picked successor, John J. Brennan, who joined the company in 1982 as Mr. Bogle’s assistant. The following month, Mr. Bogle underwent heart transplant surgery. A few months later, he was back in the office, writing and speaking about issues of importance to mutual fund investors. Continue Reading…

Make Investing great again …. one day? Part 2


By Aman Raina, Investment Coach, Sage Investors

Special to the Financial Independence Hub

In Part 1, I shared some thoughts on a recent report by the Ontario Securities Commission (OSC) outlining the challenges the financial services industry is having in getting Millennials to invest. The OSC report had a great opportunity to address those investing pain points, but like so many financial literacy initiatives, the messaging is not clear, consistent, and understandable. The report identifies solutions, yet they are separate and not integrated and use a lot of industry jargon that people just won’t connect with. They emphasize processes over results. What is the outcome we want Millennials to achieve with investing?

Another way?

In this post, I’d like to share from my experience as Investment Coach and as someone who works with people to develop their investing competencies, some approaches that I found have better motivated people and not just Millennials into becoming more engaged with investing. They address the pain points people have with expressed about investing which include; being scared of investing, feeling overwhelmed by the process, feeling paralyzed when trying to make a decision, and not knowing how to start and take that first step. These are my takes and perspectives. They are by no means the most definitive and all encompassing. 

The First Step: Define the investing path

The OSC report identified taking the first step in investing as a major pain point for people. For most people, after they have the epiphany that they should start growing their savings and invest, the most common series of events that occur include opening a brokerage account, buying some books or researching investing on the Internet or simply doing what their peers are doing. They buy a few stocks and some work out and some don’t and that’s where the fear pain point comes in.

The default for investing seems to be buying stocks, but does this really apply to everyone? In Part 1, I said that investing can be a very boring, repetitive, and time consuming process. Investing in stocks requires a major time commitment to analyze and evaluate stocks and managing the portfolio. For a lot of people, they really couldn’t be bothered to learn about investing because they have other more pressing priorities in their life … and that’s OK.

There are different investing paths we can take but ultimately we want to be on an investing path that compatible our life situation. If I don’t have the time to invest maybe I should consider working with a financial advisor, maybe use a robo-advisor service. Maybe buying a basket of Exchange Traded Funds (ETF’s) is a better path than buying individual stocks. 

Why are you investing?

It is critical that at the people define right away the appropriate investing path they want to travel. It begins with defining what the end of the path looks like (Why am investing?) as well how the road will be travelled. Will I travel it alone (Do-It-Yourself) or with someone else?

Once you’ve been able to answer these questions and defined a path, then you will have defined and reduced your scope of investments that you will use and begin work on building your investing competencies. Why learn about investing in stocks when you will be investing in ETFs?

The investment industry doesn’t really take the time to work with people on defining their investing path because they established a default that people that come to them want to invest in stocks when in reality they may have no interest or tolerance for it. The starting point is such a difficult pain point for many because once they begin to follow an investing path that was not compatible with their life and quickly they fell off it and into a ditch, it becomes harder to emotionally get back at it. These type of conversations need to happen before opening a broker account or signing up for an investing course.

Building investing competencies

I view financial literacy to be more about building competencies, more specifically investing competencies. From my experience, the people that have this investing thing pretty figured out possess three competencies. My role as an Investment Coach is to help people develop these investing competencies. 

Competency 1: Education – Principles versus Formulas

Once we have defined an investing path, we can target our learning to focus on developing our investing competencies in those areas. If we are committed to investing in individual stocks then we should focus our education on learning that area. Most investing education focuses on the mechanical aspects of investing and those mechanics which involve formulas, spreadsheets, and math trigger people’s pain points of finding investing overwhelming. Continue Reading…