No matter what stage of life you are in, it is important to know your financial health. This is not something you do just around income tax time but throughout the year. It’s good to check in at least monthly or, as we do, daily. The same as any successful business must know their income and liabilities, so should you.
Today there are plenty of free online tools that can help you, but we are old school and prefer to be able to check and edit our data anywhere in the world and at any time regardless of an internet connection. We have done this since we retired in 1991. Back then we used a paper notebook and pen, but today we created a spreadsheet using an Excel program that is on most computers sold today.
How it works
Throughout the day as we spend money we keep a mental note of the cost. Then, usually in the evening while winding down, we enter the data into our spreadsheet. We created categories such as housing, food, dining, transportation, donations, healthcare, and so on. Each of those entries then gets automatically added giving us a total for the day. That number is added to all of the previous entries and then divided by the day number in the year, 1 through 365, giving us a daily average.
Utilizing this system we can adjust the entries using local currencies, therefore knowing what we are spending in Mexican Pesos, Thai Baht, Vietnamese Dong, Guatemalan Quetzales or the money of any place where we are traveling. While this figure can easily be converted to dollars if we want, we prefer to think of our costs in the currency of our host country. This keeps our spending at the perspective of the natives instead of distorting it by thinking in Dollars.
This information is important
Once you know how much you are spending per day you can utilize this information to adjust spending accordingly if necessary. You are in control of your outflow at this point, and you can make changes in real time.
Net worth: What is it?
Another important tool for understanding your financial health is calculating your net worth. This number is derived by adding up all of your assets minus your liabilities. Do you own a house or rentals? Figure out what they are worth, then subtract out what you owe and this equates to the equity you have. It is important to use realistic numbers knowing that if you sold today, there would be fees and expenses involved as well as taxes to be paid. Do you have cars? Even though they are a depreciating asset, meaning they lose money over time, you still have some value there. How about retirement accounts? IRAs or RRSPs, 401(k)s or Defined Contribution pensions, regular banking and brokerage accounts, credit-card and student loan debt: all need to be factored into the equation.
This information is a powerful retirement tool
Now that you know your net worth and what you are spending per day, you can take further control of your future by figuring out what percentage of your net worth you are spending. Continue Reading…
Does the “global trade war,” quotation marks intentional, spell doom? It depends on your silo.
The 2009 American Recovery and Reinvestment Act poured some C$1.03 trillion of stimulus into the system, while China’s coincident crisis-era package dumped a C$768 billion package on top.1Central banks added trillions in bond purchases for the trifecta.
But some people may have missed the boat. Who? Those who couldn’t get past their ideological differences with the last U.S. president, who made some of them think the global financial crisis would lead to a perpetual depression. Distorted reality costs money, and what happened with Obama’s detractors is now happening in the Trump administration. Some proportion of the public, including many on Wall and Bay Streets, are letting their political views with respect to President Trump get in the way of arithmetic.
That can create opportunity for the sober observer.
What is one mistake investors are making? Prognosticating “global trade war” doom.
Global Trade War?
2018 has witnessed nothing but improvement in relations between China and Japan, nothing but improvement in relations between Japan and Europe and, arguably, nothing but improvement in relations between the U.S. and both Mexico and Canada, at least compared to this past summer.
Some global trade war this is, with major foreign leaders jumping over each other to prove their free market bona fides.
“We must promote trade and investment, liberalization and facilitation through opening up—and say no to protectionism.”— Chinese President Xi Jinping, 2017
“It is also quite vital that we keep on raising high the flag of free trade.” — Japanese Prime Minister Shinzo Abe, 2017
“We believe multilateral cooperation can add value for everyone, and that’s why we’re advocating global trade that is as free as possible and which is based on common rules. ”— German Chancellor Angela Merkel, 2018
The truth is that Trump is calculating that Americans have finally hit a wall on the status quo with respect to China. Regular people on the street may not know the specific trade numbers, but they know where the knock-off purses come from, they know now about wanton intellectual property theft and, most disconcertingly, cyberwarfare.
In reframing the argument about global trade, does anyone care that Japan, China and South Korea are sitting at the table with one another for trilateral trade talks?2How about the big August trade deal between Japan and the EU? Talk about large economies.
While market angst is focused on the Trump administration’s “global trade war,” most of the planet is actively making deals, in direct contrast to the meme of global internecine tariff warfare.
And China’s Scythe on Taxes
While markets react to headlines, China’s fiscal stimulus continues apace. Some investors appear to be missing the good in hoping for Trump to prove an economic failure. One such “good” is the total revolution happening in China’s personal income tax code, shockingly ignored by so many. Figure 1 shows the C$565 tax cut that the average white-collar Chinese worker, earning C$17,689 a year, is set to witness. There’s more too if we count mortgage, student loan and child deductions (figure 1).3
Figure 1: Proposed China Personal Income Tax Example, Average White-Collar Worker
That comes on the heels of this spring’s 1% cut in value-added tax (VAT) rates. Combined with income tax relief, we count C$135 billion in cuts this fiscal year alone (figure 2).4
Figure 2: VAT + Personal Income Tax Cuts, 2018 Amount
Granted, there are offsets. For example, Beijing is also vaguely promising reductions in social insurance premiums, but that may be more than offset by the tax authority’s ratcheting up of collections efforts this year. The result could be a net tax hike on this front.
Nevertheless, figure 3 shows the decade-long effect of Chinese President Xi Jinping’s tax cuts on the VAT and personal income fronts. At slow-to-fast growth rates, the cumulative 10-year estimate is C$1.35 trillion to C$2.66 trillion, straddling both sides of Trump’s C$1.97tn package that sent stocks higher in 2017.
Figure 3: Cumulative 10-Year Total, Xi Tax Cuts (Using WisdomTree’s C$135bn Calculation for 2018)
Meanwhile, we present figure 4; China’s exports to the U.S. have been shooting higher in a largely uninterrupted fashion for most of this century.
Figure 4: Annual USD Chinese Exports to the U.S.
The Play
Our TSX-listed dedicated China strategy is the WisdomTree ICBCCS S&P China 500 Index ETF (CHNA.B). It hits broad China with a 9+% earnings yield and tracks China’s S&P 500.5Because it is so broad, it can be used as a single line item for a portfolio’s entire Chinese equity exposure.
While the mass of investors focus on “global trade wars,” few observers are noting Chinese fiscal expansion or, for that matter, big trade deals being signed right now. There’s your edge, contrarian reader.
1Sources: Congressional Budget Office, Publication 49958, Estimated Impact of the American Recovery and Reinvestment Act on Employment and Economic Output in 2014. Chinese stimulus data by The Economist, China Seeks Stimulation, 11/10/08.2Source: Laura Zhou, “China, Japan and South Korea Aim to Speed Up Talks on Free-Trade Agreement to Counter U.S. Tariffs,” South China Morning Post, 9/22/18. 3Average white-collar worker income calculated by Zhaopin Ltd., a career platform similar to Monster.com, as of end-2017. Tax cut calculations by WisdomTree, using the PBoC’s tax proposal that is likely to become law in October. 4See source data beneath Figure 1. 5Sources: Bloomberg, WisdomTree, as of 10/24/18.
Jeff Weniger, CFA serves as Asset Allocation Strategist at WisdomTree. Jeff has a background in fundamental, economic and behavioral analysis for strategic and tactical asset allocation. Prior to joining WisdomTree, he was Director, Senior Strategist with BMO from 2006 to 2017, serving on the Asset Allocation Committee and co-managing the firm’s ETF model portfolios. Jeff has a B.S. in Finance from the University of Florida and an MBA from Notre Dame. He is a CFA charter holder and an active member of the CFA Society of Chicago and the CFA Institute since 2006. He has appeared in various financial publications such as Barron’s and the Wall Street Journal and makes regular appearances on Canada’s Business News Network (BNN) and Wharton Business Radio.
Important Risks Related to this Article
There are risks associated with investing, including possible loss of principal. Foreign investing involves special risks, such as risk of loss from currency fluctuation or political or economic uncertainty. The Fund focuses its investments in China, including A-shares, which include risk of the RQFII regime and Stock Connect program, thereby increasing the impact of events and developments associated with the region, which can adversely affect performance. Investments in emerging or offshore markets are generally less liquid and less efficient than investments in developed markets and are subject to additional risks, such as risks of adverse governmental regulation and intervention or political developments. The Fund’s exposure to certain sectors may increases its vulnerability to any single economic or regulatory development related to such sector. As this Fund can have a high concentration in some issuers, the Fund can be adversely impacted by changes affecting those issuers. The Fund will be required to include cash as part of its redemption proceeds which introduces additional risks, particularly due to the potential volatility in the Chinese market and market closures. The Fund invests in the securities included in, or representative of, its index regardless of their investment merit and the Fund does not attempt to outperform its index or take defensive positions in declining markets. Due to the investment strategy of this Fund, it may make higher capital gain distributions than other ETFs. Please read the Fund’s prospectus for specific details regarding the Fund’s risk profile.
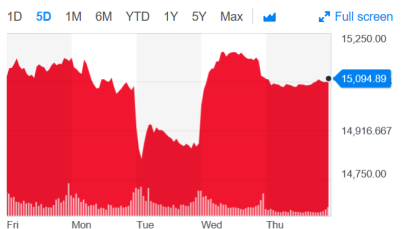
The Canadian markets have been offering investors a little taste of volatility. Here’s a one week chart going back to last Friday.
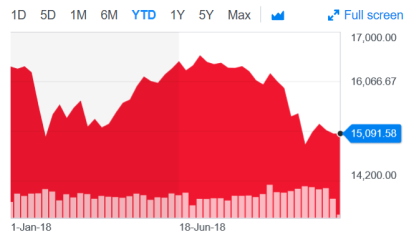
And here’s the performance of the Canadian Markets (TSX Composite), 2018 year to date:
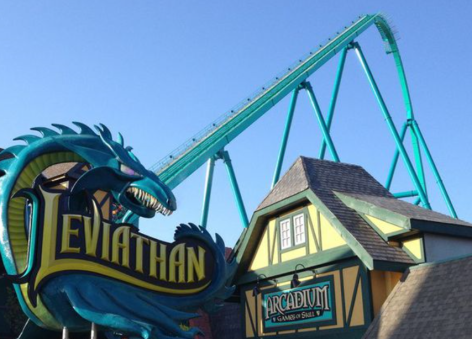
While that might look like a wild ride it’s all more of a kiddie coaster compared to the real thing such as the Leviathan at Canada’s Wonderland in Vaughn, Ontario. That coaster makes the 12 Scariest Rides according to tripsavvy.com.
Canadian markets are down by about 5% for the year. Once again: Kiddie Coaster. Serious stock market roller coaster rides will take you down by about 30%, 40%, even 50% or more. Yup, in a major correction you might have to watch your monies get cut in half if you’re in an all-stock portfolio. That 50% haircut has happened twice in the last 20 years. Many of us have been ‘lucky enough’ to invest through the two biggest market corrections since the Depression of the 1920s/1930s.
Those real roller coaster rides taught us some valuable lessons. Some investors did lose a lot of money through those corrections. Why? Because they invested outside of their risk tolerance level. They took on too much risk. They were not emotionally prepared to watch their investment portfolio drop by 40%, 50% or more. They perhaps needed some of those shock absorbers known as bonds.
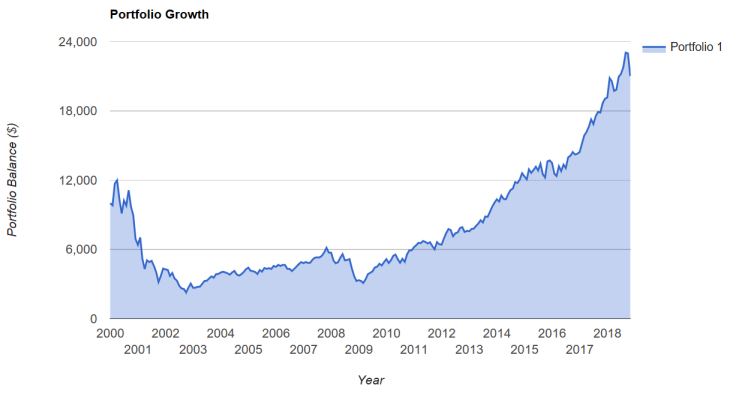
Those of us who were heavily invested in the tech-heavy indices such as the Nasdaq 100 (QQQ) or science and technology funds had to watch those investments drop by some 80%. Imagine watching every $100,000 fall to $20,000. Of course, many would jump off that roller coaster before hitting the bottom. Here’s a roller coaster ride that would make the list of Scariest Investment Rides. This is the QQQ ticker Nasdaq, chart courtesy of portfoliovisualizer.com. Full disclosure: I was ‘on’ that ride, and I don’t want to talk about it. Once again the stock market can teach us some expensive lessons.
We can see that investors who did hang on were eventually rewarded with positive returns, even more than a doubling of their initial investment. In fact, if an investor had been consistent and had kept investing on a regular schedule through those ups and downs they could have seen returns approaching 9% annual.
Buy. Hold. Add.
We might say that the risk assessment is deciding what roller coaster ride you can handle. Continue Reading…
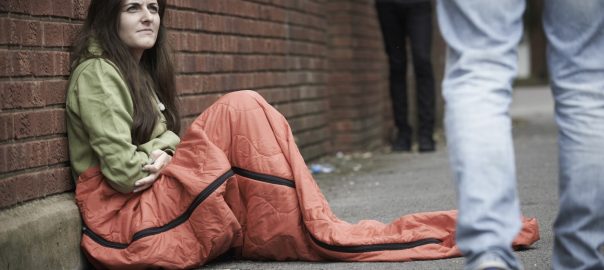
There was a gasp from the audience, when this photo of a homeless woman was shown at a talk I recently attended.
A new survey shows that almost half of women fear they will become a “bag lady” someday. They fear being financially desperate and living on the street.
What does “security” mean? It’s surprising how often the “bag lady fear” comes up. The #1 explanation is similar, but less severe:
Security: “Having enough so I never have to worry about money.”
Women want to know there will always be enough income for their family, for emergencies, and for the things that are important to their lifestyle. They want to focus on their life, their family and their friends and not have to constantly worry about whether they can afford it.
1.) Jennifer has $2 million in stock market investments. This is:
A. Very risky.
B. Financial security.
2.) Financial security is:
A. No debt and safe investments.
B. Large diversified portfolio.
3.) Who is more secure?
A. Mary has no debt.
B. Andrea has a $200,000 mortgage and $1 million in investments.
Whether you ever become financially secure depends a lot on your picture of financial security.
Most people who want security do exactly the opposite of what they need to do to get it. The biggest mistake most people make is to think they can be financially secure by paying off all debt and having safe investments, instead of investing wisely for long-term growth.
I call this the “Zero Plan.” You retire with zero debt, zero investments (nearly), and zero income (except a bit from the government). People who do this are actually making it hard for themselves to have the nest egg they will need to be secure.
The truth is, investing very little money and buying low-return investments means you will never build up much of a nest egg.
What does financial security look like? What I have learned from experience helping thousands of people become financially secure is this:
Real security comes from having a huge nest egg.
A large portfolio of equities (stock market investments) is financial security. That’s what security looks like. Continue Reading…
A growing number of Canadians plan on working longer because they haven’t saved enough for retirement. We see it at a macro-level; Canadian households owe a record $1.69 in debt for every dollar of disposable income, meanwhile the personal savings rate in Canada stands at a paltry 3.4 per cent.
There are plenty of reasons why we owe too much and save too little. The economy stinks, people get laid off, and salary increases are few and far between.
That said we’re often our own worst enemy when it comes to taking care of our finances. Here are eight bad habits that are killing your retirement dreams:
1.) You don’t watch your spending
It’s tough to stop a money leak when you have no clue where your money is going. Small daily purchases do add up (latte factor, anyone?), but these spending categories can bust your budget much faster – big grocery bills, dining out too frequently, filling your closet full of new clothes, one-click online shopping, and expensive hobbies, to name a few.
The solution: Write down everything you spend for three months. I guarantee you’ll have an ‘a-ha’ moment at best, and at worst discover something useful about your spending habits that you’d be willing to change.
The goal of course is to spend less than you earn. It’s one of the major tenets of personal finance.
2.) You want the newest ‘everything’
Fashion and décor trends change, technology constantly evolves. Staying ahead of the curve means shelling out big bucks for the latest and greatest products. The problem is your capacity to buy new things will never keep up with the pace of innovation and change. It’s an endless cycle.
The solution: Wait. Early adopters pay a hefty premium to be first. Look no further than televisions, where the latest innovations can initially go for between $5,000 and $10,000: 10 times what they’ll cost in a year or two.
The bigger issue is the psychological need to always have the latest gadget or be at the cutting edge. Ask yourself whom are you trying to impress.
3.) You have the constant need to upgrade
Fewer than half of all iPhone users hang onto their smartphones until they stop working or become obsolete. Most want to upgrade as soon as their provider allows it: usually every two years. A small percentage upgrades every year whenever a new model is released.
While spending a few hundred dollars on a new phone every other year might not hinder your retirement plans, it could be a symptom of a bigger problem. The constant need to upgrade your technology, your car, and even your home can be a big drain on your finances.
The solution: The same buy-and-hold approach that you take with your investments can also apply to your major purchases. The Globe and Mail’s Rob Carrick suggests a 10-year rule for homeowners to combat the odds of a housing crash and to save on transaction fees. Continue Reading…


 Posted By




 Posted By