Tag Archives: investing

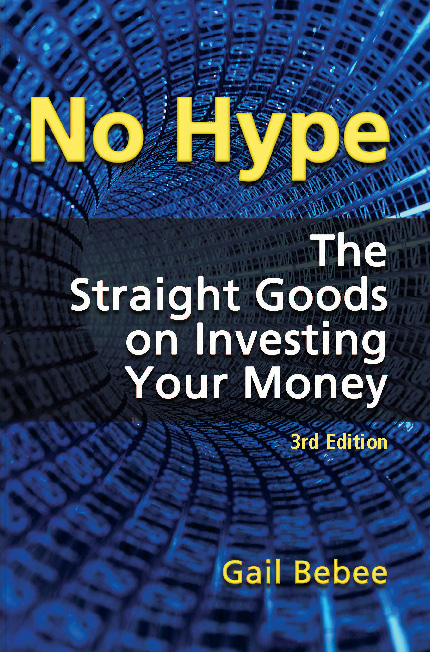
Gail Bebee releases third edition of No Hype book

NoHypeCoverToday’s Hub review is a bit unusual in that we’ve allowed an author to review her own book. I originally reviewed No Hype: The Straight Goods on Investing Your Money when it came out almost a decade ago and found it a useful addition to the genre, seeing as so many financial books these days are written by financial professionals.

It was refreshing to see a book written by a pure financial consumer like Gail, who like the rest of us has to sort the financial wheat from the chaff and has no real axe to grind. As she says on her web site, she’s an independent voice.

Hopefully we’ll review it in the more traditional manner over the coming weeks or months but in the meantime, it’s nice to know the book is still out there and has been revised.

Incidentally, and as noted in Saturday’s weekly wrap, Gail and I are among six speakers at The Financial Show in Mississauga later this month. Joining us will be Gordon Pape,  Pat Bolland, Jim Ruta and Scot Blythe. — Jonathan Chevreau

By Gail Bebee,

Special to the Financial Independence Hub
Gail_Bebee_Soft_editing_copy
Gail Bebee

When I set out in 2006 to write the original No Hype – The Straight Goods on Investing Your Money, my goal was to create a readable book that set down all the investing basics for Canadians, without a financial industry bias. It was born from my frustration at not finding such a book when I decided to take control of investing my money.

Thousands of books and two sold-out editions later, the students taking my Investment Planning night school course at Toronto District School Board still need a good reference, and retail investors are still looking for an objective, understandable book on all the investing basics written expressly for Canadians. Continue Reading…
ETFs: the next 25 years

vcm_s_kf_m160_160x141
Mark Yamada

By Mark Yamada, PUR Investing Inc.

Special to the Financial Independence Hub

From zero assets in 1989, to $79 billion in 2000, to $2.7 trillion into 2015, it has been quite a ride for global exchange-traded funds (ETFs). Few financial sectors have approached the over 25% compounded annual growth that ETFs have enjoyed. Yet many industry observers are disappointed.

ETFs’ value proposition is well known: diversification, professional management, shared expenses, all the benefits of mutual funds at a fraction of the price plus better transparency and continuous intraday trading. Yet ETFs represent only 12% of US and 6% of Canadian mutual fund assets (10% if US-traded ETFs owned by Canadians are included). If ETFs are so much better than mutual funds, why haven’t they replaced them by now?

Adopting new ideas Continue Reading…

A saving & spending plan you can live with

robb-engen
Robb Engen, Boomer & Echo

In many ways, Elizabeth Warren’s 2005 bestseller All Your Worth was ahead of its time. Warren, a relentless consumer advocate, eschews mindless frugality and focuses instead on finding the right balance so you always have enough to pay your bills, have some fun, and save for the future.

The author suggests a simple formula for spending your after-tax dollars on needs, wants, and savings:

  • Allocate 50 per cent to needs: These must-haves include housing, transportation, groceries, insurance, and clothes that you really need.
  • Spend 30 per cent on wants: Wants include cable television, clothing beyond the basics, restaurant meals, concert tickets, hobbies, etc.
  • Set aside 20 per cent for savings: This includes both short- and-long term savings, as well as debt repayment.

Warren encourages saving AND having fun rather than scrimping and pinching pennies on the things that make you happy. That means saving money on big-ticket items like housing and transportation – effectively reducing the amount you spend on needs to free up money to save for the future and spend on wants.

“If you can’t afford to have fun, you can’t afford your life.” 

When I applied this formula to my own spending I found the following breakdown:

Needs took up 53.5 per cent of our monthly budget, including the mortgage payment, property taxes, car payment, insurance (life, home, car), groceries, gas, utilities, cell phone, hair cuts, prescriptions, and clothing.

Related: What will it take for you to save more this year?

Wants made up just 18 per cent of our monthly spending, including cable and internet, restaurants, alcohol, children’s activities, hired cleaners (bi-weekly), credit card annual fees, subscriptions and memberships, gifts, summer vacation, and discretionary spending.

Finally, savings accounted for 28.5 per cent of our monthly budget. This amount includes repayment to our line of credit, contributions to my employer pension, RESP deposits, plus RRSP contributions.

Our car will be paid off late next year, which will free up $10,000 per year and reduce our “needs” allocation from 53.5 per cent down to about 44 per cent. Ideally, I’d prefer to shuffle that money over to savings and build up our TFSAs;  however, I’ll keep the idea of balance in mind and consider adding a few thousand dollars into our “wants” allocation.

Final thoughts

A balanced financial plan will ultimately lead to a happier and more fulfilling life.

Too many of us are living close to the edge financially because they’ve over-extended themselves on house and car payments and can’t afford to live.

Continue Reading…

Why do we invest?

IMG_3822
Aman Raina, Sage Investors

By Aman Raina, Sage Investors

Special to the Financial Independence Hub

One day as I was perusing the world wide web, I came across a posting about DRIP investments, which ran in the new blog by PWL Capital’s Justin Bender.

What caught my eye had nothing to do with DRIP investments but more about a comment made at the end of article that really got me thinking. It said:

“…Investors should be focusing their attention to more important investment decisions that are likely to have a bigger impact on overall success (such as savings rate, expenses, risk, fees, taxes, and behaviour)…” 

Make no mistake, these are important factors in developing your investment ideology or strategy. However, these elements just get you into the game of investing; on their own they are not going to guarantee you will be successful. Continue Reading…

How savers can cope with minuscule interest rates

Joe Atikian Saving Money Book
Joe Atikian

By Joe Atikian

Special to the Financial Independence Hub

Savers almost everywhere have nearly been beaten into submission by seemingly perpetual Zero Interest Rate Policies (ZIRP) imposed by central banks around the world.

The simple connection is that when interest rates are low, there is no incentive to save money. The flip side is that low interest rates make borrowing cheap, so people raise their debt load. So, is it still worthwhile to save when interest rates are low?

Continue Reading…