All posts by Financial Independence Hub

Are mutual funds headed for extinction?

James Avatar
James Gauthier, JustWealth

By James Gauthier, CIO, JustWealth

Special to the Financial Independence Hub

The advent of the mutual fund was one of the greatest innovations in the field of finance. Mutual funds created a practical means for common folks to invest in the markets which used to be only accessible by the wealthy.

The mechanics of how mutual funds operate have not changed much in the many decades since they have been around. Simply put, a group of investors pool their money together and form a unit trust where all investors get a pro rata ownership of what they contributed to the pool in the form of units (or shares). The pool is then used to buy a number of underlying investments such as stocks or bonds.

At the end of each day, all investments in the trust are priced and a Net Asset Value (or NAV) is determined by dividing the total value of the trust investments by the units outstanding. Investors who want to purchase shares of the trust may do so based on the NAV established at the end of each day.

Mutual funds have been available to Canadians for over 80 years, and now number more than 15,000 worth well over $1 trillion. Companies or individuals who sell mutual funds like to promote the benefits of mutual funds: Continue Reading…

Employee Savings Plans: why say no to free money from your employer?

DSC_0371[2] copy
Josh Miszk
The September long weekend is upon us and, for many, it’s the last chance to spend some quality family time before the transition back to school and work.

The post-Labour Day shift into a more productive mindset offers a good time to review your Employee Savings Plan (ESP), a benefit that can be a great way to save money but can also add some risks.

An ESP is a program set up by an employer that allows employees to contribute a portion of their income into an investment the employer has provided.  In some cases, the employer may also match all or a portion of the contribution made by the employee.

Benefits: free money!

By participating in your ESP you’re basically getting free money.  Whether an employer matches part or all of your contributions, you will be hard pressed to find any other investment out there that provides immediate returns.  Say, for example, that your employer will match 50% of your contributions, up to 6% of your salary (a typical scenario).  All growth and other earnings aside, your investment immediately grows by 50% and your 6% turns to 9%.

Continue Reading…

How to maximize Credit Card loyalty rewards programs

Frank Psoras

By Frank Psoras, TD Canada Trust

Special to the Financial Independence Hub

Credit cards can offer many benefits to achieve your financial goals. And with most credit cards today, the more you swipe, insert or tap, the more opportunities you have to earn and redeem loyalty rewards.

According to a recent TD survey, nearly three-quarters (72 per cent) of Canadian adults carry at least one card that offers a rewards program, with most cardholders (82 per cent) saying it’s one of the top factors when choosing a credit card.

North Americans are among the most rewards-savvy consumers in the world; they’re always looking for better ways to get the most from their rewards programs to reach their goals faster. That is why it’s no surprise our survey also shows that almost half (49 per cent) of Canadians are willing to change where they shop to earn and redeem points faster. But remember to pay your balance on time and in full to avoid incurring interest charges on purchases. Continue Reading…

8 reasons you may get turned down for Life Insurance

Depositphotos_111789972_s-2015By Chantal Marr, LSM Insurance

Special to the Financial Independence Hub

For some people, getting the life insurance coverage they need is not easy. Factors such as health conditions and lifestyle choices play an important role in determining whether or not a company sees you as a qualified candidate. Lying on your application to hide potentially damaging facts won’t help. It might get you a great policy at prime rates, but when it comes down to filing a claim, the insurance company will discover the truth, and your claim will be denied.

We reached out to Gisèle Babineau, Chief Underwriter with Assumption Life, for the most common reasons a person may be denied life insurance coverage. The reasons for being declined vary from one company to another, and there is also a significant gap between a re-insurer and insurer because many insurers do not shop their declines with their re-insurers. However, in general, these are the most common reasons why an application may not be approved.

Medical Reasons

A medical condition under investigation

If you have some symptoms of an illness or disease, but all of the results aren’t in yet, your medical condition is considered under or pending investigation. During this period, you are considered a high risk applicant and the insurance company may deny coverage or delay their decision. Once you are cleared of any possible long-term illness or disease, the company will probably approve your application or ask you to re-apply with the new doctor’s report.

High grade cancers

Cancer can develop in any part of the body. Where it occurs determines its type. For example, lung cancer develops in the lungs. All types begin as a tumor and how the affected tissue looks under a microscope indicates how quickly the tumor cells will grow and spread. Based on the appearance and other factors, doctors can assign a numerical “grade.”

The grade of the cancer is not the same as the stage. Stages refer to the size or extent of spread. Malignant tumors are very low grade and almost always can be completely removed. High grade cancers tend to grow quickly and spread rapidly, putting your life at a higher risk.

Nervous disorders Continue Reading…

How to use a credit card strategically for emergency expenses

Emergency FundBy Alyssa Furtado, RateHub.ca

Special to the Financial Independence Hub

You can’t plan for something you don’t know is coming.

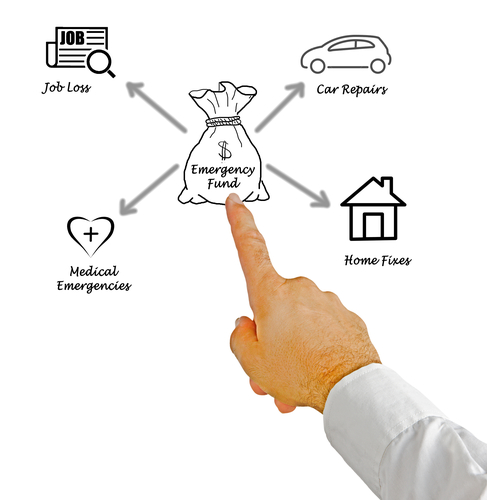
Accidents and emergencies are inevitable and a financial cost is often attached to these surprise incidents. So what do you do when you find yourself with an unexpected emergency expense? One option is to use balance transfer credit cards.

Balance transfer credit cards are great tools to help you pay off your debts sooner. They offer a low interest rate (sometimes 0%) for any debts you transfer to the card for a limited period of time. By minimizing interest costs, the money you put towards your debt will directly pay off the amount owing and not go towards fees. While there can be costs associated to balance transfers — like a fee of 1% to 5% for transferring a balance or an annual fee — the interest savings can outweigh the cost of the fees.

So how can you strategically use a balance transfer credit card for emergency expenses? Charge whatever emergency expense you make to a card you already have, immediately apply for a balance transfer card, and quickly transfer over the balance to the new credit card.

There are considerations you need to know before applying for a balance transfer credit card, such as: Continue Reading…