All posts by Financial Independence Hub

Stop believing real estate has magical investment powers

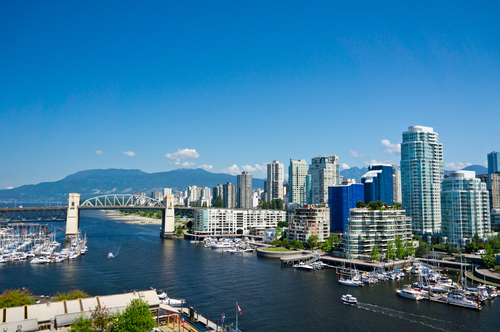
Beautiful view of Vancouver, British Columbia, Canada
Expensive Vancouver, BC

By Steve Lowrie, Lowrie Financial

Special to the Financial Independence Hub

If you found yourself on the high seas, and the captain and crew were battening down the hatches, what would you do? Depending on how fast they were scrambling, you might at least make sure your life preserver was within reach.

If the Canadian real estate market were an ocean liner, recent government words and deeds have sent some pretty solid warning shots across the bow – especially for properties in the Greater Toronto and Vancouver regions. Real estate investors who may have forgotten the essential rules of self-preservation would be wise to consider the following:

In a June announcement, Bank of Canada Governor Stephen Poloz warned: “The pace of house price increases in Toronto, and especially Vancouver, is unlikely to be sustained, given the underlying fundamentals.”

Several provincial governments have been looking for ways to manage their real estate markets. For example, this July Globe and Mail article noted that British Columbia was trying to “cool the Vancouver market” by adding a 15 per cent transfer tax on property purchases made by international buyers. Continue Reading…
Is RV Traveling a sound Retirement Strategy?

rv-925610_640
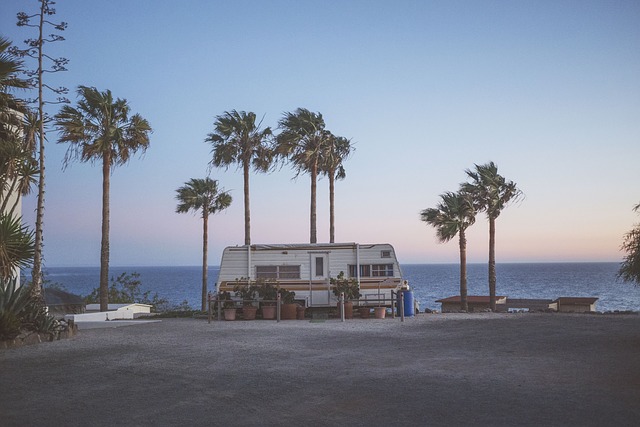
Living the RV dream. Photo courtesy Pixabay.com

By Barney Whistance

Special to the Financial Independence Hub

At some point we’ve all daydreamed about what our retirement might look like. For some, a cabin in the woods might be their dream life. Others may want a condo near the beach or high-rise apartment in the city. Many daydreams also include travel, both in and outside the U.S.

Ample Hollywood movies about the joys and headaches of the retirement life have given nods to the recreational vehicle (RV) retirement lifestyle as well. From ex-CIA man Jack Byrnes’ sleek black Fleetwood RV in Meet the Fockers, to David and Linda Howard’s homier Winnebago in the movie Lost in America, RV living may represent a luxury life of leisure for many Americans.

One former co-worker of mine, shortly after his retirement, sold his home to buy a fancy new RV. While I was able to meet him at his retirement party and do a short quiz on his reasoning, the decision never quite added up for me. I decided to do some additional research to determine if RV-living was a sound and viable financial decision for my own retirement.

Full-time RVers, also known as full-timers, are people who live, work, and play in their RVs. Often they plan their lives and moves well in advance, but they’re also known to pick up and go on a whim, or to follow the weather on a seasonal basis.

However, there are a few considerations when contemplating the full-time RV life. Here’s a breakdown of points to ponder while deciding whether it’s the best lifestyle for your needs.

Finances

RVs can be purchased in a wide price range – anywhere from $3,000 to $3 million – which makes them perfect for any budget. Continue Reading…

Make the Family Cottage less Taxing this year

Cottage On The Carpenter Lake, Canada

By Fraser Willson

Special to the Financial Independence Hub

As the days of summer dwindle to a precious few, the last few weekends at the family seem especially poignant now. And while those thoughts may warm you up a bit, you don’t want to be left out in the cold if you’re not aware of the financial implications when you sell the family retreat or if you transfer ownership to your children this year.

Unlike with your home, transferring ownership of the family cottage to anyone other than your spouse may trigger a taxable capital gain on the appreciation in value during your ownership. You may want to consider leaving the property to your spouse. Doing this helps defer the tax bill until the property is sold or passed on to future generations.

In addition, there are a number of strategies that you can undertake to help reduce and potentially avoid the capital gains tax, including:

Selling and taking back a mortgage

If you decide to sell the cottage to your children, consider taking back a mortgage by offering your children a mortgage loan as payment for the purchase price. The capital gain can be spread over a period of up to five years. And you can forgive the mortgage in your will so your children will own the cottage without debt or paying taxes.

Transferring ownership while you’re alive

Transferring ownership of the cottage to a trust that designates your children as beneficiaries will trigger an immediate capital gain. But from that point on, your heirs are responsible for taxable gains. They won’t pay those taxes until they sell the property or transfer ownership.

Declaring the cottage as your principal residence

You can have only one principal residence for tax purposes. So if your cottage has gone up in value more than your home, consider designating the cottage as your principal residence, which isn’t subject to capital gains tax.

Buying life insurance

Family members can use the tax-free proceeds from a life insurance policy to help pay capital gains taxes on your cottage when you leave it as part of your estate.

If you plan to sell or transfer ownership of your family cottage this year, make sure your finances align with your goals. Doing so can help ensure you stay on track to reach them.

Continue Reading…

What is Mortgage Insurance?

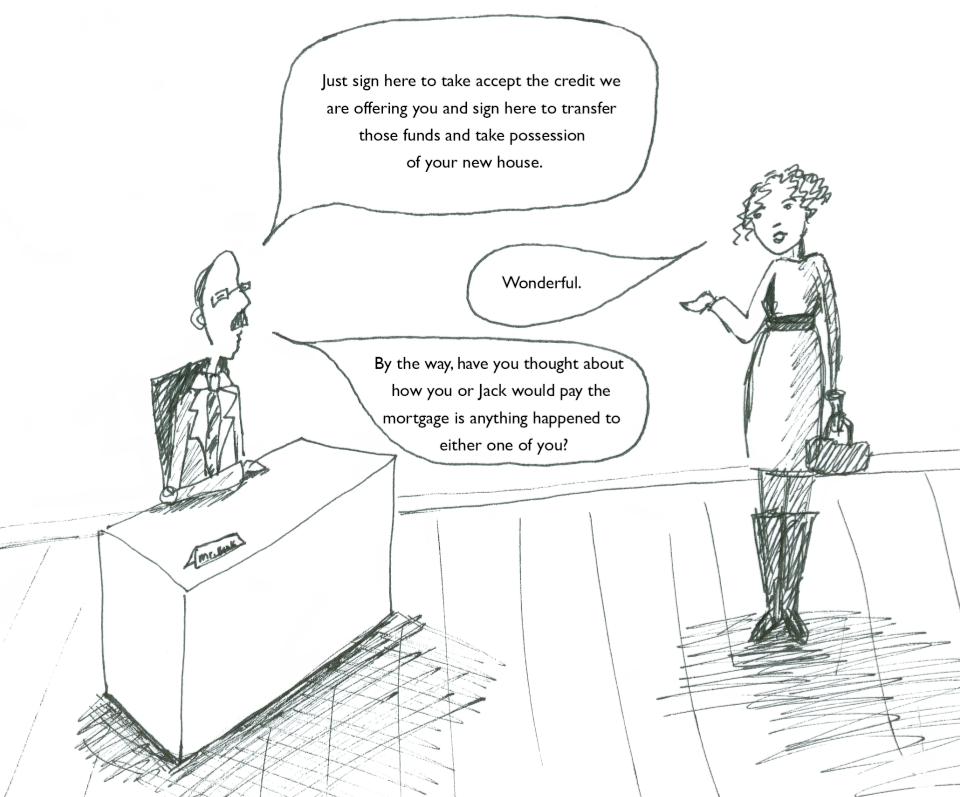
mortgage-insurance-cartoon
Cartoon courtesy of LSM Insurance

By Chantal Marr, LSM Insurance

Special to the Financial Independence Hub

Sounds great just lying there on paper, doesn’t it?

Really solid.

The underlying concept of mortgage insurance is that if you die or are incapacitated mortgage insurance will pay off the rest of your mortgage. But be careful: Mortgage Insurance is the most dangerous financial product out there.

Mortgage insurance is the one financial product that declines in value as you continue to pay. Therefore each year you are getting less and less value for your premium.

Why Math is Important

Renting vs. Owning

Let’s start with your house. When you take a mortgage out on your house, it’s a very bad deal to start with. You are just paying interest on the value of the house and in most cases the interest far exceeds the cost of renting the same property.

Here’s an example based on a $500,000 20-year mortgage at 6% on a $600,000 house. We’ll assume rent inflation of 4%/year:

Year 2010: Mortgage payment $3,560/month. Rent: $2,500.

You are leaving over $1,000 in your pocket per month in ready money. That’s a lot of restaurants and vacations twelve months a year.

But let’s take it ten years later: Continue Reading…

The critical role of planning for Cash Flow

ennio_4-1500x1058
Ennio Longo

By  Ennio Longo

Special to the Financial Independence Hub

Are you like so many Canadians? You have a good paying job, are in a two-income household, own a home and yet you run out money before you run out of month?

The majority of Canadians are spending more than they make.   If this sounds like you, you’re not alone.  We are trying to put some money aside for the future as we have been told we should, but we also want to enjoy today; take that trip, get a new car, renovate the kitchen. We cannot just live for tomorrow.  WE WANT TO ENJOY TODAY.

The reason we have this shared experience is that we never went to school to learn how to “handle” our finances or how to manage our CASH FLOW. With so many different companies from financial institutions to consumer goods vying for our money, managing our cash flow on a monthly basis can be very difficult for many people; myself included.

Certified Cash Flow Specialist

With a four-year business degree and a CFP (Certified Financial Planner) and CLU (Chartered Life Underwriter), one would think that I would have received a formal education in cash flow planning as well, but I didn’t; at least not until I received an actual formal education in cash flow planning and became a CCS (Certified Cash Flow Specialist). Continue Reading…