Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

Financial Freedom is the “New and Improved” Retirement

Below is a guest blog by financial educator, Chartered Professional Accountant and money coach Patricia Gass, who tweeted me that “You inspired this” and granted permission to post on the Hub.  I do that below with only slight edits and formatting tweaks because I can use all the help I can get at this stage, but please check out the actual blog at Patricia’s site, Let’s Talk About Money. She is @gasspatricia on Twitter.

Let us indeed talk about money! Naturally, I would have preferred that the title were “Findependence is the ‘New and Improved’ Retirement,” but we’ll have to go with what Patricia actually wrote. We can however agree that we both dislike the word Retirement. We suggested during Launch week that the word Retirement should itself be retired!

And that’s how Patricia begins her blog:

By Patricia Gass, CPA, CA
image
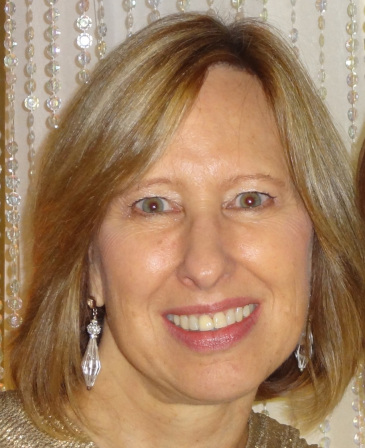
Patricia Gass

I’ve always hated the word RETIREMENT.

For me, this term comes with unpleasant images of failing health, unwanted naps and uninspiring leisure activities without purpose. Ouch! Maybe I’m too sensitive? Maybe it’s because my father lived only a year of his retirement “dream” before his sudden death. And for him, retirement was something he had longed for for quite some time. A hard-earned reward for being a productive and valuable employee for 45 years.

When I voluntarily left my corporate job several years ago, I didn’t know what to call myself. I tried the word “retired” but I would get strange and curious looks from people. “What do you do all day? You look too young to be retired” many would say. While I suppose the latter was meant as a compliment, it still made me feel uncomfortable. Less valuable to society. Idle and no longer needed. I must work on my mindset!

A new life chapter

But here’s the thing; I was happy … VERY happy! I left my job because I had a choice (financially speaking). My job was no longer giving me the satisfaction and fulfillment that I desired. I couldn’t imagine 5, 10 or even one more year of the same stuff. Achieving financial freedom (or close to it) opened up a whole new and exciting chapter of my life. I couldn’t wait to get started!

While I no longer needed to search for paid employment (although a little income is always nice), I knew I wanted to do something meaningful. Does paid employment mean greater value for society? The reality was that I wanted and needed time to figure out what meaningful meant to me. Little did I realize that the opportunity to help people, strengthen relationships, give back or volunteer would give me greater satisfaction than a higher salary!

The Gift of Time

From my own experience, the gift of time is a wonderful thing. That’s what you get when you achieve financial freedom. Money no longer becomes a big factor in your decisions. The world is full of endless possibilities … so many things to see, do, learn, explore and enjoy. Some need money, but not all do.

Financial freedom is a worthwhile goal at any age. I admire the many people today who are doing what it takes to make it happen. Especially the thirty and forty somethings that want it sooner,  not later. Maybe one day, it will become fashionable to build wealth rather than spend it?

I think my husband (who is also happily “retired” and proud of it) said it best …

Retirement (aka financial freedom) is about doing more of what you love and less of what you hate.

I couldn’t agree more.

Thanks to Jon Chevreau and his new Financial Independence Hub (worth a visit!) for the inspiration for today’s post.

Proud founder of the blog, Let’s Talk About Money, Patricia Gass, CPA, CA, provides personal finance coaching and education to improve your money skills. Follow her on linkedin, twitter or pinterest.

 

GIS for the wealthy? TFSA is key so maximize it while you still can

fredvettese
Fred Vettese, Morneau Shepell

My latest MoneySense blog is a followup to an interesting piece by actuary Fred Vettese about the curious phenomenon of wealthy couples being able to contort their finances between ages 67 and 70, by which they can receive the Guaranteed Income Supplement or GIS.

Considering that the GIS is aimed at seniors with no savings and minimal pensions, the idea of putting such a gambit in place offends some, although as the blog points out, most of the readers who contacted Vettese just wanted more details on how they could benefit from the strategy themselves.

Hypothetical now but expect eventual crackdown

I’ll be doing more on this but it seems that the strategy is not so much likely to become widespread as it is an example of the inherent contradictions and unintended consequences that accompany such a proliferation of government programs. This one is based on suspending most sources of income from 67 to 70, except Old Age Security (OAS) and the GIS, plus taking tax-free income from the Tax Free Savings Account or TFSA. TFSA withdrawals are neither taxed nor trigger clawbacks of OAS and GIS. In fact, it’s arguable TFSAs were created expressly to motivate low-income workers to save without being penalized by the taxes and clawbacks that accompany RRSPs and employer-sponsored pensions plans.

Will Ottawa move to crack down on this theoretical loophole? Who knows but the TFSA was the Conservative administration’s creation and if they lose the next election, it’s quite possible the Liberals or NDP would move to tweak either the TFSA rules or the GIS qualifying rules. Best advice? Max out the TFSA while you still can!

My road to Findependence: Guest Blog by Sheryl Smolkin

sherylholdingrufus.
Sheryl Smolkin and Rufus

By Sheryl Smolkin

Special to The Financial Independence Hub 

Almost 10 years ago, at age 54, I took early retirement from my job as a pension lawyer and Canadian research director of an international benefits consulting company. I locked the door of my downtown office for the last time on a Friday; on the following Monday I started my new career as editor-in-chief of an industry magazine.

My new job paid only about one third of what I earned before, but I left with a defined benefit pension (albeit reduced by about 30%) and retiree health benefits so I was prepared to take the risk in order to try something new.

With the benefit of hindsight, I can say it was a totally audacious move. I knew how to write peer-reviewed, factual client publications but didn’t have a clue about the economics of running a trade magazine or how to turn a bunch of disparate articles into a cohesive product.

Hard work but fun, and I learned fast Continue Reading…

Happy Money vs. Findependence

text happy moneyWhile more and more financial pundits seem more inclined to retire the term Retirement, it’s by no means clear what the preferred term should be. Obviously I’m biased since I’ve invested six years in the term “Findependence,” culminating in this web site, the Financial Independence Hub. Over the weekend, we linked to Roger Wohlner’s site and his reposting of a one-year-old posting by me arguing the case for Financial Independence over Retirement. And last week, we posted financial planner Jenya Rose’s piece making the case for Happy Money over Findependence.
I then responded to that piece here at the Hub and now Jenya has reposted that piece over at her own site. She announced this on Twitter on Monday, with this gracious tweet:
responds nimbly to my post that argued is moot if you have Happy Income Touché! :)
Love that use of the hashtag in front of #Findependence!

Guerrilla Frugality & Froogers

LunchEarlier this fall, I gave a short interview to robo-adviser/light advice firm NestWealth.com about financial independence, ETFs and the term I often use in Findependence Day: guerrilla frugality. You can find it here.

I first used the term “guerrilla frugality” in a personal finance column in the Financial Post. The idea was that early retirement (or findependence) requires a sort of super-frugality.

Guerrilla warfare and guerrilla marketing are both phrases already in the public lexicon. I reasoned that as consumers, we’re constantly besieged by the “guerrilla marketing” efforts of well-heeled advertisers and stealth marketers. So in order to spend less than you earn consistently, in order to save and invest the difference, you need to become super-frugal and practice “guerrilla frugality.”  (Note, it’s not “gorilla,” which some readers have mistakenly used in their correspondence with me. Gorilla is the ape!)

In the book, we talk (in war terms) of donning the battle fatigues of the “Frugality Guerrilla,” which we shortened to “Frooger.”

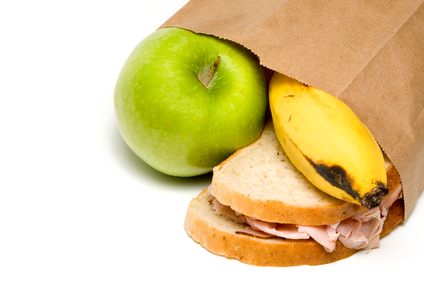
I’ve used the photo of a brown-bag lunch to illustrate this blog, since the character in the novel starts to brown bag it once he decides he wants to be “findependent” by age 50. In his guest post here at the Hub last week, millennial Sean Cooper also describes how he “brown bagged” it (among many other frugal endeavours) to accelerate his mortgage pay down campaign.

Formal definitions in the Glossary of the new ebooks

In the glossary to two new e-books published earlier this month, we offer these two definitions:

Guerrilla Frugality: A term invented by the author to describe the “warlike” mentality of being super-frugal in order to resist the strong consumption messages of America’s markets and advertisers.

Frooger (Frugality Guerrilla): An invented term in this book describing anyone highly committed to being frugal and saving money.

US fee-only financial planner Sheryl Garrett used the term “frooger” in both her foreword to the US edition of Findependence Day, published in 2013, as well as the new US ebook. Because it appears near the front, you can read Sheryl’s foreword free by clicking on the “Look Inside” feature on either the full book or the abbreviated e-book edition.