Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

7 ways Investors are capitalizing on Low Interest Rates


What is one way you are capitalizing on low-interest rates?

To help you take advantage of low interest rates, we asked seven finance experts and business leaders this question for their best insights. From refinancing existing debts to looking into preferred securities, there are several suggestions that may help you benefit from the low interest rates in the current market. 

Here are seven tips for capitalizing on low-interest rates:   

  • Work with a Finance Broker
  • Get into Commercial Real Estate
  • Refinance Existing Debts
  • Consider FHA Loans
  • Maximize your Return on Investment
  • Set up a Line of Credit
  • Look into Preferred Securities 

Work with a Finance Broker

As a commercial finance broker, we work with our clients to make sure they can take advantage of low interest rates based on a thorough financial analysis of their company. By analyzing your credit and financial health, we act as an advisor to clients for the best financing options available. We also build leases and loans that are competitively priced and intelligently structured for an optimal plan that works for the client and incorporates the best rates possible.  — Carey Wilbur, Charter Capital

Get into Commercial Real Estate 

If you’ve been wondering whether or not to buy commercial real estate, I think it is time to take advantage of the “perfect storm” of low borrowing rates. You’ll save a lot of money on interest payments long term. Now is the perfect moment to acquire real estate for assets as an income-generating resource. So whether you need a warehouse, brick-and-mortar store outlet, or even commercial property to place on the rental market, this might be one of the best times to get in the market. Renting your commercial property will provide you with consistent income, and you might also benefit from tax advantages on depreciation and capital gains, to name a few. — Allan J. Switalski, AVANA Capital

Refinance Existing Debts 

I suggest you consider refinancing your small business loan, mortgage, or student debt, which entails paying off your existing loan by taking out a new one. The new loan will have a reduced interest rate. Ideally, opt for a fixed-rate loan to lock in the lower rate. To qualify, you’ll need strong credit, but if you do, you’ll save a lot of money on interest fees. — Sundip Patel, LendThrive

Consider FHA Loans

FHA Loans are a great low-interest lending option that is offered by the Federal Housing Administration. These loans are intended to increase homeownership access to those who may not have the ideal credit score required by other financing options. This can be a great option for prospective real estate investors. — Than Merrill, FortuneBuilders

Maximize your Return on Investment

When interest rates are low, borrowing is much more convenient. Continue Reading…
Helping entrepreneurs thrive as pandemic-driven small business trends stay for the long haul

Image RBC/iStock

By Don Ludlow, Vice President, Small Business, Strategy & Partnerships and Business Financial Services, RBC

(Sponsor content)

While the COVID-19 pandemic brought significant challenges and uncertainty to small businesses across Canada, it also became a catalyst for many new business practices.

In many ways, it also accelerated the need for small business owners to adapt to other trends and consumer expectations that were steadily on the rise over the last several years.

To help us better understand these trends, RBC recently conducted research to gauge the types of experiences and expectations Canadians have when interacting with small businesses in the coming year as we continue to navigate the ongoing pandemic and journey toward economic recovery.

The survey revealed three important trends that will continue to impact small businesses in the year ahead:

  1. First, we’ll see a growing demand for digital payment and engagement options, whether customers are connecting with small businesses in person or online.

While eCommerce and digital solutions were already on the rise pre-pandemic, they became pandemic necessities as businesses adapted to health and safety measures.

Now, more Canadians are expecting this to be the new way of doing business, with two-thirds (64%) of Canadians saying that partnering with digital platforms to make products and services more accessible will be important post-pandemic, especially among millennials (72%).

Meanwhile, four in five Canadians polled say that they would like to continue to shop online at small businesses, even after the economy is fully reopened, and 72% say that increased social media presence helped them become more aware of what small and local businesses had to offer.

  1. Small businesses that focus on prioritizing employee wellness and overall customer health & safety will be greatly valued by Canadians.

The majority of Canadian respondents in our poll said providing more wellness and mental health benefits and resources to employees will be important going forward (87%).

They also expect heightened hygiene standards to continue post-pandemic (99%) and would like businesses to continue offering flexible curbside pickup and delivery services (78%).

As a result, offering employee benefits, resources and safety protocols that meet these expectations will be critical differentiators for small businesses looking to attract and retain talent and customers.  

  1. We’ll continue to see a rise in socially and locally conscious consumers – especially among millennials and Gen Z.

Supporting small, local, and diversity-focused businesses is here to stay post-pandemic. According to our research, the majority of Canadians (77%) polled plan to spend more at small, local retail stores, restaurants and businesses to support their recovery than they did before the pandemic.

Many respondents also said they are actively seeking out and supporting 2SLGBTQ+* (52%) and BIPOC **(61%)-owned businesses, products and services. These numbers are greater among Millennials and Gen Z, indicating the next generation of consumers will increasingly purchase through a diversity-focused lens.

Being aware of these trends, and adapting business strategies and operational practices to address evolving consumer expectations will be important to the success of small business owners in the next year.

In light of these insights, we have three tips for entrepreneurs to consider as part of their 2022 playbook for success. Continue Reading…

Retired Money: What is the Rule of 30?

ECW Press

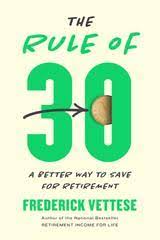
My latest MoneySense Retired Money column reviews actuary Fred Vettese’s new retirement book: The Rule of 30 (ECW Press).

You can find the full column by clicking on the highlighted headline here: What’s the Rule of 30? And what does it have to do with Income and Retirement?

Never heard of the Rule of 30? Neither had I, nor Fred himself until he invented it.

In a nutshell, it’s a rule of thumb financial planners can use to guestimate how much young couples starting off on their financial journeys need to save for Retirement. Rather than flatly state something like save 10 or 12 or 15% of your gross (pre tax) income each and every year, the Rule of 30 sees retirement saving as occurring in tandem to Daycare and Mortgage Repayment.

From the get go Vettese suggests young couples allocate 30% of their gross or after-tax income to the three expenses of Retirement saving, Daycare and Mortgage paydown. However, in the early years they may save less in order to handle Daycare and the mortgage. Since daycare expenses usually fall away after a few years (depending on how many children a couple has), once it has gone you can ramp up the mortgage paydown and/or retirement savings. And if – ideally five years before retirement – the home mortgage is paid off, then couples can kick their retirement saving into overdrive by allocating a full 30% or more solely to building their nest egg.

Wealthy Barber style fictional format

In a departure from his previous books — Retirement Income for Life and The Essential Retirement Guide among them — The Rule of 30 uses the tried-and-true quasi-fictional “story” pioneered by David Chilton’s The Wealthy Barber. That road has been ploughed by many subsequent financial authors, including Yours Truly in Findependence Day. 

As Vettese told me in an interview mentioned in the column, he didn’t plan it that way initially. “I did a first chapter using that format and then realized it’s a lot easier to write this way and it’s not as dry: it’s somewhat easier to read and to write. When you get a problem, a character chimes in.”

The main characters are a couple, X and Y, and — conveniently — the neighbour next door who happens to be an actuary with time on his hands.

No doubt it would have worked either way, but Vettese’s dialogs are readable enough and he even works in a minor subplot involving the actuary and his estranged daughter.

One of the people acknowledged by Vettese at the back of the book is fellow actuary and retiree Malcolm Hamilton. In an email, Hamilton said “I have always believed that middle class Canadians who marry, buy a house and have children cannot reasonably expect to save much for retirement until after the age of 45,” Hamilton told me via email, “There just isn’t enough income to cover mortgage payments, the cost of raising children and Canada’s heavy tax burden (with child care expenses and mortgage payments generally non deductible for those with incomes that suggest they need to save.”

All in all, a useful rule of thumb for young couples setting out on family formation, home ownership and ultimately Retirement. Note that Vettese says that once you are within five years of your hoped-for Retirement age, you should strive to be mortgage free. And around 55, you should move from the Rule of 30 to using a Retirement calculator like the free one Vettese developed for Morneau Shepell: PERC, or the Personal Enhanced Retirement Calculator.

PS: I am now Investing Editor at Large for MoneySense

Alert readers who got to the bottom of the column and read the author blurb will see a slight change in my status at MoneySense. In addition to writing the monthly Retired Money column I am now also the Investing Editor at Large for the site, a fact that’s also divulged in my Twitter profile.  I will continue to publish Hub blogs every business day: so much for Retirement!


A look at BMO Asset Allocation ETFs

This article has been sponsored by BMO Canada. All opinions are my own.

I’m on record to say that the vast majority of self-directed investors should simply use a single asset allocation ETF to build their investment portfolios.

What’s not to like about asset allocation ETFs? Investors get a low cost, risk appropriate, globally diversified portfolio in one easy to use product. It’s a fresh take on an old idea – the global balanced mutual fund – updated for the 2020’s using low-cost ETFs.

Investors don’t even have to worry about rebalancing their portfolio when they add or withdraw money, or when markets move up and down. Asset allocation ETFs automatically rebalance themselves regularly to maintain their original target asset mix.

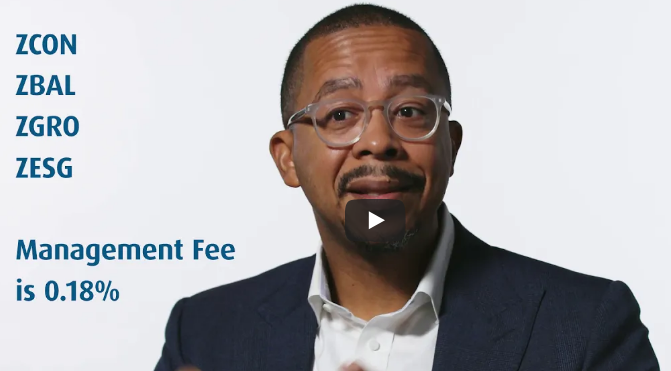
This article looks at BMO’s line-up of asset allocation ETFs, which include a conservative (ZCON: 40/60), balanced (ZBAL: 60/40), growth (ZGRO: 80/20), and balanced ESG (ZESG: 60/40) option.

For a YouTube video about these ETFs, click here.

These BMO asset allocation ETFs are available for self-directed investors to purchase through their online brokerage account. Notably, these ETFs can be traded commission-free through BMO InvestorLine and Wealthsimple Trade.

What’s inside BMO’s Asset Allocation ETFs?

Launched in February 2019, BMO’s core asset allocation ETFs are made up of seven underlying ETFs representing various asset classes and geographic regions.

On the equity side we have:

  • ZCN – BMO S&P/TSX Capped Composite Index ETF
  • ZSP – BMO S&P 500 Index ETF
  • ZEA – BMO MSCI EAFE Index ETF
  • ZEM – BMO MSCI Emerging Markets Index ETF

While on the fixed income side we have:

  • ZAG – BMO Aggregate Bond Index ETF
  • ZGB – BMO Government Bond Index ETF
  • ZMU – BMO Mid-Term US IG Corp Bond Hedged to CAD Index ETF

Altogether these seven ETFs represent nearly 5,000 individual stock and bond holdings from around the world.

In terms of geographic equity allocation, the BMO asset allocation ETFs hold 25% in Canadian stocks, 25% in international stocks, 40% to 41.25% in US stocks, and 8.75% to 10% in emerging market stocks.

BMO reviews their portfolios quarterly and will rebalance any fund that is more or less than 2.5% off from its target weight. In reality, these funds are rebalanced regularly with new cashflows from new investors.

BMO’s Balanced ESG ETF (ZESG) is made up of six underlying ETFs, including:

  • ESGY – BMO MSCI USA ESG Leaders Index ETF
  • ZGB – BMO Government Bond Index ETF
  • ESGA – BMO MSCI Canada ESG Leaders Index ETF
  • ESGE – BMO MSCI EAFE ESG Leaders Index ETF
  • ESGB – BMO ESG Corporate Bond Index ETF
  • ESGF – BMO ESG US Corporate Bond Hedged To CAD Index ETF

The management expense ratio for each of the BMO asset allocation ETFs is 0.20%. There is no duplication of fees or additional charges for the underlying ETFs. Continue Reading…

Why would anyone own bonds now?


By Mark Seed, myownadvisor

Special to the Financial Independence Hub

Many investors have been saying for years that rates can only go up from here, rates can only go one direction, rates will eventually go up. Will they? This begs a question I get from readers from time to time given bonds pay such lousy interest:

Why would anyone own bonds now?

Today’s post shares a few reasons to own bonds including some counter-arguments why I don’t own any – at least right now.

Why own bonds?

Personally, I believe the main role of fixed income in your portfolio is essentially safety – not the investment returns and certainly not the cash flow needs. In other words, if all else fails per se, if/when stocks crash, then bonds should historically speaking offer a flight to safety for preserving principal.

So, they are there for diversification purposes.

As Andrew Hallam, a Millionaire Teacher has so kindly put it over the years: when stocks fall hard, bonds act like parachutes for your portfolio. Bonds might not always rise when the equity markets drop. But broad bond market indexes don’t crash like stocks do.

Is that enough to own bonds in your portfolio? Maybe.

Here are a few reasons to own bonds in no particular order.

1. Bonds as a hedge for stock market volatility.

Call them parachutes or anchors or use any other metaphor you wish but bonds tend to do their jobs when stock markets tank. More importantly maybe, they provide a psychological edge to avoid tinkering with your portfolio and selling any stocks/equities when stock markets correct.

Many investors, dare I say most investors (?), have a hard time with market volatility. I’m certainly not immune to it. The ups and downs, especially the big market downs, can be gut-wrenching to live through. Owning bonds in your portfolio can help bring the overall portfolio volatility down a few notches through prudent asset allocation. It is however not always necessary to own bonds.

When you own bonds, my experience has been for the last 20+ years you are trading away long-term, more positive, generous equity returns for accepting less risk and less long-term returns.

If you don’t want to take my word for it, check out this page courtesy of Vanguard when it comes to long-term returns. Check out the “worst year” stats as well.

Why would anyone own bonds - bias to bonds Vanguard Canada

Sure, a 40/60 stock/bond portfolio has hardly done poorly for the last century. But overall, you are absolutely giving up (historically speaking) returns on the table when you own more fixed income in your portfolio. Will the future be the same?

Why would anyone own bonds - bias to stocks Vanguard Canada

Personally, I’ve tried to learn to live with stocks as much as possible for as long as possible. Depending on your goals, taking into account long-term potential reward against short-term price fluctuations, some investors may not be comfortable with a 100% equity or near-equity portfolio. That’s A-OK. If that’s your case, some bonds in your asset accumulation years could be right for you.

2. Bonds can be used to rebalance your portfolio. 

Even though I’m not a huge fan of bonds myself, this might be one of the most compelling reasons to own bonds at any age.

When the stock market sells off, that’s ideally the time you want to dive in and buy your stocks on sale. However, unless you are very comfortable with leveraged investing – you need money to buy such stocks on sale. That can come from cash savings for sure but for many investors, that can also come from bonds within your portfolio.

Mind you, some levels of diversification don’t work very well if you don’t have any asset allocation targets in mind. The process of rebalancing is a systematic way to buy low and sell high; sell your bonds when markets are tanking and sell-off some stocks when markets are euphoric.

In our portfolio, because we’ve largely learned to live with stocks, we tend to buy more stocks when they come on sale and/or we buy stocks periodically during the year to increase our equity holdings. More specifically, to help me gravitate away from my bias to Canadian dividend paying stocks for income we’re owning more low-cost U.S. ETFs for extra growth over time.

Check out some changes I’ve made to our portfolio to increase equity diversification.

Instead of selling bonds to buy our stocks, I use cash savings. I tend to save up cash during the year and make a few lump-sum stock or equity ETF purchases instead.

I will continue to use cash savings to make more equity purchases as I enter semi-retirement.

Consider keeping this much cash on hand yourself – in your asset accumulation years or retirement years.

3. Bonds can be used to spend cash when essential. 

Can you have too much money saved? Too much money in your RRSP?

For most people, I highly doubt it.  Continue Reading…