Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Advice matters: Here’s why

Getty Images

By Bernard Letendre

Special to the Financial Independence Hub

The investments landscape has witnessed seismic changes in North America and around the globe in recent years. Although the vast majority of customers are either satisfied or extremely satisfied with the services they receive from their advisor — based on The Investment Funds Institute of Canada and Pollara Strategic Insights 2019 Canadian investor survey –one narrative that has been gathering a lot of attention focuses narrowly on fees and goes as far as questioning the value of advice. Like all generalizations, this narrative oversimplifies things and can create misleading perceptions.

If you’re a seasoned investor, you know that picking individual securities to create a desired return isn’t a simple task. Investing to achieve a meaningful goal is even harder: it involves developing a good plan and focusing on outcomes rather than fees and performance alone. And that’s hard work.

That’s why I believe in the value of advice. Studies like the one conducted by CIRANO and the University of Montreal have shown that financial advice results in better outcomes: pure and simple. In fact, findings revealed that investors who worked with an advisor over a 15-year period accumulated 3.9 times more assets than those who invested on their own during the same period. Another interesting finding revealed that the difference in outcomes wasn’t mostly due to investment performance (Alpha) but to other factors such as discipline and increased savings rate associated with the advice received by investors: grouped under the concept of Gamma by the study’s authors.

One explanation for those better outcomes could be that in creating a financial plan, an advisor will ask their clients important questions that DIY investors may not think about: or wish to ask themselves. Secondly, once a plan is put in place, an advisor can play a unique role in holding clients accountable towards their own goals, which may result in better financial outcomes compared to people who rely on self-discipline to keep themselves in check.

When it comes to navigating the big moments in life, like passing down a business to the next generation, recognizing early signs of mental health issues that come with age, or handling the death of a spouse, the complexity of such precarious situations often requires a human touch. Investors need someone with the expertise, emotional intelligence and compassion who goes above and beyond to help them every step of the way. Advisors do that.

Advisors focus on more than just Asset Allocation

As is clear by now, advisors focus on more than just asset allocation to help clients achieve their goals. They’re able to support them with a more holistic approach, which could include advice around tax planning, estate planning, insurance planning and more. This is why investors who benefit from the support of an advisor often achieve better outcomes than if they were to try and do it themselves. Continue Reading…

Retired Money: The trouble with playing with FIRE

My latest MoneySense Retired Money column looks at the trouble with playing with FIRE. Click on the highlighted headline to retrieve the full column: Is Early Retirement a realistic goal for most people?

FIRE is of course an acronym for Financial Independence Retire Early. It turns out that Canadian financial bloggers are a tad more cynical about the term than their American counterparts, some of whom make a very good living evangelizing FIRE through blogs, books and public speaking.

The Hub has periodically republished some of these FIRE critiques from regular contributors Mark Seed, Michael James, Dale Roberts, Robb Engen and a few others, including one prominent American blogger, Fritz Gilbert (of Retirement Manifesto).

No one objects to the FI part of the acronym: Financial Independence. We’re just not so enthusiastic about the RE part: Retire Early. For many FIRE evangelists, “Retire” is hardly an accurate description of what they are doing. If by Retire, they mean the classic full-stop retirement that involves endless rounds of golf and daytime television, then practically no successful FIRE blogger is actually doing this in their 30s, even if through frugal saving and shrewd investing they have generated enough dividend income to actually do nothing if they so chose.

What the FIRE crowd really is doing is shifting from salaried employment or wage slavery to self-employment and entrepreneurship. Most of them launch a FIRE blog that accepts advertising, and publish or self-publish books meant to generate revenue, and/or launch speaking careers with paid gigs that tell everyone else how they “retired” so early in life.

How about FIE or FIWOOT or Findependence?

Some of us don’t consider such a lifestyle to be truly retired in the classic sense of the word. Continue Reading…

How bad advice on Defined Benefit plans could cost you your retirement

The following is a guest post by financial planner, author and pension expert Alexandra Macqueen, which originally ran on Dale Roberts’ Cutthecrapinvesting blog on Feb. 26, 2020. Because they both consider it such an important subject, they have given us permission to re-publish on the Hub. While an overview, it can serve as the ultimate guide to defined benefit pension planning. And mostly, Alexandra outlines the pitfalls and the importance of finding a true and qualified pension expert.

By Alexandra Macqueen, CFP

Special to the Financial Independence Hub

If you’re a Canadian facing a decision about staying in or leaving your defined-benefit pension plan, it might be one of the highest-stakes choices you’ll ever make: the amounts you’re considering can be high – worth as much as your house, or even more – the timeline short, the tax consequences significant, the details complex, and the outcome irreversible.

Over the course of my financial planning career, I’ve encountered, unfortunately, more than one pension decision gone wrong. Just how many ways can a pension decision go off the rails? Here are five “pension pitfalls,” drawn from real-live cases that have crossed my desk in the last year or so, along with the lessons Canadians who are facing this decision can glean.

Pitfall Number 1: Unbalanced advice

It is widely understood that defined-benefit pension plans cover what’s called, in the financial planning world, “longevity risk” – or the chance of living longer, even much longer, than you expect. Defined-benefit pension plans protect against the risk of living very long by providing lifetime income.

In exchange for covering off this risk, however, if you die sooner than expected, the pension payments may stop (depending on whether you have a surviving spouse or other beneficiary, and whether your plan provides guaranteed payments for a specified term).

Image by Gerd Altmann from Pixabay

One of the most misleading financial plans I ever encountered – it was just one page, and written in Comic Sans font – outlined the “pros and cons” of staying in a defined-benefit plan. Under “cons,” the planner had listed “mortality risk,” which they defined as the risk of dying relatively shortly after starting to receive monthly pension income.

Here’s what they meant by “mortality risk:” Let’s say you’re facing a pension decision between, say, receiving a lump sum of $750,000 if you “commuted” your entitlement under the plan today, versus $3,500 per month for as long as you’re alive – and you’re wondering about what happens if you die a few years after starting the pension. (“Commuting” your pension entitlement means taking the assets out of the plan as a lump sum today, typically to manage on your own.)

In this situation, and with “mortality risk” presented by the advisor in this way – as equally balanced with the probability of living a long time – it can be very tempting to think that the best option is to “take your money and run.” Maybe you’ll die “early,” you might think – and if you do, you’ll leave an estate!

However, this “financial plan” simply listed “pros and cons” of staying in the defined-benefit plan, without considering the probability of either outcome. If we use the projection assumptions provided for Certified Financial Planners® to reference in preparing financial plans, we can see that a woman aged 65 today has a 50% chance of living to age 91, and a 25% chance of living to age 97, while a man aged 65 today has a 50% chance of living to age 89, and a 25% chance of living to age 91 (see page 13 of the linked document).

Longevity risk vs mortality risk.

Instead of this guidance, however, in this plan the chance of “living” (longevity risk) and “dying” (mortality risk, although you won’t be able find anyone else using this term in the way this advisor did) were presented as equally-weighted possibilities, with no discussion of the likelihood of living to an advanced age.

While a discussion of the impact of dying “early” on pension outcomes is appropriate, this probability should be contextualized – not simply listed as a “con” of staying in a defined-benefit plan, and implicitly characterized as “just as likely” as living to an advanced age.

Pitfall Number 2: Inexpert advice

In this case, a member of a “gold-plated” pension plan (think large sponsoring organization and top-of-the-line pension plan features, such as inflation protection) was going through a divorce, and needed to find a way to equalize assets with a soon-to-be-ex-spouse.

As is not unusual for members of defined-benefit pension plans, the member didn’t have significant other assets. In order to meet his financial obligations, and guided by a financial advisor, he decided to commute his plan entitlement and use the freed-up cash to make an “equalization payment” to his ex.

Unfortunately, neither he nor the advisor really understood the tax consequences of this choice. Because of the size of the plan’s commuted value, the client was unable to shelter much of the paid-out lump sum from immediate taxation, meaning he had a very significant tax bill when tax time rolled around. (That’s because the amount of the commuted value was well in excess of the Maximum Transfer Value set by the Income Tax Act, which specifies how much of that commuted value can be sheltered from immediate taxation.) Continue Reading…

How much is enough? Retirement Calculators and Rocket Science

By Doug Dahmer

Special to the Financial Independence Hub

How much is enough? This is the number we all want to know as we strive to determine how much needs to be set aside to fund our aspirations for freedom of life after work. The industry’s tool of choice, to answer this question, is the retirement calculator.

While these calculators provide a rough guideline for those early on in their accumulation years; once the count down for retirement begins (around ten, nine, eight years before retirement lift-off), you need to shift your attention from the rough guestimates of retirement calculators to a more disciplined planning process. Failure to do so robs people of the retirement they dream of and keeps them from achieving the security they deserve.

Reality Oversimplified

I recently re-watched the movie Apollo 11: a film that focuses on the spaceflight that first landed humans on the moon.

While Commander Neil Armstrong and pilots Buzz Aldrin and Michael Collins garnered most of the headlines, as I watched the mission unfold, it occurred to me that the unsung heroes of this mission were really the 100+ engineers back in Cape Canaveral. These were the people tasked with planning and then monitoring every single detail of the flight.

Complex? Unquestionably. Yet, this mission did have a pre-planned duration (8 days), a known destination (the lunar surface), a highly-researched flight plan and the ability to pre-determine fuel consumption: prior to lift-off.

Those approaching or currently living in retirement should be envious of the simplicity of this type of mission. Why? Because baby boomers face a much more daunting mission. A journey of unknown duration (often 11,000+ days), to an (all too often) poorly defined destination, along an uncharted course (Baby Boomers are redefining retirement), while constantly worrying and wondering if they will run out of fuel (money) before their journey’s end.

Unfortunately, the guidance system offered by the financial services industry is based upon the simple math of retirement calculators. Google “Retirement Calculator” – you will find every financial planning institution has an on-line version readily available. Continue Reading…

RBC leads Big 5 banks in Retirement planning, Dalbar study finds

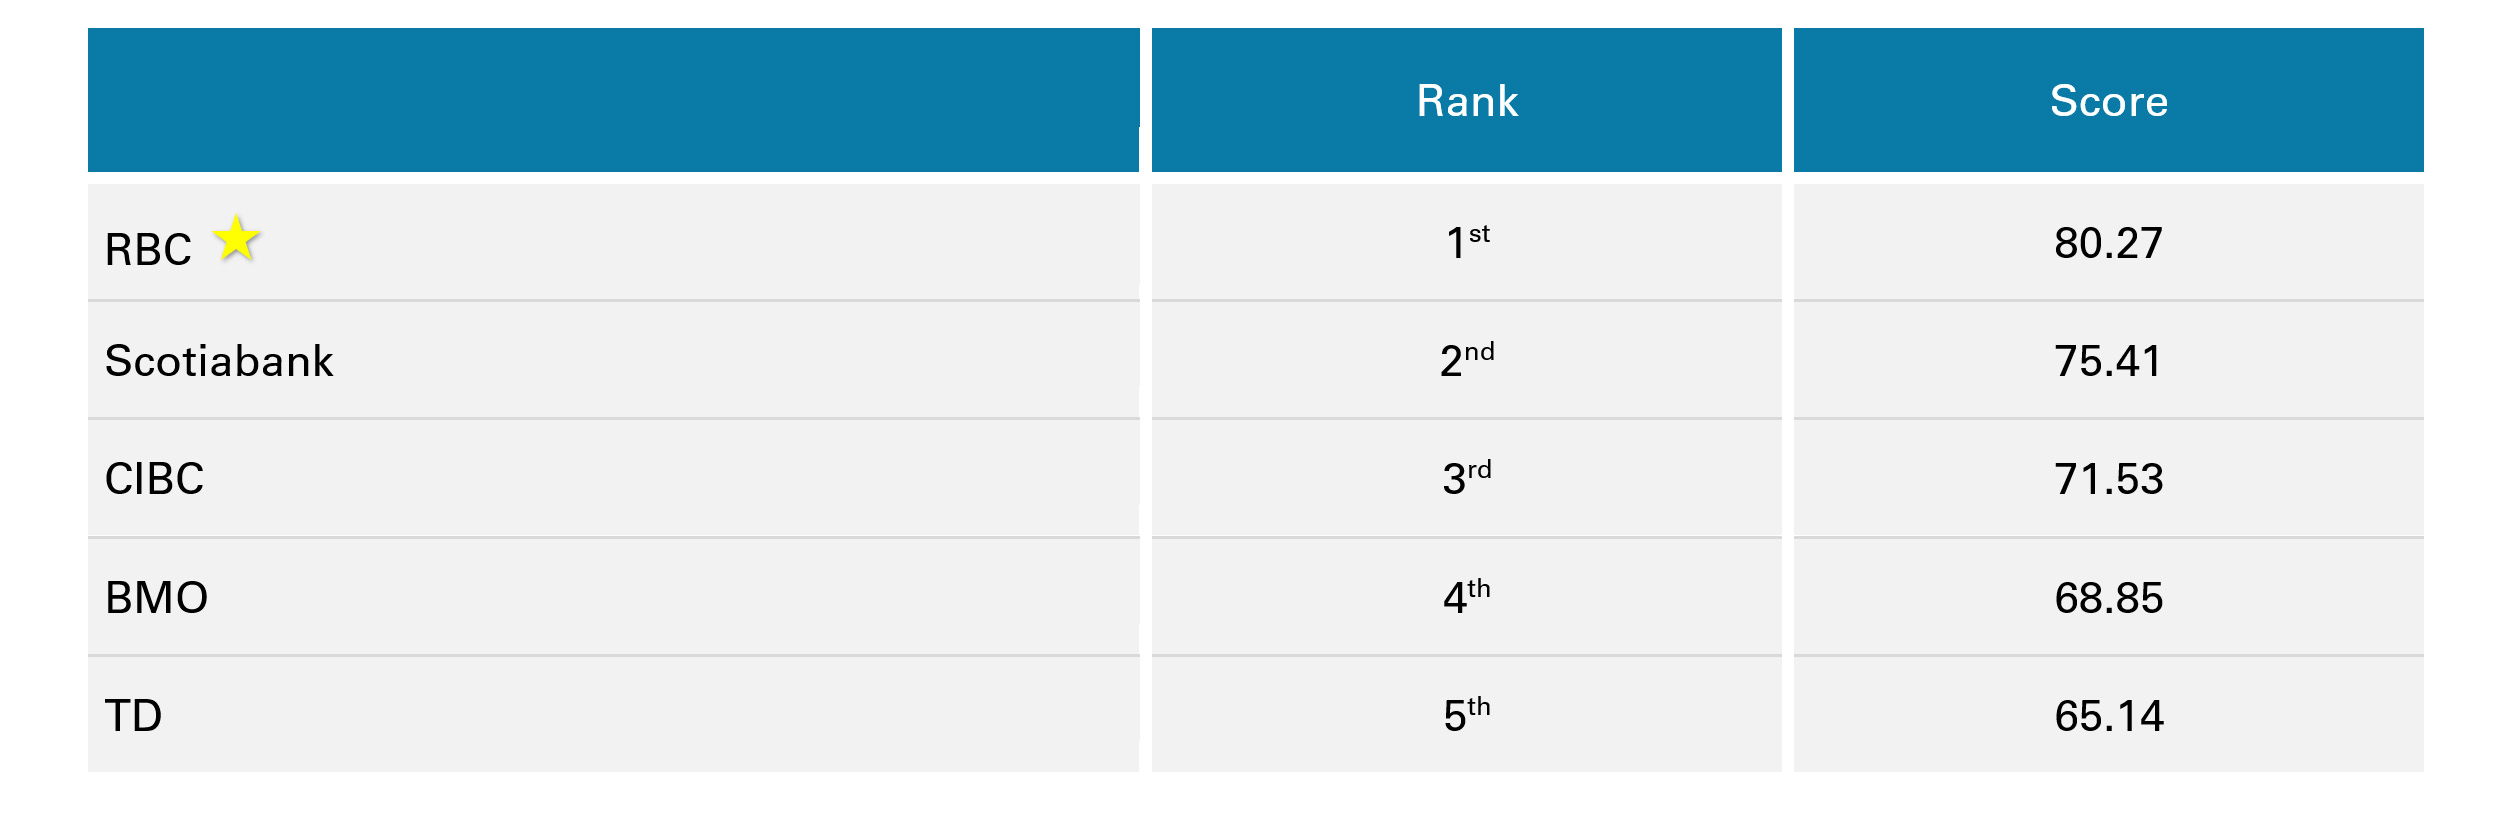
The big 5 banks ranked by DALBAR in order of client preparation for Retirement

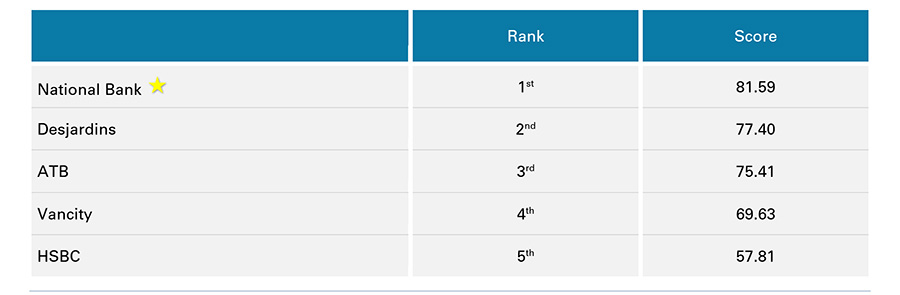
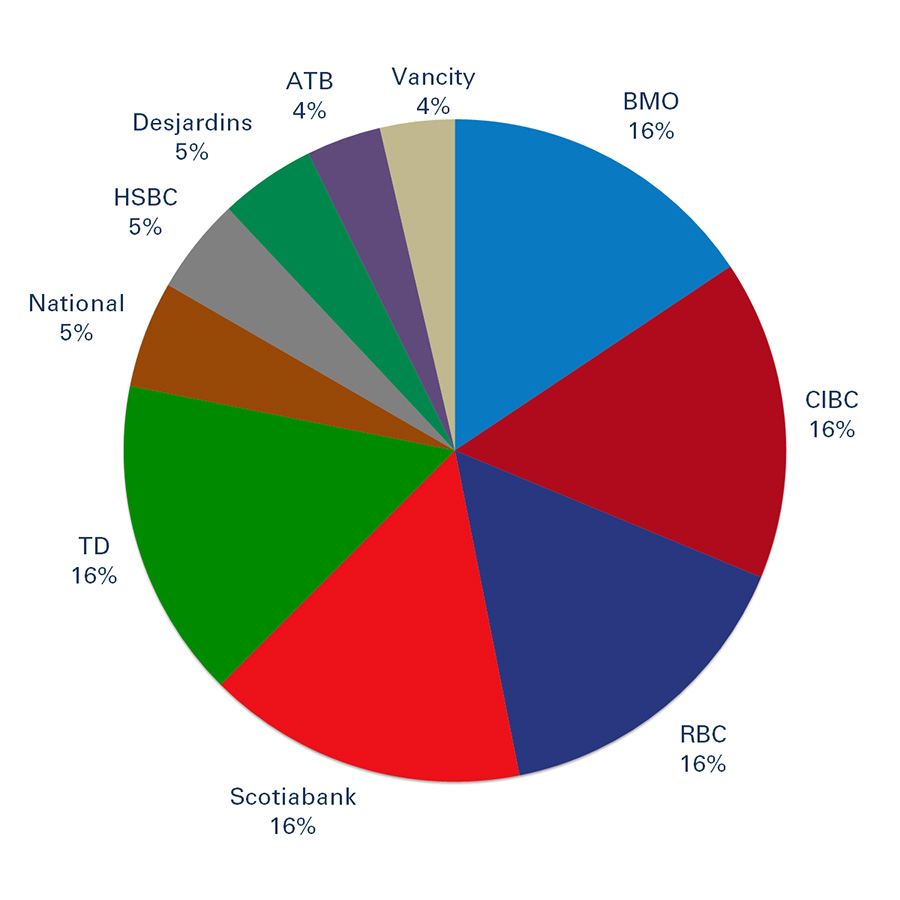
The Royal Bank of Canada (RBC) topped the list of big Canadian banks in serving the Retirement needs of Canadians, according to a new DALBAR study released this month. A first of its kind, the study — released on Feb. 5th and covered in the trade press — sought to assess how the Big 5 handled Retirement conversations through its retail branch network. It also rounded out the study with research on smaller banks, credit unions and regional financial institutions: 1,800 Canadians were polled, all with ten years or less until Retirement. 57% were males and and 74% had portfolios in excess of $100,000.


5 major alternative Financial Institutions ranked by client preparation for Retirement.

In this press release, DALBAR said “Retirement is an ever-growing concern for many Canadians, with increasing life expectancies, diminishing pensions, and a rising cost of living: the retirement nest egg has become more important than ever.”

Well, you’ll get no argument from me on that score, now that I’ve personally started to draw down on my own little nest egg. (Our family uses both RBC and TD, both for banking and through their online brokerage divisions. That’s typical, by the way: 29% of those polled had retirement money with more than one institution.)

Percentages of clients polled at major banks and other financial institutions

“RBC representatives used their experience and expertise to ease client fears, imparted useful knowledge about closing retirement shortfalls, and made the client feel it was a financial coaching experience instead of a transactional one,” DALBAR said. To me, the significant phrase their was “financial coaching experience instead of a transactional one.” Clients rated their experience with RBC to be one of “financial coaching” 70% of the time, higher than the 53% rate at the other big banks.

Only 50% of bank reps introduced the benefits of proper financial planning, although 82% of clients were promised a financial plan. Only 44% of the meeting featured itineraries. And while CIBC, RBC and National Bank led in offering followup meetings with 90% or more of clients, Scotiabank (number 2 overall) led in talking about digital retirement tools at 80% of meetings.

DALBAR vice president Anita Lo said many Canadians realize that government safety nets alone (i.e. CPP/OAS/GIS) are not enough to support healthy retirement lifestyles, so “this is the time for the banks to shine in helping Canadians plan for retirement.”

No surprise that when it comes to Retirement (and I’d argue just about everything else), Canadians prefer speaking to a real person for financial advice instead of relying on online information: DALBAR cited a CIBC study that found that’s the case for 70% of us.

Wide variance in placement of CFPs and PFPs before clients

Staffing with personnel with key financial designations is obviously a plus. DALBAR found RBC places staff with either the CFP or PFP designation 83% of the time for client conversations about Retirement, compared to just 40 across financial institutions generally. Continue Reading…