Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Retirees can sell most of their stocks as they approach Retirement

By Dale Roberts, for Boomer & Echo

Special to the Financial Independence Hub

Retirement can be a scary time for retirees who have considerable and even modest portfolios. We want to protect those assets. And certainly the risk tolerance level for most retirees will drop considerably. And that risk tolerance level will often drive the bus with respect to your allocation to bonds and cash and other risk management techniques you might put to work.

While the order of returns does not matter considerably in the accumulation stage, when we enter retirement we face that sequence-of-returns risk. Years of poor stock market returns early in the retirement funding stage can permanently impair your portfolio and your retirement. And in fact the risk to retirees begins well before that retirement start date. On Cut The Crap Investing I wrote on that with You Should Protect Your Retirement Portfolio Long Before Your Retirement Start Date. [This also ran subsequently here on the Hub.] Have a read of that article and you’ll see that the Retirement Risk Zone is typically qualified as 5 years before retirement and your first 5 years in retirement. We have to be careful as we approach retirement and in those first few years.

Can a near retiree almost completely de-risk the portfolio and sell a large percentage of their stocks? Sure, it may be emotionally pleasing, but with less stocks in hand it may slightly compromise late accumulation stage portfolio growth. That said, the most important part of it all might be that comfort level and that stress reduction event that comes with greatly lessening that stock component. And let’s face it, some near retirees who’ve planned well and who are lucky enough to have a generous defined pension plan might not need much or any inflation-beating portfolio growth. We’re all snowflakes when it comes to retirement funding, we are all entirely unique in our needs and our situation.

But let’s look at a scenario where a retiree does need their personal portfolio to work very hard; they are counting on that portfolio to deliver a generous component of their ongoing retirement funding needs. It’s time for those hard-earned monies to work for them. On the ‘rule of thumb’ spend rate for portfolios see my Boomer and Echo guest post:  The 4% Rule: Is There A New Normal for Retirees?You’ll read that historically a retiree with a sensible mix of stocks and bonds can spend at the rate 4%-4.5% of the portfolio value each year, with an adjustment or increase each year to compensate for inflation.

Given that we want some growth in the later stages of accumulation and we need that growth component to potentially earn returns above that 5% range, we do not want to abandon that Balanced Portfolio model, we still need those stocks.

To manage the risks, we want to keep that nice mix of Canadian, US and perhaps International stocks to work in concert with that bond component. And the most conservative range that we might move to is 80% to 70% fixed income. That’s a very conservative mix of course.

The returns might be muted but you might be able to eek out 3% income from your fixed income component (a mix of bonds and GICs) and perhaps if stock markets continue to deliver 9-10% annual you must see a returns breakdown such as this:

  • 70% of portfolio @ 3% = 2.1%
  • 30% of portfolio  @ 10% = 3%

That might give you a return in the 5% annual range if the stock market ‘rally’ continues and the bond market does not come under pressure.

Now it’s time to dollar cost average back into stocks

OK, so you’ve largely de-risked but you want and need your portfolio to work as hard as possible. When you hit that retirement date you can begin to increase your stock exposure over time. You might become a retiree stock ‘dollar cost averager’. Yup, you’ll employ the tried and true technique that many of us employ in the accumulation stage: you’re going to add to your stocks on a regular schedule.

You’ve de-risked and then you begin and continue to add risk. They call this an equity glide path. And this has been described and studied in detail by retirement funding rockstars Wade Pfau and Michael Kitces. Here’s their White Paper on the strategy. Continue Reading…
How much does it cost to Retire?

By Steve Lowrie, CFA

I’ll start with one good question posed, because it probably crosses everyone’s mind with increased frequency over time:  How much money do I need to retire?

Since I’ve been a financial professional now for more than two decades, I feel well qualified to answer that question.  The answer is:  It depends.

Okay, I realize that isn’t a very helpful answer, even if it’s the truth.  Let’s dig a little deeper.

From a purely quantitative perspective, there are several rules of thumb in common use.  For example, some say if you’ve got 20 or 25 times your annual income in reserve that should do it. Others suggest you’re ready to retire if you can withdraw no more than 4% of your investment portfolio each year.  So, if you have $1 million in your investment accounts, you should plan to withdraw no more than $40,000 annually in a “successful” retirement.

These and similar guidelines offer a decent starting point.  But bad luck happens.  Even if you’ve diligently saved up 20 times your income, if you happened to retire on the eve of a bear market or if you encounter large unexpected expenses, your handy rule of thumb could end up poking you in the eye. Continue Reading…

Motley Fool: How to move from Saving to Investing

What’s the difference between Saving and Investing and how do you move smoothly from the one to the other?  Motley Fool Canada has just published the second in a new series of articles by me about the basic steps towards Financial Independence, or what I call “Findependence.” You can find the first one, which ran early in June, here; and the new one by clicking on the highlighted text here: 2 critical steps toward Financial Independence.

The first article discussed how the journey to Findependence hasn’t even begun while you’re still in debt. To paraphrase one of the characters in my book Findependence Day, you can’t even begin to climb the tower of Wealth until you get out of the basement of debt.

It’s nice to be free of debt, whether high-interest credit card debt, student loans or even a mortgage. It’s a big step moving from negative net worth to being merely broke, where your assets and liabilities cancel themselves out. Being free of all debt is certainly a nice place to be if you’ve been anxious over being hounded by creditors. But it’s not financial independence either, which is the stage of life when all sources of income more than meet your monthly financial needs.

As the followup article summarizes, you want to move from Debt elimination to the intermediate step of Saving, and then from Saving to true investing. Saving is being a loaner — you lend money to a bank or other institution and receive a small amount of interest back as well as your principal upon maturity. But to be an investor you want to be an owner: a business owner, through stocks or equities, or more broadly through a diversified basket of equity ETFs.

The end of the piece references a piece by Investopedia about the difference between investing and saving. You can find their explanation here. It says saving is for emergencies and purchases, by which they mean immediate needs. Investing is about a longer-term horizon (defined as seven or more years) and entails more risk than saving. That’s why they refer to the “risk free” return of investing in cash, treasury bills and the like.

Investing is about Money begetting Money

The beauty about saving is that, once the process is begun, it sets the stage for when  money begins to beget still more money, a process that will ultimately happen even while you’re sleeping. So does investing: the difference is that saving is a kind of junior partner to investing: it works a bit for you, but nothing so hard as true investing for the long term. Saving begets small amounts of money; ultimately, investing begets huge amounts of money: eventually enough to live on whether or not you choose to work another day in your life. Continue Reading…

You should protect your retirement portfolio assets long before your actual retirement date.

By Dale Roberts

Special to the Financial Independence Hub

We often think of wealth building and retirement as static dates. We have that accumulation stage when we are building our assets and net worth, and then we have that decumulation stage (retirement or semi retirement) when we are spending our assets. We tend to think of those periods in static terms, with hard stop and start dates. But that could be dangerous thinking thanks to what Dr. Moshe Milevsky of York University describes as the Retirement Risk Zone. That period is typically 5 years before your retirement date and the first 5 years of retirement. That is when the risks are greatest for a retiree.

We need to prepare our investment portfolios well in advance of our planned retirement date. We need to protect our ASSets. And certainly we build wealth in many ways or by many channels. We have our cash and investment portfolios, and we may also have workplace pensions that are building future retirement payments. And of course we have our real estate and perhaps we are also building value and net worth in business ventures. We may have inheritances that we know are likely to come our way. On that front, we don’t want to count those chickens before they hatch.

In this post we’ll discuss protecting the assets that potentially hold the greatest risk: the stocks in your investment portfolios. Of course the funds could be in an RRSP, RRIF, a locked-in plan of sorts, your TFSA or in taxable accounts. And the risk comes from holding those stocks that can be more than volatile at times.

As a refresher, imagine if you had picked January 2008 as your retirement date. In 2007 things are looking rosy and then the Financial Crisis hits and the US stock markets fall by more than 50%. The chart is courtesy of portfoliovisualizer.com

Retirement 2008 start dateYour handsome $350,000 RRSP portfolio gets clipped to fall below $200,000. If a retiree was spending down in typical fashion on the above portfolio they would have seen that $350,000 drop to the $170,000 range. If one entered retirement with an aggressive all-stock stance, they might have their retirement permanently impaired. The Retirement Risk Zone is more about the retirement funding math compared to your tolerance for risk.

Related post: How Retirees Made It Through The Last Two Recessions

When should you prepare your portfolio for retirement?

Again, Dr. Milevsky suggests the risks are great even 5 years before retirement. I’ll give an example using perhaps the most dangerous start date for a retiree over the last 50 years: the year 2000. This was the beginning of a stock market correction that simply would not let up. US stocks were down for 3 successive years in 2000, 2001 and 2002. That has only happened twice in US stock market history, you’ll have to go back to the Great Depression of the 1920s and 1930s to find the other event. Canadian stocks were down for 2 years in a row and did not suffer the same level of meltdown (though it was certainly a troubling bear market).

As you can imagine if a retiree had the year 2000 as a retirement start date and they entered retirement with an all stock portfolio that asset bucket would have been permanently impaired. Of course, I’m assuming that they need to spend from that account type. If you need to spend from that plan or retirement bucket, you need to protect those assets at least 5 years in advance.

Here’s an example of failure in the last years of portfolio accumulation for a retiree. The year is 1998, the stock markets are one the greatest kicks in stock market history and our retiree is smiling from ear to ear with those incredible portfolio gains and a planned 2003 retirement date.

In 1998 our future retiree has $350,000 in her RRSP account, she is still adding $700 monthly, or $8,400 annual. Once again, we’ll use the US stock market for demonstration purposes. Of course you hold a more diversified asset mix.

Retirement 2003 No ProtectionThe retiree has been adding monies on a regular schedule for 5 years and has a negative rate of return. The real rate of return when we factor in inflation is even less favourable. The retiree started 1998 with $350,000, added $42,000 and ended the period with just over $369,000.
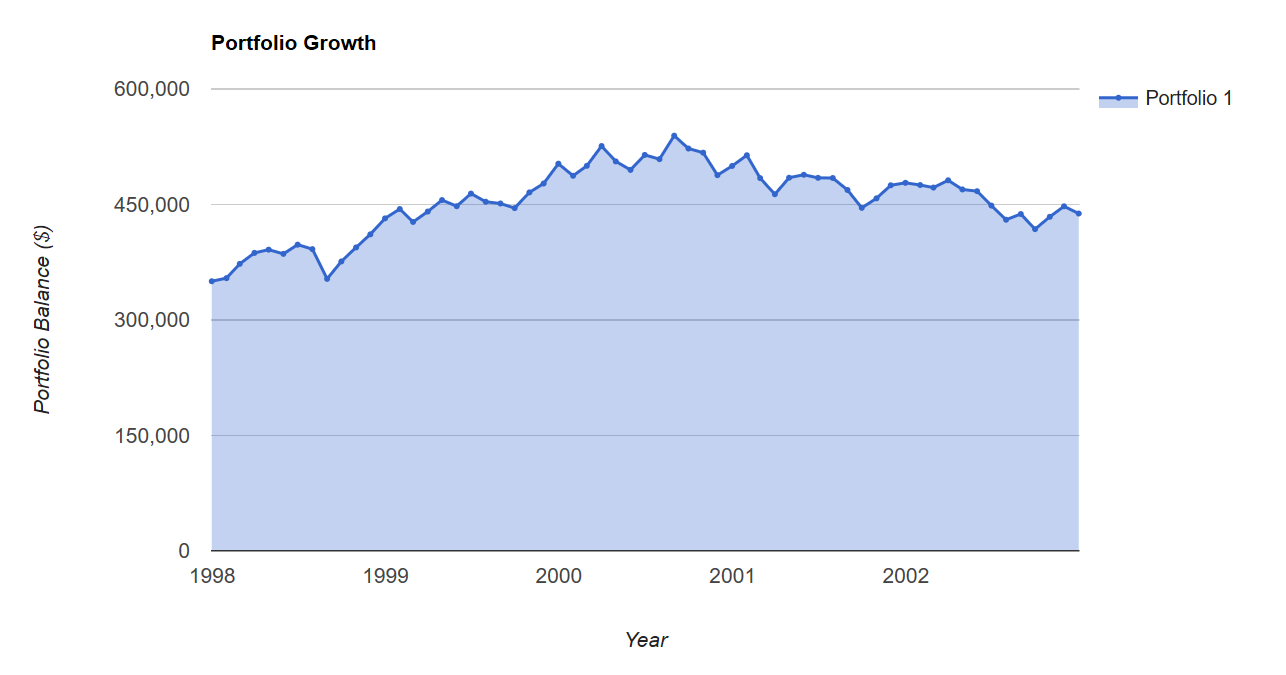
In Scenario 2 our retiree moves to a Balanced Growth model in 1998. She is now 70% stocks and 30% bonds (I’ve used 10 year treasuries). She enters 2003 with modest but positive returns for the period, and with a portfolio value of $438,000.

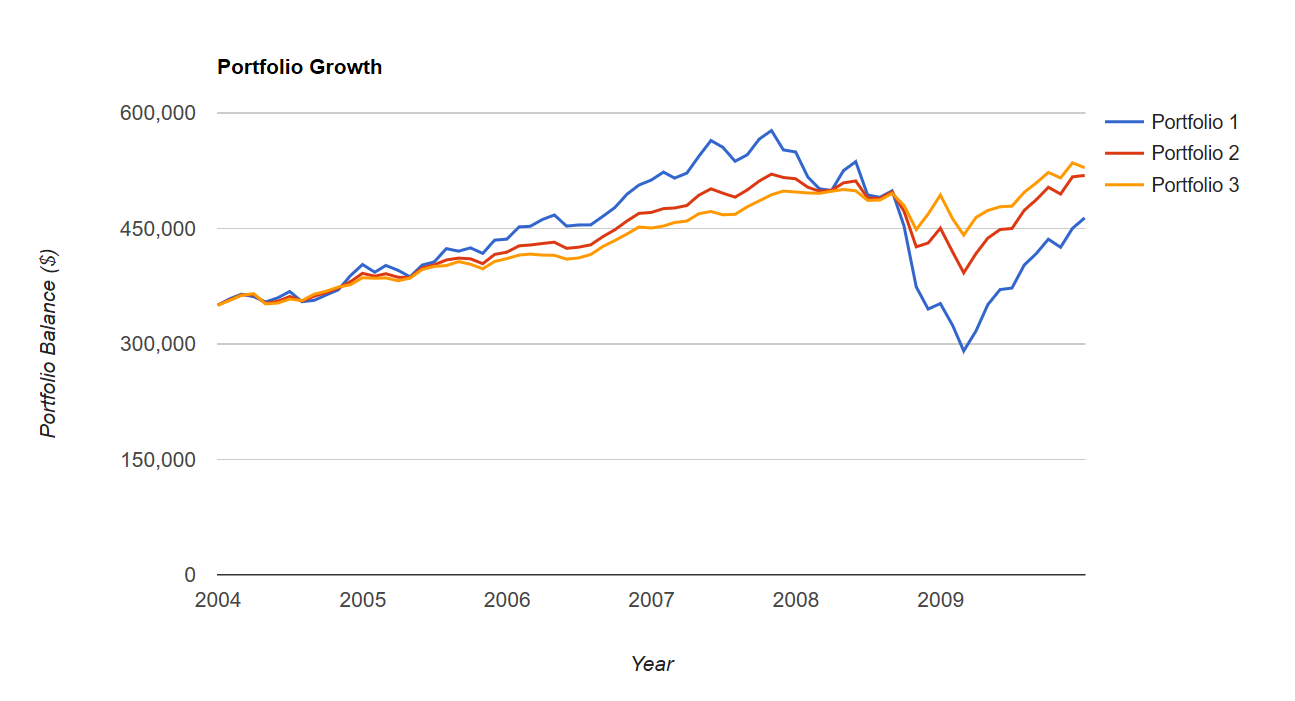
Retirement 2003 with ProtectionAnd of course, to a point, the more conservative a portfolio (more bonds) the better for the test. But hey, that’s all certainly hindsight as we’ve picked the worst possible retirement start date. Right? Not so fast. Even if we look at the 2008 market correction protecting the assets well in advance works much better, and the more conservative the balanced portfolio, the better. You might at least keep your equity allocation in the 30%-40% area.
*And certainly, one can use other assets beyond bonds to manage risks.

We are on the same last few years accumulation strategy with a 2010 retirement start date. In this example we are ‘protecting’ the funds 6 years in advance.

Portfolio 1 is all US 100% equity.

Portfolio 2 is 60% stocks and 40% bonds.

Portfolio 3 is 40% stocks and 60% bonds.

Retirement 2010 start date various allocationsThe only time this strategy will fail, that is deliver opportunity cost, is when we take out a severe market correction and invest only in a period of mostly rising markets (bull markets). Of course as an investor or advisor that is not a risk that you want to take. You do not want to guess that a stock market correction is not in the near future. Stock market corrections historically come along with regularity. We are currently in an abnormal period of an extended (mostly) bull market run.

A more conservative accumulation stage

As we approach the final turn toward the retirement ‘finish line’ we obviously want to increase our portfolio value. Continue Reading…

Boomer & Echo guest blog: What I’ve learned so far in Semi-Retirement

Regular Hub guest blogger Robb Engen returned the favour earlier this week by inviting me to write a blog for his site Boomer & Echo. You can find that version by clicking on the highlighted headline: What I’ve learned so far in Retirement.

For convenience, it also appears below, including original links, with a Hub headline and a few subheadings that better reflect the central point that I personally don’t consider myself fully retired yet. This version has a few extra points added, plus two links to FIRE pieces that didn’t appear in the original B&E version. And as a bonus, it includes near the end an update on some of our recent travels, which hopefully reinforce some of the broader themes described in this blog.

Which begins as follows:

Through most of the five years the Financial Independence Hub has existed, Boomer & Echo’s Robb Engen has been kind enough to allow the “Hub” to republish some of his blogs that first appeared on his own site.

He recently suggested we turn the tables and invited me to write a guest blog for Boomer & Echo recounting some of the lessons I’ve learned in my decades as a financial writer and what I’ve learned so far in Retirement. Here it is.

For starters, my age alone qualifies me as a Boomer: I recently turned 66, but do not consider myself retired: at most, I consider myself semi-retired. As Robb would know, running a website is no trivial undertaking and I aim for new content 5 days a week, 52 weeks a year. That and writing for a handful of media outlets keeps me fairly occupied, although the privilege of doing this from home means I gain a couple of hours that would formerly have been expended on commuting.

Indeed my last full-time salaried staff job that involved commuting and bosses ended five years ago, when I stepped down from the editorship of MoneySensemagazine. That two-year stint followed 19 years at the National Post/Financial Post, most of which time I was the paper’s personal finance columnist.

Those familiar with my books or blogs would not expect me to describe myself as Retired, since my shtick has long been Financial Independence, or my contraction for it: Findependence. That’s as in Findependence Day, a financial novel I wrote in 2008 (Canadian edition) and 2013 (US edition.)

As I have often written, I do not regard the terms Retirement and Findependence as synonyms. You can be Findependent but not Retired, as I am; but it’s hard to be Retired if you’re not Findependent.

In the old days, the traditional “full-stop” retirement was considered to happen at age 65, which even today is when you can first start receiving Old Age Security benefits. (And yes, I do now collect OAS, for reasons I’ve explained elsewhere). But “Findependence Day” can be years or even decades earlier: you may still choose to work for money but on your terms: the magic day is when you’re completely free of debt and have enough saved (and properly invested) that even if you never earned another dime you could meet all your major living expenses, assuming some variant of the 4% Rule.

Even if I considered myself as having “retired” at age 61, that’s relatively old by the standards of the so-called FIRE movement, which of course stands for Financial Independence Retire Early. True FIRE people aspire to “retire” in their 30s or 40s, sometimes even in their 20s, typically by saving like demons for a decade or so: in the most extreme cases they may save      something like 50% of their income.

I’m more like Robb, where he described in his blog why he wasn’t yet paying down his mortgage because he first wanted to maximize RRSP and TFSA savings. Mind you, my books do argue that “the foundation of financial independence is a paid-for home” but I’m old school and we bought our first home (of only two) back in the 1980s, when Toronto real estate was pricey but hardly at the lofty levels of today. Of course, interest rates were much higher then: close to 12% in our case, so we were motivated to pay off the mortgage as quickly as possible.

I don’t see myself as an early retiree or a “FIRE” blogger

There have been some interesting critiques of FIRE, nicely summarized by Fritz Gilbert in a guest blog for the Hub: Is the Fire community full of hypocrites? Fritz is an American Pluto award winning blogger for RetirementManifesto.com, who I’ve come to know through our joint membership in the Younger Next Year 2019 Facebook group, which I helped found and have helped moderate (along with the site’s prime mover Vicki Peuckert Cook) since late 2017. Fritz “retired” himself at age 55 about this time last year. But as we would both argue, he’s hardly retired in the classical sense of the term. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.