Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

How to create a pension for the Average Joe: 65 with as little as $200K in Savings

By Billy and Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

We know many of our readers are not “average.” However, if average Joe can support his retirement on as little as US$200,000 savings, imagine what you can do with the amount you have!

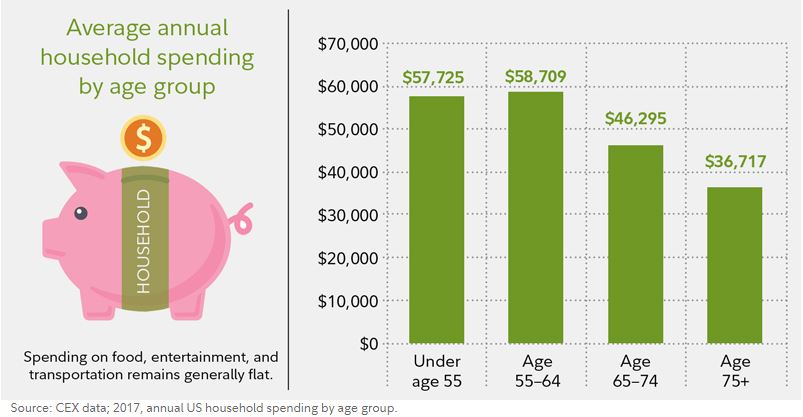
By reading the chart below, you can see that the average spending for retirement households age 65 – 74 is US$46,000.

It is tough to make that $46k amount with only Joe’s savings, so what should he do?

Social Security

The average recipient today (in the United States) collects US$1,461 a month, or US$17,532 a year. Joe’s SS check is average and he has a wife who also collects the average Social Security amount.

$17,532 times 2 (people) = US$35,000 per year.

Not quite the $46,000 that they need but getting closer.

Hopefully, Joe has his retirement money invested in VTI (Vanguard Total Stock Market) or SPY (S&P 500 Index) and is making market gains equaling around 10% annually.
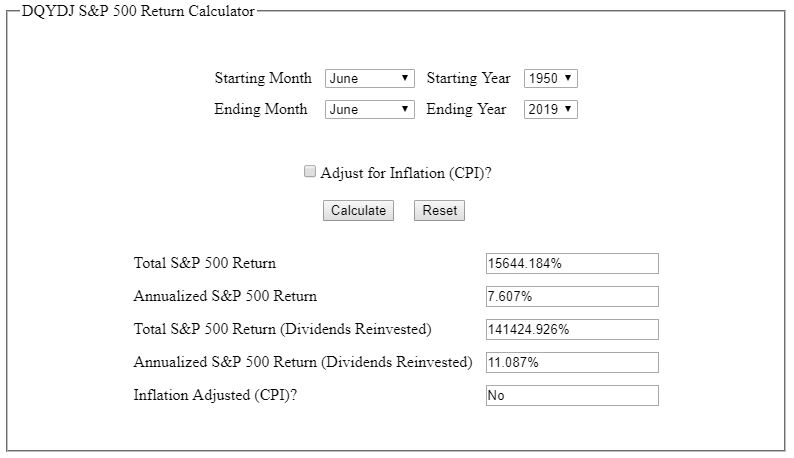

Here you can see that since the 1950’s — about when Joe was born — the S&P 500 has had an annualized return of over 11%, dividends reinvested, but let’s use 10% as a more conservative projection.

Remember, Joe has to make up $11,000 to match his average spending ($46,000). But let’s give Joe an extra one thousand dollars per year so he can pamper Mrs. Joe with occasional gifts and dinners out.

So, he needs $12,000 out of the $200,000 in savings per year to make up the difference in spending. That’s an extra $1.000 per month.

Invested in the S&P 500 — based on 69 years of returns and using 10% as the annual return — after his first year he would have $220,000 minus $12,000 withdrawal = $208,000.

Now Joe has $47,000 in annual income: $35,000 from Social Security and $12,000 from investments.

Plus, his $200,000 has grown to $208,000, a 4% gain outpacing inflation at the current rate of less than 2% per year.

Their Social Security payment is also indexed to inflation so as inflation rises, so will their Social Security. Continue Reading…

Retired Money: What to do about falling GIC rates

PWL Capital’s Ben Felix

My latest MoneySense Retired Money column has just been published. It looks at the reversal the past year in interest rates, which impacts seniors who had started to look forward to at least half-decent GIC rates near 3%. You can find the full piece by clicking on the highlighted headline: Are GICs right for retirees looking for Fixed Income? 

Short of embracing high-yielding dividend paying stocks, the more palatable alternative for conservative retirees might be fixed-income ETFs. The article focuses on a recent video by CFA Charterholder Benjamin Felix, an Ottawa-based portfolio manager for PWL Capital. Felix argues that at a minimum such investors should have a mix of both fixed-income ETFs and GIC ladders.

The latter let you sleep at night because they are invariably “in the green” in investment accounts. But while in the short term fixed-income ETFs can be in the red — just like equity ETFs — Felix makes a compelling argument for the higher potential returns of bond ETFs.

Felix believes that what really matters for investors is total return: “Holding a lower-rate GIC after a rate increase still results in an economic loss.” Bond returns consist of principal, interest payments and reinvested interest, so focusing only on return of principal misses the point. Individual bonds are not ideal for individual investors, as they require extensive research, are relatively expensive and tricky to trade.

Short-term GICs miss out on the term premium

But short-term GICs miss out on the term premium, which is substantial over time. Going back to 1985, Felix says short-term bonds returned 6.51% annualized versus 7.97% for the aggregate bond universe (which includes some short-term bonds).  This shows how much mid- and long-term bonds bring up the overall return. To be clear, this period captures one of the greatest bond markets in history but Felix says it is still reasonable to expect a relationship between riskier longer-term bonds and higher expected bond returns. Risk and return should be related.

GICs are also illiquid, so even if an investor chooses to include GICs in a portfolio, they will generally also include bond ETFs, which – like stock ETFs – can be sold any trading day. Nor do GICs provide exposure to global bonds.

Of course, a nice alternative are those asset allocation ETFs we have often discussed on this site. See for example this excellent overview by CutthecrapInvesting’s Dale Roberts: Which All-in-One, One-Ticket Portfolio is right for you? 

The Felix video can be found at his Common Sense Investing YouTube series here.


No surprise: the best retirement investments are the same as for everyone else

We recommend that you base your investing for retirement on a sound financial plan relying on the best retirement investments.

One thing investors of all ages fear is not having a good financial plan in place so they have enough retirement income to live on once they’ve stopped working. Looking for the best retirement investments, addressing this concern is usually a high priority for many of our Successful Investor Portfolio Management clients.

Four key factors to consider when investing for retirement

  1. How much you expect to save prior to retirement;
  2. The return you expect on your savings;
  3. How much of that return you’ll have left after taxes;
  4. How much retirement income you’ll need once you’ve left the workforce.

Our portfolio diversification approach gives you strong potential for long-term gains  

If you diversify as we advise, you improve your chances of making money over long periods, no matter what happens in the market.

For example, manufacturing stocks may suffer if raw-material prices rise, but in that case your Resources stocks will gain. Rising wages can put pressure on manufacturers, but your Consumer stocks should do better as workers spend more.

If borrowers can’t pay back their loans, your Finance stocks will suffer. But high default rates usually lead to lower interest rates, which push up the value of your Utilities stocks.

As part of their portfolio diversification strategy, most investors should have investments in most, if not all, of these five sectors. The proper proportions for you depend on your temperament and circumstances.

For example, conservative or income-seeking investors may want to emphasize utilities and Canadian banks in their portfolio diversification, because of these stocks’ high and generally secure dividends.

More aggressive investors might want to increase their portfolio weightings in Resources or Manufacturing stocks. For example, more aggressive investors could consider holding as much as, say, 25% to 30% of their portfolios in Resources.

However, you’ll want to spread your Resource holdings out among oil and gas, metals and other Resources stocks for diversification and exposure to a number of areas.

Stick with conservative estimates to account for unforeseen setbacks

As for the return you expect from investing for retirement, it’s best to aim low. If you invest in bonds, assume you will earn the current yield; don’t assume you can make money trading in bonds.

Over long periods, the total return on a well-diversified portfolio of high-quality stocks runs to as much as 10%, or around 7.5% after inflation. Aim lower in your retirement planning — 5% a year, say — to allow for unforeseeable problems and setbacks.

Above all, it’s important to remember that while finances are important, the happiest retirees are those who stay busy. You can do that with travel, golf or sailing. But volunteering, or working part-time at something you enjoy, can work just as well. Continue Reading…

How Property Investment can help you reach Findependence (Financial Independence)

By Rebecca Lee

Special to the Financial Independence Hub

Financial Freedom is a way for anyone to escape the grind of the 9-5 work life to live the life they desire without relying on anyone else for money. Almost all of us trade our time for money to pay our bills, eat, travel and live in general. Without trading our time, it would be impossible to pay for the things we need and want. Many of us are stuck doing this until we have just enough to retire late in life.

Those who find financial freedom, AKA Findependence, do so by acquiring assets that generate wealth on their own. As the saying goes, “don’t work for your money, make it work for you.” One of the most popular types of these assets is real estate. Here’s how you can achieve financial freedom through real estate investment.

Have a strategy

Financial freedom, what it is and how to achieve it is different for everyone. Everybody has their own needs and wants and will require a different amount of cash flow to live on. Therefore, you must have a personalised strategy based on your income, savings and liabilities.

Without a plan, you won’t know what opportunities to take advantage of and what ones to pass up on. A strategy that’s designed for you will help take the emotions out of your decisions, avoid making mistakes and minimise risk.

Get the mindset

Wealth creation and investing requires a certain mindset to be successful. A lot of people are selling “Get rich quick” schemes but unless you get super lucky, this is not a realistic approach. Real estate in particular is a long-term investment game.

Real estate investors understand that their wealth will grow not overnight, but over years of gradual growth. Understanding this and knowing yourself enough to be able to commit to such a long-term plan is key to reaching financial independence. Investing in real estate isn’t as simple as buying property and waiting for its value to grow. Continue Reading…

Challenging conventional investment wisdom

By Noah Solomon

Special to the Financial Independence Hub

Many investment professionals tell their clients:

  • That markets tend to rise over the long-term.
  • To “hang in there” and “sit tight” during bear markets because they will eventually recover their losses.

While we agree with the first assertion, we wholeheartedly disagree that investors should sit idly through bear markets based on the notion that they will eventually live to see a better day. Rather, we strongly believe that a dynamic approach that adjusts to changing markets can provide superior long-term results.

The table below illustrates this by showing what happens to $1M invested in two different portfolios:

Portfolio A Portfolio B
Year 1 -30% -5%
Year 2 +30% +5%
Year 3 -30% -5%
Year 4 +30% +5%
Sum of returns 0% 0%
Value at end of year 4 $828,100 $995,006


Since the returns over four years add up to 0% for both portfolios, many people assume that the final value of each portfolio at the end of year 4 should be $1 million. However, as the last line in the table indicates, this is far from true.

Portfolio A, which is more volatile, declines in value by $171,900, while portfolio B, which is less volatile, suffers a decline of only $4,994.

The observation that two portfolios can have the same sum of returns over 4 years yet have significantly different values at the end of the period can be explained by the mechanics of compounding. After experiencing a 30% loss, a $1 million portfolio is worth only $700,000. Unfortunately, a subsequent 30% gain will only bring the value of the portfolio back to $910,000, which is still $90,000 less that its starting value. However, when a $1 million portfolio experiences a 5% loss, its value is $950,000, and a subsequent gain of 5% will bring its value up to $997,500, which is only $2,500 less than its starting point. Continue Reading…