Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Could you become car-free?

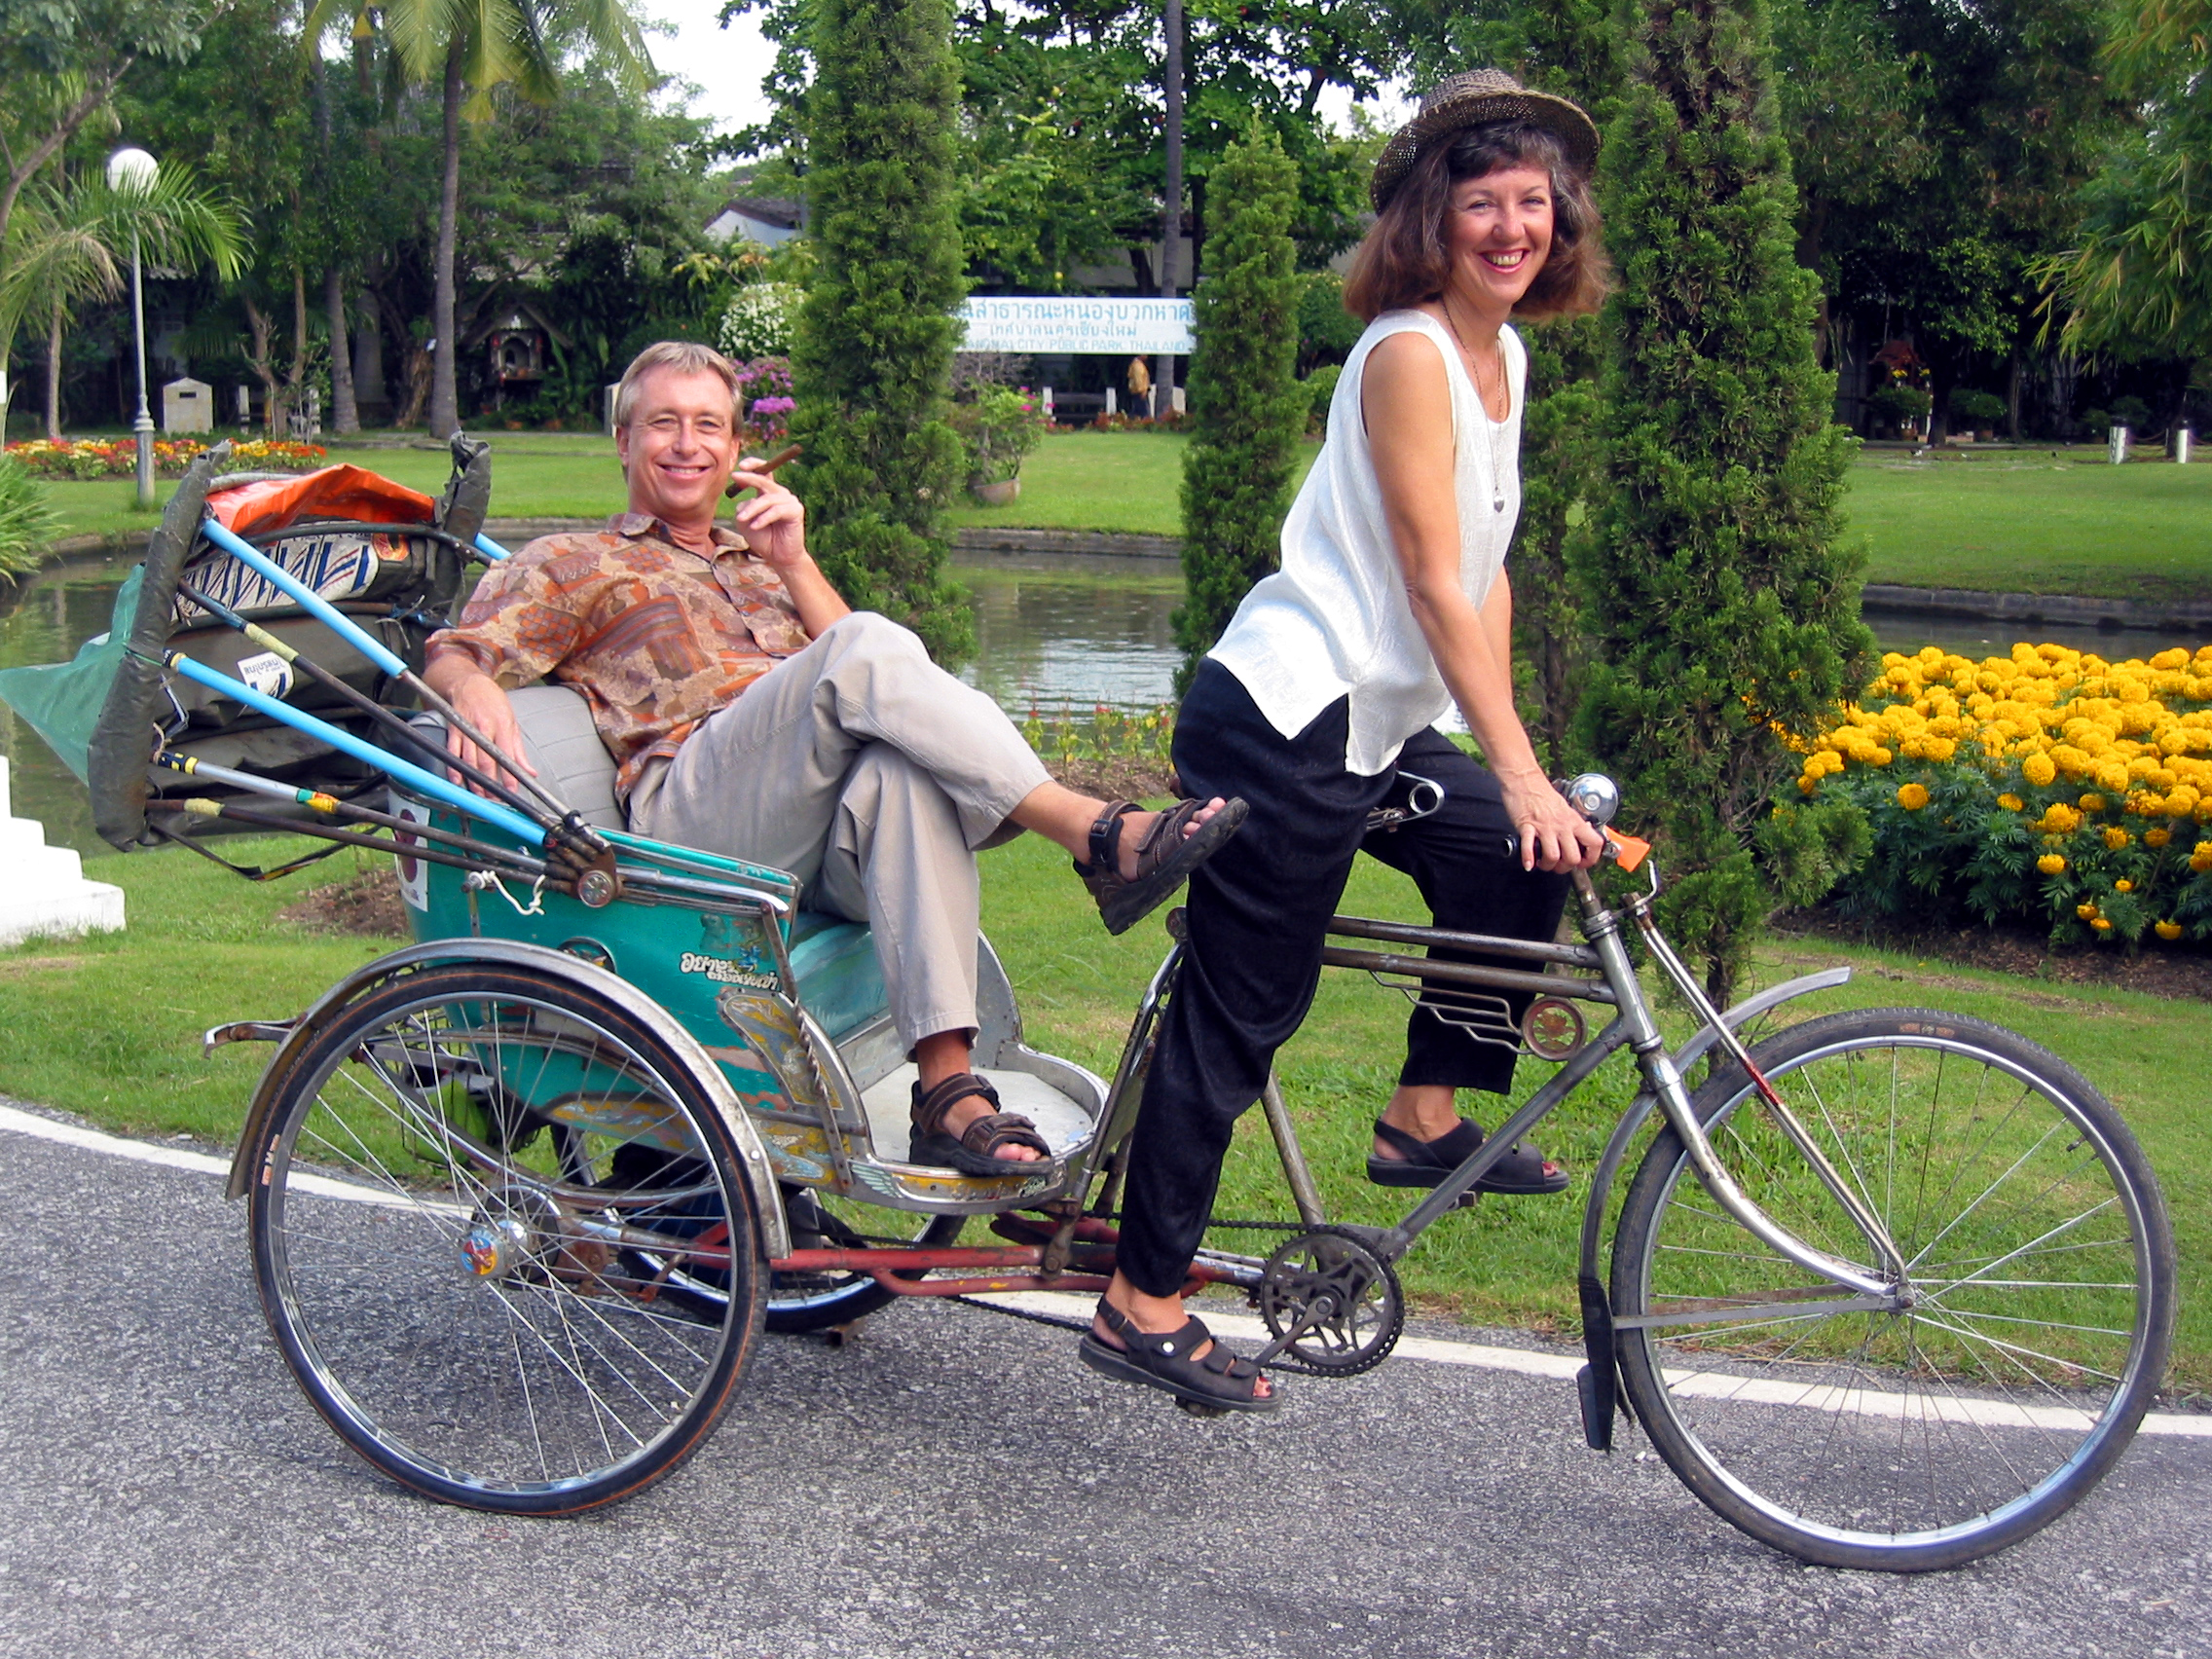
Billy and Akaisha on a Jak-a-Ran in Thailand

By Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

It wasn’t a decision we took lightly.

In fact, Billy and I discussed the idea of becoming car-free for several years. There were good reasons to do it: no more maintenance and repair costs; no more fees for insurance, license plate renewal, or registration; no more fuel expense; and no more worry about storing the vehicle here in the States when we are traveling overseas for months or years at a time.

But there were also some obvious downsides. We wouldn’t have the freedom to come and go at a whim. And because we live in the American Southwest, where temperatures reach triple digits in the summer, we wondered how we’d manage to get around during the sun season.

Silly idea or feasible plan?

Most people we know couldn’t fathom the idea of giving up their vehicle and saw this new lifestyle choice as a hardship. Americans love their automobiles, and owning one is packaged as part of the American Dream. A look at the automobile and truck commercials today describe how we will be sexier, more popular, physically stronger, and obviously smarter if we purchase their brand of car.

As we’ve described on our Retire Early Lifestyle website, Billy and I live in an active adult community where we are within walking distance to stores, restaurants, and several different entertainment options. Most of what we need is near to us, and we appreciate the slower pace of life with all the rewards it brings. Many of our neighbors use a small scooter, golf cart, or bicycle to get around within a reasonable range. When we need to go somewhere farther, we trade services or pay cash to a neighbor or friend for their time. This is much cheaper than a taxi, more sociable, and we aren’t bogged down with worries about maintaining a vehicle. Both sides appreciate the trade, and our lives are enriched.

After almost two decades of world travel, we realized that the only place where we need to drive is in the States. Elsewhere, we take public transportation or hire a private driver. For the amount of time we live in the States, and for the amount of money that owning our own transport required, we finalized our decision to sell our vehicle.

The year was 2009.

What about you? 

Retirement takes many expressions and even if you could never see yourself as becoming completely free of car ownership, maybe you have toyed with the idea of keeping only one vehicle instead of two.

The following sites may help you with this transition: Continue Reading…
The (Renewed) Case for GICs

**This is a sponsored post written by me [Robb Engen] on behalf of EQ Bank. However, as always, all opinions are my own.

A guaranteed investment certificate (GIC) is unlikely to spark an exciting dinner party conversation but when stock markets are reeling, like they were earlier this year, investors often seek safe havens to wait out the storm. Cash is king for those who don’t have the stomach to watch their portfolio plunge in value, and GICs at least offer the promise of a modest return.

Back in February 2009, when the global financial crisis had just about reached rock-bottom, 30-year-old me was scrambling to meet the RRSP deadline and bought a five-year GIC. It was a costly mistake in hindsight. The Toronto Stock Exchange surged ahead for the next five years, earning annual returns of 9.52 per cent, while my five-year GIC earned an average annual return of 2.75 per cent.

Instead of turning my $7,000 contribution into nearly $10,000, I only had $7,800 to show for my decision. At the time, though, I thought the GIC was a smart move because I had to make a quick decision on what to do with my contribution, and the stock market still looked downright nasty.

Why invest in GICs?

The truth is there’s nothing wrong with stashing your savings inside the comfort of a GIC. Here are four times when it makes good sense to put your money in GICs:

1.) When your entire portfolio is sitting in cash, waiting for “the right time” to get into the market

If you’re the type of investor who can’t ignore the doom-and-gloom economic headlines, and who’s convinced that a market meltdown is always imminent, maybe the stock market isn’t right for you.

Having your retirement savings constantly sitting in cash and earning nothing is like sitting on the fence and being paralyzed to move for fear of making the wrong decision at the wrong time.

A GIC ladder, which might involve purchasing equal amounts of one, two, three, four, and five-year terms, will maximize your risk-free returns and still give you the option of dipping your toes in the market each year when one of the terms comes due.

2.) When your investing strategy boils down to chasing last year’s winning stocks or mutual funds

If you’re the type of investor who’s constantly looking for the latest fad, you might be falling victim to the behaviour gap – the difference between investment returns and investor returns.

Consider that, according to DALBAR, from 1986 to 2016 the S&P 500 Index averaged 10.16   a year, but the average equity fund investor earned just 3.98   a year.

When you think about our poor investor behaviour, coupled with sky-high mutual fund fees (at least, here in Canada), those investors who just can’t help themselves might be better off parking their savings in the best five-year GIC and earning a guaranteed return. Continue Reading…

Resilience in the face of Market Volatility

By Fritz Gilbert,

Special to the Financial Independence Hub

The market’s been a bit “wobbly” in the past few days, in case you haven’t noticed.

We shouldn’t be surprised, and we shouldn’t worry.

Today, I’ve chosen to talk about market volatility, and how we should think about volatility in terms of our overall retirement plans.

As I write these words, the S&P 500 was down another 2%, on top of a 3.3% decline yesterday.

Down 5% In Two Days.  Yep, that’s volatility.

Here’s the 5-day chart:

Down … down … down.

But, it’s no big deal

Funny thing about markets, they’re volatile.  As Ben Carlson wrote last Friday, the market has averaged a daily drop in excess of 3% three times per yearsince 1928.  So, we should expect “Big Down Days” on a regular basis, even if we haven’t seen too many of them lately.  One interesting note is that 80% of those “Big Down Days” occur during a market correction or bear market.  Makes sense, but it can and does happen during Bull markets, as well.

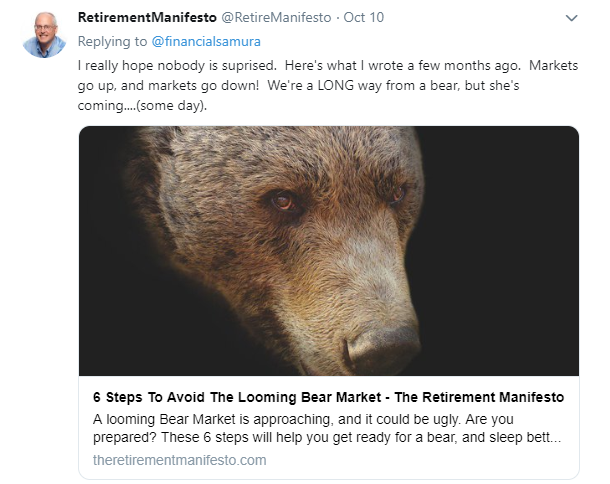
Here’s what I posted on Twitter after the Big Down Days last week:

I’ve no idea where things will go from here. In all honesty, I really don’t care.  I know markets will go up, and markets will go down, and we’d be naive to assume otherwise as we plan for our retirement.  I don’t check the market daily, and I don’t worry about daily volatility.

Markets Go Up, And Markets Go Down. Make sure you prepare for volatility as part of your retirement plan.

Let’s Be Real.  The CAPE ratio continues at abnormal highs, which increases the likelihood of subpar performance over the coming years.  I’m expecting it, and I’ve incorporated it into our retirement withdrawal strategy. As of October 16th, after two consecutive down days of 2%+ declines in the S&P 500, the CAPE ration remains at a level of 30.80, well above historical norms of 16.6, as shown below:

We’re being unrealistic if we expect the market to continue an uninterrupted upward trend, especially in light of today’s high valuations. Volatility is real, so make sure you incorporate it into your retirement plans.

One Day’s Decline = One Year Of Withdrawals

As I thought about the market’s move on October 10, I realized that the 3%+ move was equivalent to an entire year’s Safe Withdrawal Rate, and I sent the following Tweet:

Resilience In The Face of Market Volatility

Rather than worry about the volatility, Be Resilient.  Think about volatility before you retire, and incorporate your strategy for volatility into your retirement planning.

As part of our retirement planning, we have to be realistic to the fact that markets will face volatility.  They always have, and they always will.  It’s the way the world turns, and we’re well advised to plan accordingly.   It’s why I built my Bucket Strategy as my primary plan for Retirement Income, and it’s the reason I really don’t worry as the market ebbs and flows over any given day.  In fact, I don’t even watch the market dynamics on a day-to-day basis.

On a long-term basis, it doesn’t really matter.

I don’t watch the market on a day-to-day basis. I know our Bucket Strategy will cover all but the worst Bear Market. Click To Tweet

Markets will be volatile. 

It’s the nature of The Beast.  Plan for it, and have sufficient funds to absorb a significant market downturn should it happen in the early years of your retirement.

Best to plan for the worst, and hope for the best.

Fritz Gilbert is the Founder of The Retirement Manifesto, a Plutus Award winning blog dedicated to helping people Achieve A Great Retirement.  After 30+ years in Corporate America, most recently as a Commodity Trader, Fritz retired as planned in June 2018 at Age 55.  He and his wife are looking forward to extended travel and “giving back” to their community through charitable work in retirement. This blog was published on his website on Oct. 16, 2018 and is republished here with his permission. 

A great business + great planning = A great Retirement

By Mark Bertoli, IPC Securities Corporation

Special to the Financial Independence Hub

It has been estimated that over the next decade there will be approximately $1 trillion in personal wealth transferred from one generation to the next. A great portion of that wealth is currently tied up in equity within Canadian small businesses. A recent study conducted by IPC Private Wealth, a division of Investment Planning Counsel (IPC) revealed some startling statistics.

A full 42% of business owners are uncertain about their retirement and what is more alarming is that almost half of business owners (48%) do not plan to seek the advice of an advisor. Some of the existing plans of business owners consist of working until they are unable to do so (36%) or exiting when they have enough money (25%). One highlight is that 29% of business owners plan to run their business until their successor is ready.

How to maximize the value of a business

Start with a plan: it is a great strategy to start early. A 10-year plan is a good starting point. Seeking a financial advisor with experience in business transition is a great advantage. This may be the owner’s first business sale but the advisor may have navigated these waters many times and has the advantage of knowledge. The advisor may bring in specific expertise to increase the value of the business. If an advisor – who truly acts as a coach – is brought into the situation, one of the first projects would be to systemize the operation and create a turnkey situation. The business is then far less reliant on the owner and more valuable to a potential buyer or successor. With time on your side, many other strategies may be employed.

A family business or a liquidity event

When selling or transitioning a business, there are several steps that are critical to its future success, as well as the social continuity of the seller, buyer, or heir. Continue Reading…

Motley Fool on Market Cycles: How worried should investors be?

Talk about strange timing! Last weekend, right before this week’s sharp market sell-off, the Motley Fool Money podcast featured an interview with Howard Marks, the influential money manager at Oaktree Capital. Marks has just released his second book, Mastering the Market Cycle, which I promptly bought and downloaded on Kindle and read over the (Canadian) Thanksgiving weekend.

Subtitled Getting the Odds on Your Side, the book is only Marks’s second, following the 2011 publication of The Most important Thing: Uncommon Sense for the Thoughtful Investor. What was clear about the podcast and the book is that Marks felt that the current market cycle is closer to a top than bottom. In fact, late in September Motley Fool Money’s lead podcaster Chris Hill titled a blog “How worried should we be about Howard Marks’ Market Caution Warning?”

Cautious Optimism

Maybe a little, it turns out, although at the time of that podcast Marks’ mood was one of “cautious optimism.” Since then the market seems to have shifted a bit more from optimism to caution. As it happens, Wednesday’s 800-plus plunge in the Dow occurred just two days after I personally started to rebalance our portfolios, partly inspired by my weekend reading, so the new book was quite relevant.

Book publishing being what it is, and with much of it largely written in 2017, Marks doesn’t come right out and declare that the market is near a top; authors tend to be aware that books need to stand up for a few years. However, a quick look at his web-based market commentaries underline his cautious approach. As Hill pointed out in his conversation with Tim Hanson, Marks’ memos may not be quite as well known as Warren Buffett’s, but he nevertheless has a strong following.

At age 72, Marks has seen more than his share of market cycles and claims to have been able to profit from most of the biggies: from the 1999 Tech Wreck to the 2007 Global Financial Crisis. In fact, he’s been around long enough to remember the famous Nifty 50, which were perhaps analogous to today’s mania for FANG stocks. Continue Reading…