Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

How mortgage rule changes impact affordability

By Alyssa Furtado

Special to the Financial Independence Hub

The mortgage market in Canada is heavily regulated. Both the federal government and the Canada Mortgage and Housing Corporation (CMHC) control almost every aspect of residential mortgage lending.

The government decides what criteria people must meet when getting a mortgage in Canada. Rules apply to almost every aspect of the mortgage, ranging from the maximum amortization to the minimum down payment required when buying a home.

In the last few years, the government has taken action in response to rapidly rising house prices in an effort to keep people from taking on mortgages they can’t afford. A number of changes have been made to mortgage rules since 2012. Dry descriptions of the changes make it difficult to understand their true effect.

Instead, let’s take a look at some examples of how some recent mortgage rule changes affect their ability to borrow.

Sarah and Rachel
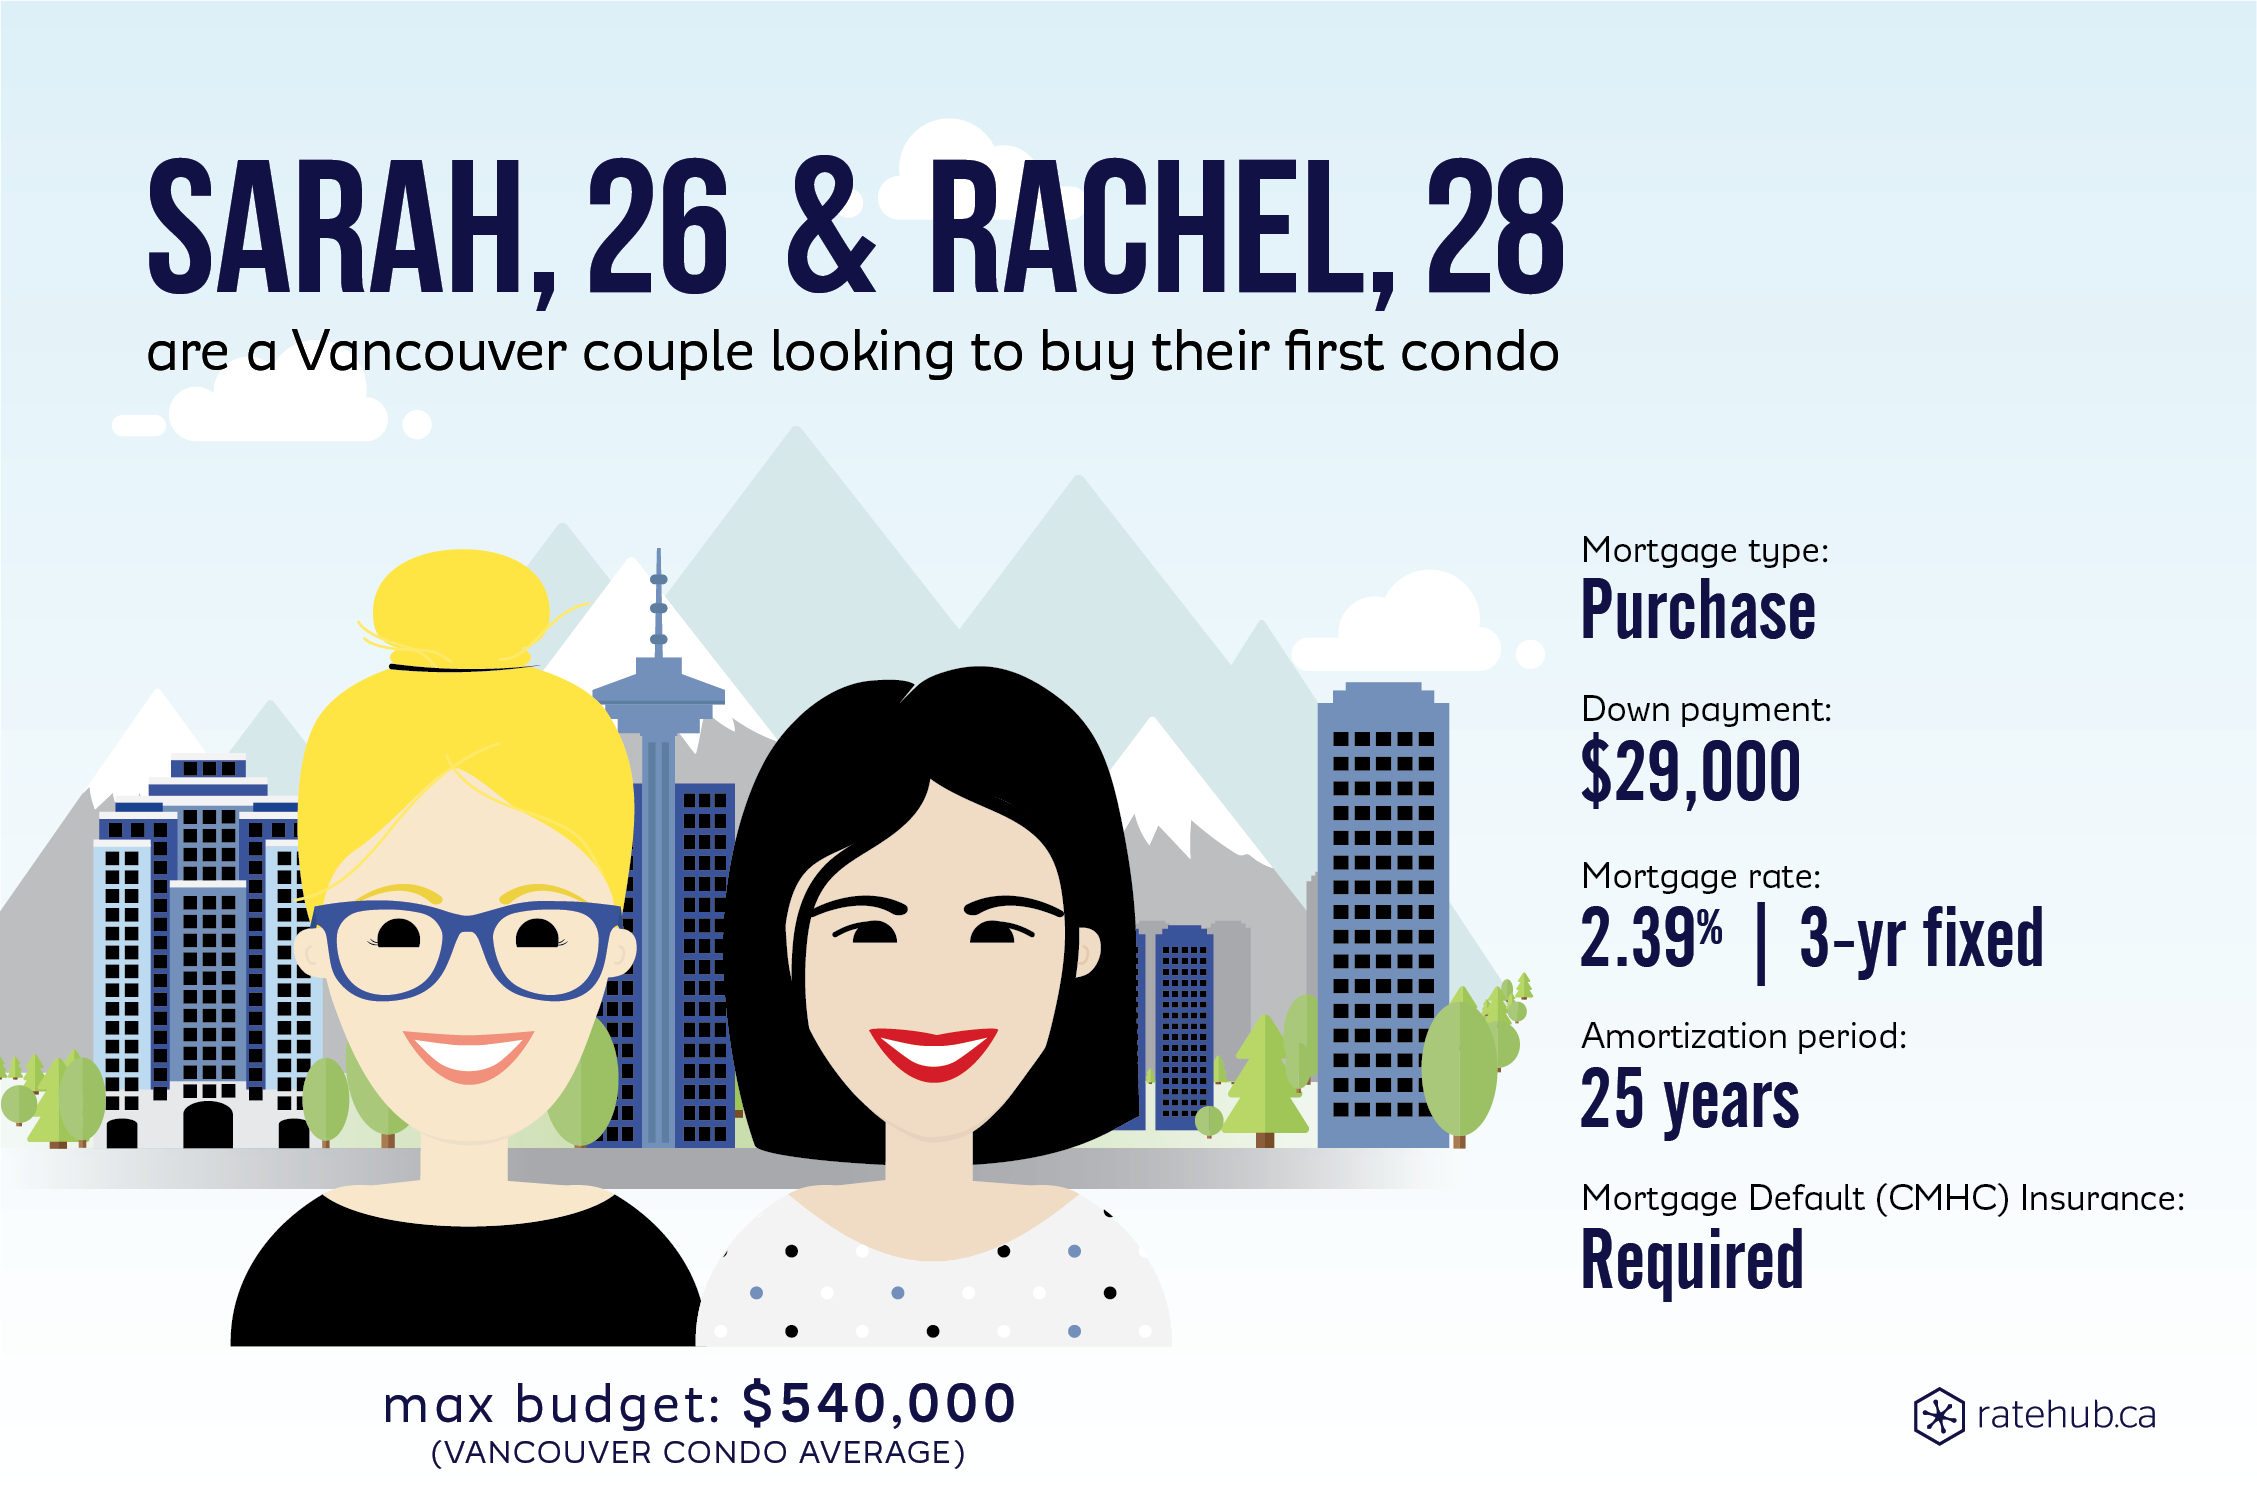
Even though Sarah and Rachel are choosing a three-year fixed mortgage with a rate of 2.39% for their condo purchase, new “stress testing” rules introduced in October 2016 mean they have to qualify at a substantially higher mortgage rate than they’ll actually get. The qualifying rate is set by the Bank of Canada (BoC), and is currently 4.84%. When checking a mortgage payment calculator, they find that even though their monthly payment will be $2,352 at their chosen rate, they’ll need to prove they can afford payments of $3,043.

A new rule pertaining to minimum down payments that came into effect in February 2016 will apply to Sarah and Rachel as well. The minimum down payment on a home sold for over $500,000 was raised to 5% of the first $500,000, and 10% of any amount thereafter. For their $540,000 purchase, Sarah and Rachel have to save a little longer: the minimum down payment went up to $29,000 from $27,000. They’ll also need to pay for CMHC insurance since their down payment is less than 20%. Continue Reading…
6 unexpected expenses you need to prepare for

By Lidia Staron

Special to the Financial Independence Hub

“Life is like a box of chocolates. You never know what you’re gonna get.”

Truer words were never spoken. We all know how life can be full of surprises: some of them happy while others can be a huge pain in the backside.

We’re talking about unexpected expenses here. Even when you’ve already set your budget,  you’re sticking with it, and you’ve got some savings set aside, you can still get knocked off your financial track due to a cost you never anticipated paying for. While you were patting yourself on the back for your financial savviness, life was preparing to throw you a curveball. To help you expect the unexpected and plan your savings accordingly, we’ve listed six of the most overlooked costs that are just waiting for you around the corner.

1.) Home repairs or replacements

It’s a fact of life that everything breaks down eventually, especially if it experiences everyday wear and tear. Your home won’t last forever, especially since you and your family are living inside it everyday. Anything that breaks down will need to be taken care of right away. Plumbing, electricity, a leaking roof, a flooded kitchen, a broken oven, termites …  all  these are things you never think of saving for when you plan your budget.

2.)  Health-related bills (Dental and vision care)

We all know you need to save up for those emergency room visits and prescriptions you may need to fill. But have you ever considered that you may suddenly need to pay your dentist or eye doctor a visit? If you’ve ever had a really bad toothache that turned out to be a root canal in your future, then you know this is something that needs to be placed in your “health budget” right away. Continue Reading…

Borrowing to invest? Beware of rising interest rates.

Del Chatterson

By Del Chatterson

Special to the Financial Independence Hub

Your financial advisor is probably not recommending it and you may be naturally averse to more borrowing, but it is hard to ignore the basic principles of financial leverage from Finance 101. (The principles have not changed, since I first taught the course in 1972!)

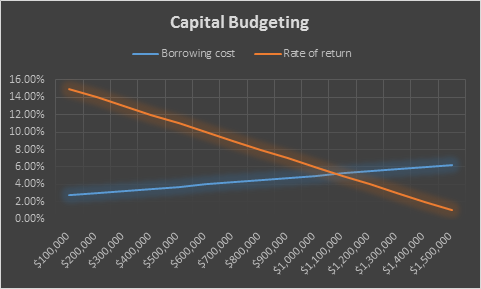
As explained in a chapter on Capital Budgeting, companies and investors should continue to invest in projects until the marginal cost of capital equals the marginal rate of return: assuming you select projects in order from the highest return to the lowest return and that the cost of borrowing increases with the total amount of loans outstanding.

So in the example chart shown to the right, you would borrow and invest up to $1.0 million, which is the point where the expected rate of return declines to meet increasing cost of borrowing at about 5%.

You may have confirmed the theory from your own experience. Your current portfolio has a few investments that are achieving better than 10% or 12% returns, most congregate around the long-term average of 7% to 8% and a few continuing disappointments are returning below 5%, or worse.  Your lowest cost of borrowing is probably the mortgage you signed in 2015 at 2.5% or a car loan at 1.9%, but your subsequent borrowing for a personal line of credit is at 3.25%.

Continue Reading…

Half of us fear rising interest rates will be negative for our finances

Now that interest rates have finally appeared to bottom, consumers are starting to worry about the prospect of rising rates and their impact on their personal finances.

This is explored in my latest article, which is in Monday’s Financial Post (e-paper and online). You can access it by clicking on this self-explanatory highlighted headline: Only a quarter of Canadians have a  rainy day fund, but more than half worry about rising rates.

It describes a new Forum Research Inc. poll that shows more than half of Canadians (51%) fear rising rates will negatively impact their personal finances. The national poll of 1,350 voting-age adults was conducted after the Bank of Canada raised the prime interest rate from 0.75 to 1% on September 6th, which in turn followed an initial 0.25% hike in July.

After an amazing run of nine years of ultra-low interest rates, it’s clear consumers are starting to fret the party is over. Anyone with variable-rate mortgages might well be petrified that interest rates could again reach the high teens, as they did in the early 1980s. Little wonder that many homeowners are starting to “lock in” to fixed mortgages while rates are still relatively low.

Of course, as Credit Canada’s Laurie Campbell notes, for the longest time it’s paid to stay variable and flexible, whether with a variable-rate mortgage or a line of credit. It does cost a bit more to “lock in” to fixed mortgages, as Campbell notes, but the ability to sleep well at night in my opinion more than makes up for the difference.

While the poll asked specifically how consumers felt about the second hike, “they are worried more are coming,” Forum Research president Lorne Bozinoff told me. 12% say the negative effect will be extreme. However, 17% believe rate hikes will have some positive aspects:  you’d expect debt-free seniors to welcome higher returns on GICs and fixed-income investments. Another 38% don’t think it will have an effect either way.

Lorne Bozinoff

A quarter have no emergency savings at all

Bozinoff is more concerned that 26% of respondents have no emergency savings, and 40% have a cushion of a month or less: 9% have less than a month and 11% just a one-month cushion.

Financial planners generally recommend three to six months as a hedge against job loss or other setbacks. A minority do: 14% have two to three months, 9% four to five months, and 13% six months to a year. Only 15% have a year or more and predictably, 56% of the latter group are 55 or older. Continue Reading…

5 common senior financial traps and how to avoid them

Scott Terrio’s Twitter feed (@CooperTrustee) reads like a financial horror story. Terrio, an insolvency expert at Cooper & Co. in Toronto, uses the 140-character medium to share the multitude of ways seemingly well-off Canadians end up buried in debt and turning to debt consolidation, consumer proposals, and even bankruptcy.

Canada’s record household debt levels have been a cause for concern for years, but Terrio sees a new problem on the horizon. Canadian seniors are the demographic increasing debt at the fastest rate.

Take Dorothy, an 81-year-old widow who owns a home with a 1st mortgage from a secondary lender. She refinanced a couple of years ago to do house repairs ($18,000), assist her son with divorce legal fees ($37,000), and to help her grandson with tuition ($8,500).

When her partner died she was no longer able to make the mortgage payments. A friend from church referred her to a mortgage broker.

The broker suggested a reverse mortgage,  which would let her stay in her house without the monthly mortgage payment. But the money from the reverse mortgage wasn’t enough to pay out the 1st mortgage after fees and penalties. She needed a private 2nd mortgage at 12 per cent to pay the balance.

Dorothy co-signed a $26,000 car loan for her nephew and co-signed with her son for funeral expenses ($12,000) for her partner. Her son stopped paying, so Dorothy was pursued (100 per cent).

She then ran into tax trouble by not having tax on her OAS & CPP deducted for the first few years. She owes $21,000 in tax, much of it penalties and interest.

This scenario is becoming more common among seniors today.

“Many are in a unique quandary. They’re asset-rich, but cash-poor. Cash flow is tight. Pensions are fixed, and many have underestimated retirement costs,” said Terrio.

So what do they do? Many seniors cash out assets to make ends meet. Others raid their home equity and take out lines of credit. All have financial consequences.

We asked Terrio to share the top financial traps seniors fall into and how to avoid them:

1.) Tax problems

Most seniors were used to being paid by their employers in after-tax dollars. At pension time, many don’t have taxes deducted to offset their Old Age Security and Canada Pension Plan income and therefore end up spending taxable pension income.

Continue Reading…