General

Affording our Lifestyle, post Financial Independence

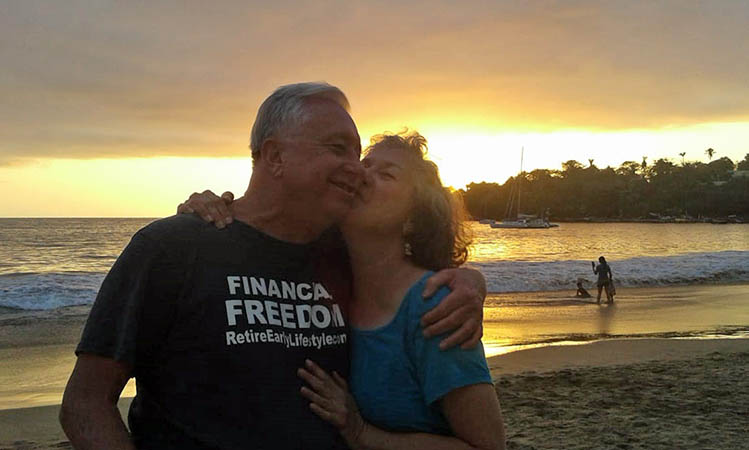
Billy and Akaisha enjoying Chacala Beach, Nayarit, Mexico

By Billy and Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

It’s no secret that we have been living on around US$30,000 per year.

Now into our 31st year of financial independence we see no need to lower our spending. In fact, we are trying to increase it.

Some people do not believe we can have such a fulfilling lifestyle on this small annual amount, so in this article, we thought to explain how we do it.

Let us break this down

Decades ago we discovered the lower cost of living in Mexico. This is what is referred to as Geographic Arbitrage. You make your money in US Dollars – in our case dividends, capital gains and Social Security – and spend in the local currency. After running around the Caribbean Islands and RVing through the Western US, in 1993 we were invited to visit friends living in Chapala, Mexico. Since we track our spending daily, we saw our expenses in Dollar amounts drop rapidly by being there.

After spending 4 years in Chapala,we started traveling to Asia – another low-cost destination – again utilizing the strength of the US dollar to ease the pressure on our wallets. All the while, our stock market assets continued to increase in value.

For a handful of years again we made Dollars in the market and spent Quetzales in Panajachel, Guatemala. Easy living is what we call it and this is an essential style of our retirement approach.

In between all of these travels we spent time in our Adult Community Resort in Arizona. Surprisingly, our cost of living there was one of the best in all of the locations where we have lived. Yes, we were spending Dollars, but the price of living with value was attractive, and we modified our spending in other ways. Often, we walked or biked to grocery stores and various locations. Rarely using our vehicle at that time, the insurance company gave us a discount for having such low annual mileage. Weather – other than the super-hot summers – was pleasing and since there were tennis courts in the resort and friendly neighbors, we had assorted low-cost entertainment options.

These days we’re settled back in Mexico where the exchange rate is as good as it gets.

Travel

As our readers know, we still travel quite a bit even though Covid has kept us mostly in Mexico.

We have upgraded our lodging and choose more comfortable ways to get from place to place. Intra-country flights are very affordable here in Mexico, with a one-way ticket from Guadalajara to Puerto Vallarta costing less than $50USD per person. One time we flew from Guadalajara across the country to Merida for $38USD each. There is no need to stay at home when a week away is so attractively priced.

Because we have permanent residence status here in Mexico, we are entitled to an INAPAM card offering us 50% discounts on buses. Therefore, our transportation expenses for a bus trip to the beach is 2-for-the-cost-of-one. For example, we go to Chacala Beach, Nayarit, Mexico for 538Pesos for the 2 of us. This is about $13USD each on a luxury, air-conditioned bus.

This INAPAM card also gives us free entry into museums and certain public areas that charge a fee.

Rent
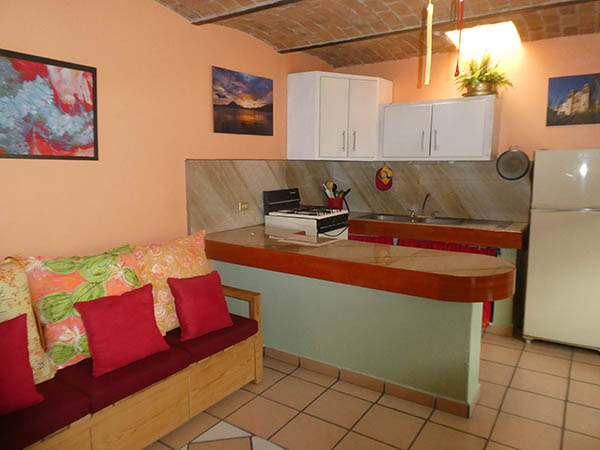
Our apartment, showing the upgrades we just finished

Our rent is $300USD monthly, or the Peso equivalent. This amount allows us to live in a gated garden complex, where we have a roomy one-bedroom apartment centrally located. Shopping, restaurants and doctors are easily within walking distance. There is no pressure to own a car in a foreign country with all the expenses like maintenance, licensing, fuel and insurance that are involved.

Recently we remodeled our kitchen with new counter and backsplash tile plus paint, costing 13,800 Pesos, about $690USD. Continue Reading…
Behavioural Issues with Variable Asset Allocation

By Michael J. Wiener

Special to the Financial Independence Hub


I recently adopted a specific type of dynamic asset allocation for my personal portfolio.  I call it Variable Asset Allocation (VAA).  It only deviates from my original long-term plan when the world’s stocks become pricey, but any time you change your long-term investing plan, there’s the possibility you’re just looking for a smart-sounding justification for giving  in to your emotions.

It’s certainly true that I’ve been concerned for some time that stock prices are high and that the chances of a stock market crash have been rising.  But I know better than to join the chorus of talking heads predicting the imminent implosion of the stock market.  I don’t know what will happen to stock prices in the future.

I’m not tempted to just sell everything and wait for the crash.  It’s possible that stocks will keep rising, and when they finally do decline, it’s possible they’ll remain above today’s prices.  It must be sickening to wait for a crash that doesn’t happen.  This would have been the fate of someone who decided 5 years ago that prices were too high and sold out.

Waiting for a Crash that never comes

Whenever an investor sells completely out of stocks, the problem is when to get back in.  Sometimes, it’s a significant market decline that causes investors to sell all their stocks in fear.  Then they have to decide when it feels safe enough to buy back in.  Too often, they wait until prices are much higher than when they sold.  The same thing can happen to those who sell because they think stock prices are too high.  They can sit in cash waiting for the big crash that never comes.

So, could some form of this happen to me with my VAA?  The answer is no, but only if I follow VAA strictly.  With VAA, if my portfolio’s blended Cyclically-Adjusted Price-Earnings (CAPE) ratio exceeds 25, I add CAPE minus 25 (as a percentage) to my bond allocation.  For example, when the blended CAPE of my portfolio sits at 32, I add 32-25=7 percentage points to the bond allocation I would have had if the CAPE were below 25.

If stock prices rise, the CAPE rises, and if my bond allocation rises enough to trip my rebalancing threshold, I rebalance from stocks to bonds.  However, given that I’ve chosen to adopt VAA, selling stocks is easy because that’s what my emotions are already telling me to do. Continue Reading…

Are Financial Advisors really ready for a serious downturn?

https://advisor.wellington-altus.ca/standupadvisors

By John De Goey, CIM, CFP

Special to the Financial Independence Hub

Clients facing a big, sustained drop in the markets might not listen to advice that worked last time

I recently listened to an excellent podcast hosted by my friend Preet Banerjee, who had my acquaintance Dan Bortolotti as his guest. Much of the conversation was about Dan’s fantastic new book, Reboot Your Portfolio, but the topics bounced around a bit, and I was left with a sense of dread about the overall mood.

Listeners got a glimpse into what it is like to give advice to retail clients, and some of the anecdotes about the life of an advisor I thought were particularly telling. Discussion around the fear felt by investors and advisors in the five or six weeks when COVID-19 first hit was harrowing, but I couldn’t help but think that advisors listening in might be misled.

In the past decade or so, a narrative about the role and value of professional advice has included behavioural coaching. The term can include such value-added activities as topping up RRSPs, getting wills written, naming proper beneficiaries, integrating taxes and other valuable things. But the one thing that always seems to top the list is the notion that advisors add value by encouraging clients to remove the emotion from decision-making. This helps clients take a long-term view focused on personal life goals.

While I agreed with almost everything said in the podcast, I was concerned by what wasn’t said. There was a lot of self-congratulation about advisors navigating their clients through the major market drawdown in early 2020, as if it were a given that this would always be the case.

In truth, that drawdown was the shortest bear market in history. As bear markets go, a walk in the park. Mr. Bean could have provided enough comfort and counsel to keep clients invested in that market. While there is nothing wrong with giving credit where credit is due, I think the podcasters were too congratulatory to mainstream advisors. There was also a reference to the global financial crisis of 2007-2009, and both podcasters agreed that it was far harsher than the 2020 experience. Again, the story was that good advisors can help emotionally driven clients stay on course when things get choppy. They can – but that’s not necessarily the same as they will.

Comparing downturns

That attitude I heard is likely based on what they’ve seen and done in their careers – and those careers embody a time of relative stability. Few advisors today were working in finance during the bear market of 1974 when the OPEC oil embargo crashed markets. In addition, the one-day drop of more than 20 per cent in 1987 was a blip of sorts, but markets were still up that calendar year.

So, the only significant bear markets most people reading this have lived through were: 1) at the turn of the millennium (aka the dot.com bubble), and 2) the global financial crisis. Both were medium-sized drawdowns. But what if we experience something earth-shattering? How will we react? Nobody knows.

If you claim to play a role in modifying behaviour constructively, you will also be prepared to stand up and take your lumps should that behaviour not be what you wanted nor expected.

Here is what I mean by “medium sized.” In the first one, it took about seven years for the S&P 500 to return to its previous level; the index stood at around 1,500 in April 2000 and didn’t return to that level until October 2007. While the previous high was technically reached, it was only a few weeks before the trend reversed and markets began to fall back again. The S&P 500 didn’t get back to the 1,500 range again until February 2013. There was a dip and return, closely followed by a second dip and return, and the net effect was the entire market went sideways for more than 13 years.

Most people refer to the early 2000s as two distinct drawdowns experienced back-to-back, but I would describe both as medium-sized drops. Either way, the net effect, excluding dividends, was no market growth for more than 13 years. Continue Reading…

Should you invest in Canadian Depositary Receipts (CDRs)?

www.investorsedge.cibc.com/

By Bob Lai, Tawcan

Special to the Financial Independence Hub

It is always great to see innovation and new products in the banking and investing industry. A few months ago, CIBC introduced the Canadian Depositary Receipts (CDRs) on the NEO Exchange as a way to provide Canadian investors with yet another option for investing in non-Canadian companies.

Canadian Depositary Receipts, or CDRs, may not be a familiar name for many readers. However, some readers may be aware of American Depositary Receipts, or ADRs. ADRs have been trading in the US for many years as a way for investors to buy shares of companies that are listed outside of the US. For example, we own Unilever PLC via the Unilever ADR listed on NYSE. In case you’re wondering, there are many ADRs available on the NYSE.

With CDRs becoming increasingly more popular, a few readers have emailed me about whether it makes sense to invest in CDRs instead of directly trading US stocks.

What are Canadian Depositary Receipts (CDRs) and what are the benefits? 

Canadian Depositary Receipts are created to allow Canadian investors to buy US stocks in Canadian dollars. For now, CDRs represent shares of US companies but are traded on the NEO Exchange. Since CDRs are traded on a stock exchange, you can view them like traditional stocks. Owning CDRs means you would receive dividends (if the company pays dividends) and have voting rights to the underlying company you’re holding.

What makes CDRs very attractive is the fact that you can buy them in Canadian dollars. You no longer need to convert CAD to USD and pay the extra currency conversion costs or perform Norbert’s Gambit. By buying CDRs in Canadian dollars, it is more cost effective. In addition, there are no management fees associated with CDRs.

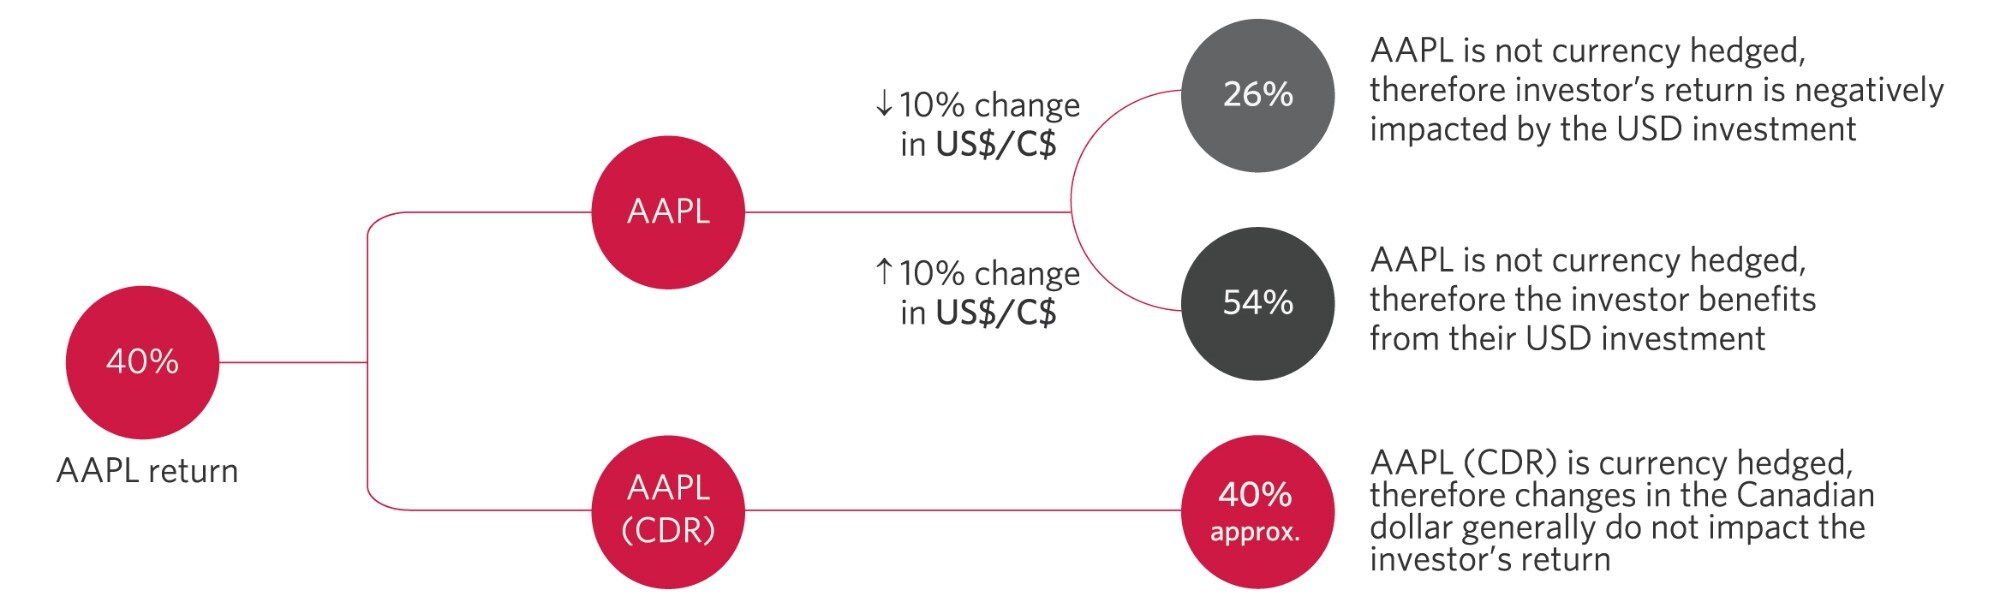
There is a built-in currency hedge in CDRs which eliminates the impact of exchange rate fluctuations over time. Therefore, in theory, the returns of the CDRs are tied directly to the performance of the underlying stocks and you do not have to worry about currency fluctuations.

Since the initial price for each CDR is around $20, CDRs allow Canadian investors to own fractional shares of the underlying stocks at a much lower cost. Essentially, CDRs utilize a ratio called the CDR ratio to represent the number of shares of the underlying stock. The CDR ratio is adjusted automatically daily to account for the currency hedge. If the Canadian dollar increases in value compared to the US dollar, the CDR ratio is adjusted to represent a larger number of underlying shares. The reverse is done when the Canadian dollar weakens.

In other words, rather than buying one share of Amazon at around $3,500 USD or $4,500 CAD, you can hold a few shares of Amazon CDR at around $20 per share at a much lower overall cost. You would still get all the equivalent benefits as a regular Amazon shareholder.

What stocks are available as Canadian Depositary Receipts?

When CDRs were launched in July 2021, CIBC had only a handful of CDR stocks available to trade. Since then, CIBC has added more and more CDR stocks. At the time of writing, there are 18 CDRs available on NEO Exchange:

Symbol Name Price Trades Volume
AMZN AMAZON.COM CDR 21.5 352 53,220
GOOG ALPHABET INC. CDR 25.05 382 73,588
TSLA TESLA, INC. CDR 32.66 1,779 207,169
AAPL APPLE CDR 25.34 342 56,092
NFLX NETFLIX CDR 25.11 125 10,358
MVRS META CDR 18.68 181 8,509
MSFT MICROSOFT CDR 24.94 437 64,181
PYPL PAYPAL CDR 14.6 348 44,410
VISA VISA CDR 20.13 292 33,288
DIS WALT DISNEY CDR 18.32 339 24,460
AMD ADVANCED MICRO DEVICES CDR 28.21 197 9,498
BRK BERKSHIRE HATHAWAY CDR 22.1 147 25,926
COST COSTCO CDR 25.67 155 8,254
IBM IBM CDR 19.24 31 4,391
JPM JPMORGAN CDR 22.48 25 1,143
MA MASTERCARD CDR 21.97 111 14,719
PFE PFIZER CDR 24.79 147 6,796
CRM SALESFORCE.COM CDR

As you can see, there are some really big name, very popular stocks like Apple, Tesla, Alphabet, Netflix, Meta, and Berkshire Hathaway available as CDRs. I am virtually certain that CIBC will add more CDRs on NEO Exchange going forward.

Where can I buy Canadian Depositary Receipts?

Since CDRs are traded like normal stocks on the Canadian stock exchange, you can purchase these CDRs through any online discount broker, such as TD Direct Investing, Questrade, and National Bank Direct Brokerage. You can also trade CDRs on WealthSimple Trade.

Because these CDRs have the same symbols as the US equivalent, you need to pay extra attention to make sure you select the correct stock symbol when purchasing. For example, when you search Apple on WealthSimple Trade, Apple listed on NASDAQ and Apple CDR listed to NEO Exchange both will show up. If you do not pay attention, it is easy to select the Apple listed on NASDAQ and put in a buy order.

It would be a shame to end up buying US listed shares and incur currency exchange fees when that was the very opposite of what you intended to do.

Should you invest in CDRs? 

It is always positive to have options, so I think overall CDRs are great for Canadian investors. Should you invest in CDRs? Well, that depends on your situation and preference. Continue Reading…

Here’s to 2022: Surely it will be better than 2021?

A quick note to say Happy 2022 to all the Hub’s readers and supporters. We’ll be back to our regular blog-a-day rotation on Tuesday.

In the meantime, I’ll point readers to Dale Roberts’ excellent year-end market wrap for MoneySense, which was published Friday.

Click on the highlighted headline to access, but settle down with a coffee before you do: it’s quite a long read: Making Sense of the Markets: 2021.

It’s a thorough long read that looks at all the major market developments each month in 2021 and you’ll also see a number of prescient market calls made by Dale over the last few years, including an early call on Covid-19 itself, an early call on the Energy and Commodities recovery, and several others.

I’ve followed Dale for some years now: he famously tweets as @67Dodge and I now help edit his weekly MoneySense market wrap, seeing as I became MoneySense’s Investing Editor at Large a few months ago.

Don’t forget to contribute to your TFSA ASAP

Oh, while on the subject of MoneySense New Year’s content, I may as well point those to my own column that ran a few days ago: Why contributing to a TFSA is a good (New Year’s) resolution.

In normal years, I would move new money into the TFSA on January 1st but there’s probably no rush this year until Tuesday, Jan. 4, seeing as the Canadian market is closed Monday. (The US will be open that day though).

I’ve not decided exactly what to invest in but it will likely be inflation-related. Going back to Dale Roberts, you can glean a few ideas from his 2021 market wrap: things like short-term TIPS ETFs, or the Purpose Real Assets ETF, or energy/commodity plays.

Personally, I’ve been researching Ray Dalio’s All-Weather portfolio (google it for videos and articles, or try this Seeking Alpha link on it). I’ve concluded that our own family has sufficient US equity exposure but not enough in commodities or TIPS [Treasury Inflation Protected Securities] plays.

Dalio is a bit heavier on fixed-income than most, with a mix of long-term and short-term bonds. His recommended equity exposure is a bit lower, and he suggests 7.5% commodities and 7.5% in gold. Readers may therefore find Friday’s Hub article on gold of interest: A perfect storm for gold.

Every case is different of course. IF I were looking to boost US equity exposure, I’d certainly be considering the new Canadian Depositary Receipts (CDRs), more on which you can read on the Hub early in the new year. If we didn’t already own Berkshire Hathaway, I’d be tempted to add to it with the CDR version of Berkshire, seeing as it pays no dividends and would be a good value counterbalance to high-priced US tech stocks.

So by all means get your $6,000 (if available) into your TFSA early in 2022 but take a few days to figure out how to invest it.

The wild card is certainly Omicron. If you’ve not yet gotten your booster, I highly recommend it.

So again, have a happy, healthy and profitable 2022!