General

Retired Money: How Bond ETF investors can minimize risk of rising rates

My latest MoneySense Retired Money column has just been published: click on the highlighted text to retrieve the full column: Should investors even bother with Bonds any more?

In a nutshell, once again pundits are fretting that interest rates have been so low for so long, that they inevitably must soon begin to rise. And if and when they do, because of the inverse relationship between bond prices and interest rates, any rise in rates may result in  capital losses in the value of the underlying bonds.

In practice, this means choosing (or switching) to bond ETFs with shorter maturities: the risk rises with funds with a lot of bonds maturing five years or more into the future, although of course as long as rates stay as they are or fall, that can be a good thing.

As the column shows, typical aggregate bond ETFs (like ETF All-Star VAB) and equivalents from iShares have suffered losses in the first quarter of 2021. Shorter-term bond ETFs that hold mostly bonds maturing in under five years have been hit less hard. This is one reason why in the US Vanguard Group just unveiled a new Ultra Short Bond ETF that focuses on bonds maturing mostly in two years or less.

The short-term actively managed bond ETF is called the Vanguard Ultra Short Bond ETF. It sports the ticker symbol VUSB, and invests primarily in bonds maturing in zero to two years. It’s considered low-risk, with an MER of 0.10%.

Of course, if you do that (and bear the currency risk involved, at least until Vanguard Canada unveils a C$ version), you may find it less stressful to keep your short-term cash reserves in actual cash, or daily interest savings account, or 1-year or 2-year GICs. None of these pay much but at least they don’t generate red ink, at least in nominal terms. Continue Reading…

Projected Inflation and investment returns

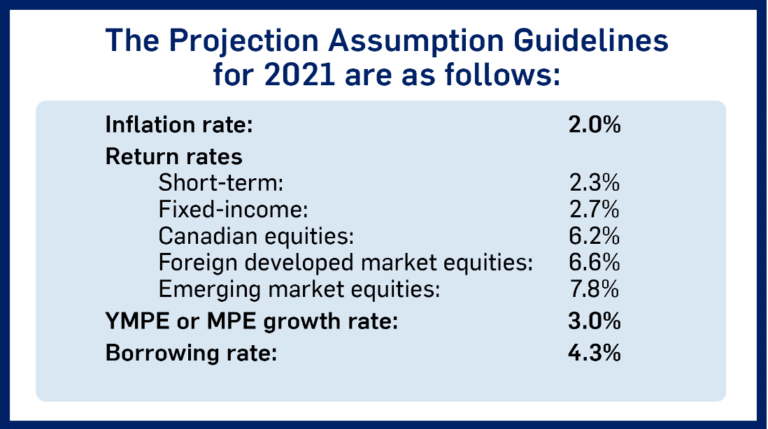
FP Canada issues guidelines every year to help financial planners make long-term financial projections for their clients that are objective and unbiased. The guidelines include assumptions to use for projected inflation and investment returns, wage growth, and borrowing rates. It also includes “probability of survival” tables that show the life expectancy at various ages.

The 2021 Projection Assumption Guidelines were of particular interest because, well, a lot has happened since the 2020 guidelines were published last spring. How should we project inflation and investment returns as we get to the other side of the pandemic and economies start opening up again?

Will we see sustained higher inflation? Should we expect any returns at all from bonds or cash? Should we lower our expectations for future stock market returns?

Remember, these are long-term projections (10+ years). That’s very different than guessing the direction of the stock market for 2021, or predicting whether we’ll see a short burst of inflation in late 2021, early 2022.

The inflation assumption of 2.0% was made by combining the assumptions from the following sources (each weighted at 25%):

  • the average of the inflation assumptions for 30 years (2019 to 2048) used in the most recent QPP actuarial report
  • the average of the inflation assumptions for 30 years (2019 to 2048) used in the most recent CPP actuarial report
  • results of the 2020 FP Canada/IQPF survey. The reduced average was used where the highest and lowest value were removed
  • current Bank of Canada target inflation rate

The result of this calculation is rounded to the nearest 0.10%

Projections for equity returns were set by combining assumptions from the following sources:

  • the average of the assumptions for 30 years (2019 to 2048) used in the most recent QPP actuarial report
  • the average of the assumptions for 30 years (2019 to 2048) used in the most recent CPP actuarial report
  • results of the 2020 FP Canada/IQPF survey. The reduced average was used where the highest and lowest value were removed
  • historic returns over the 50 years ending the previous December 31st (adjusted for inflation).

Equity return assumptions do not include fees.

Unlikely that bonds can replicate their projections of last 50 years

Projections for short-term investments and Canadian fixed-income returns included the assumptions from QPP and CPP, the results of the 2020 FP Canada/IQPF survey, but the 50-year historical average rate was removed in 2020 as a data source. This makes sense given that interest rates were significantly higher than they are now and so it would be impossible for bonds to replicate the performance of the last 50 years. Continue Reading…

The Bubble blowing contest

Wellington-altus.ca/standupadvisors

By John De Goey, CFP, CIM

Special to the Financial Independence Hub

One element of Bullshift that I cannot help but notice is how the finance business has selective and self-serving definitions and explanations that abound when explaining the business to the public.

We’ve already discussed how a 10% move downward is called a “correction”,  but there is no term for a 10% move upward.  Is that an “incorrection”?  Who decides what is correct or not, anyway?

The related term that I often find a bit amusing is the word “bubble.”  Before reading further, take a moment to reflect on what you believe the word means when used in an economic context.  Have you got it?  Don’t read further until you have a firm definition and / or example of ‘bubble’ in your mind.

According to Wikipedia:

An economic bubble or asset bubble (sometimes also referred to as a speculative bubble, a market bubble, a price bubble, a financial bubble, a speculative mania, or a balloon) is a situation in which asset prices appear to be based on implausible or inconsistent views about the future.

Advisors usually acknowledge bubbles after they burst

In my experience, advisors generally only acknowledge bubbles after they burst.  Here’s a fictional story to illustrate that conditional acknowledgement.  Let’s pretend a pair of 12-year-old boys are in the world championships of bubblegum blowing.  The one with the biggest bubble wins, provided the bubble is generally accepted by judges without bursting first.

Three esteemed economists have been hired as judges in the contest. The boys get their gum, chew it and begin to blow their bubbles.  In short order, the bubbles become remarkably large.  Unbelievably large.  And identical in size …. there’s nothing to choose between them!  The judges can’t decide which of the bubbles is bigger … and yet they get bigger still.  Eventually, one of the identical bubbles bursts and the kid with the unburst bubble holds his position for a couple of seconds for the judges to acknowledge that his remains intact: and then inhales the gum back into his mouth, thinking he has won. Continue Reading…

Book Review of Beyond Brochures: an insider’s guide to the Travel Business


By Ruth Snowden

Special to the Financial Independence Hub

Hopefully by summer’s end, travel will start to return.

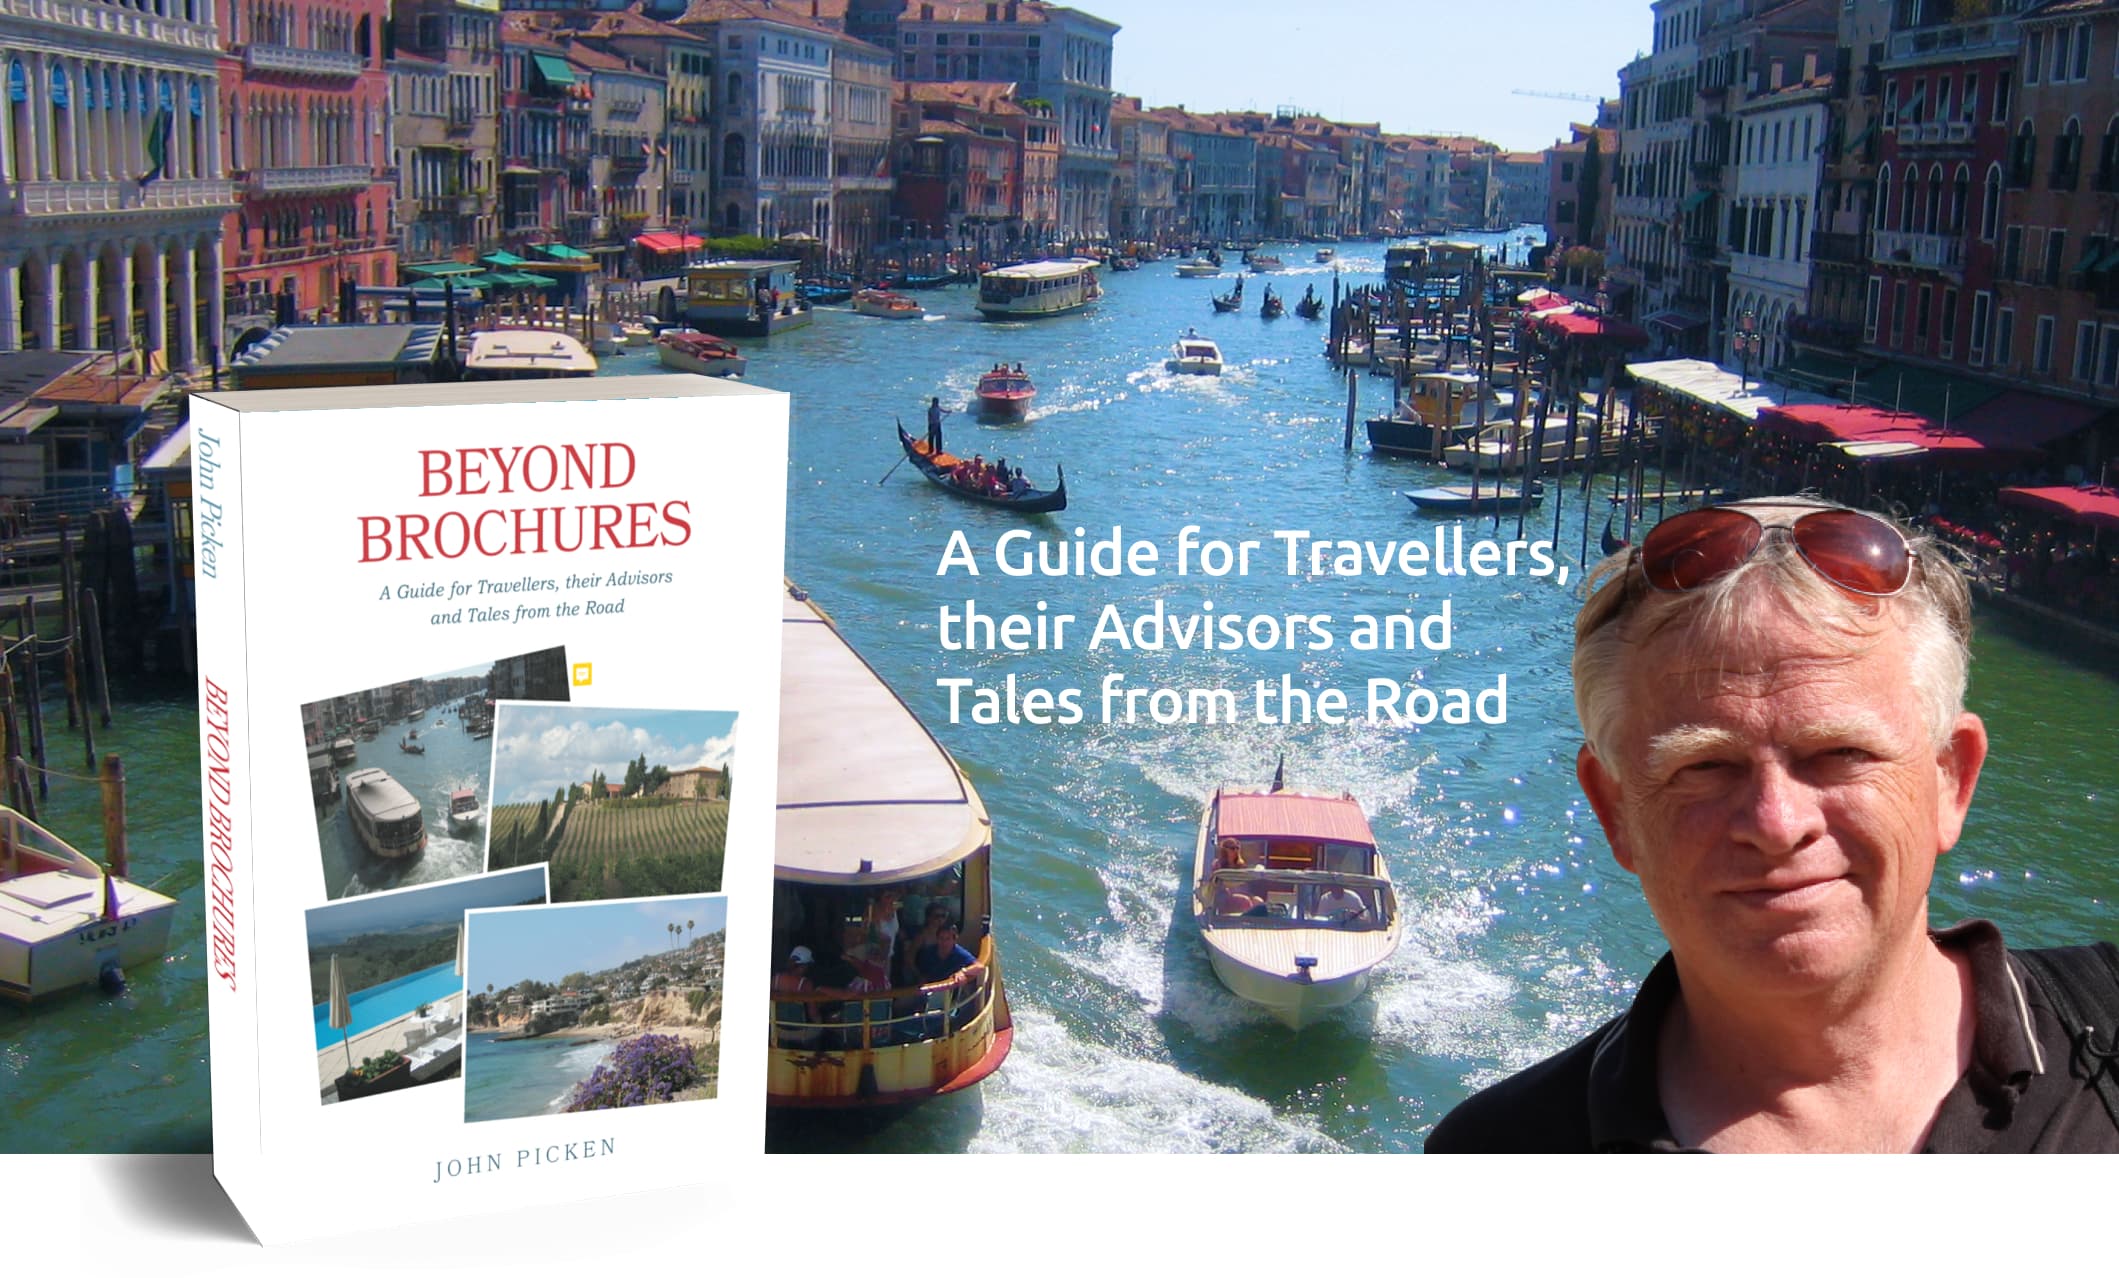
In this little gem of a Traveller’s guide readers will find dozens of precious nuggets, gleaned from the experience of a ‘well-seasoned’ Traveller, written with a light touch, a definite opinion and a good sprinkling of humour.

A bit skeptical at first, I wasn’t sure how anyone could write a book targeted to two different readers, the Traveller and the Travel Advisor, as announced in the introduction.  Within a few pages, though, it was evident that Picken honestly believes that although Travellers and Travel Advisors are on different sides of the same transaction, mutual understanding is a good thing and ‘the more people travel intelligently the better the world should be.’

He then proceeds to draw his readers into the joy of travelling, in 98 chapters: each a succinct one or two pages, divided into three distinct parts: Travellers, Travel Advisors, Travelling.  In every section are valuable hints and suggestions to help Travel Advisors make their customers’ experiences favourable and unforgettable, in a good way.

Building trust is not easy, especially in this world of virtual engagement and digital communication. In Beyond Brochures Picken provides readers with such solid insights that the Traveller reader naturally trusts him and Travel Advisors who follow his advice will be better able to create trust with their customers.

I am another seasoned traveller, having logged thousands of miles on business and leisure travel over many decades, much of which I’ve booked myself and some for which we needed a Travel Advisor.  For both the neophyte Traveller and for someone who has been there and done that, Section A is chock-a-block with important information: government websites; the regulatory environment and jurisdictions governing air travel; demystifying how airlines price seats; and agreeing that in many cases it is easy to book your own hotel room, without the assistance of a Travel Advisor.

Even when booking your own hotel rooms, the author shares great tips on how to use the ubiquitous on-line booking engines and suggests additional actions you can take to save money. Beyond Brochures will make me a better customer of a Travel Advisor and will make my self-directed and self-booked travel more enjoyable.

The philosophy behind why we travel

Early in this section he looks at what we look for in travel that is interesting and enjoyable to us: the philosophy behind why we travel. Continue Reading…

Setting them up for success: Financial Advice for new parents

By Veronica Baxter

Special to the Financial Independence Hub

Are there some things that you wish you knew before you became a parent? Parenting comes with lots of financial responsibilities, and it’s a life-changing experience for many. Suddenly, life is about taking care of yourself, but another person solely depends on you for everything.

Preparation is critical to get ready for this exciting and, perhaps, scary new adventure. It is more helpful to be prepared for the many financial alterations to come. It is estimated that a middle-income American parent spends at least $284,570 (US$)  till the child turns 18 years old.

Most people tend to focus more on their finances after a significant life event. Making the necessary financial plans will save you the stress as you embark on this journey.

Here are vital planners to get you started:

1. )  Make a Household Budget

Having a baby can be expensive. A household budget prevents you from being a spendthrift and also saving for the future. Please write down your steady monthly sources of income and compare them to your monthly expenses.

Adjust your expenses to cover the baby’s needs like diapers, furniture, formula, and other unexpected costs that come up. Also, set some spending limits and do your best to stick to them.

2.)   Get a Life and Disability Insurance Policy

Many new parents question the worthiness of buying life insurance. After all, most don’t think of death. Life insurance comes in handy during such situations to protect you during such worst-case scenarios financially. Life insurance has three different choices:

1.   Whole Life Insurance

This one is lifetime guaranteed. It offers a specified benefit given to your spouse or other beneficiaries upon your death. It accumulates cash value over time and provides the opportunity to earn dividends.

2.   Term Life Insurance

This policy provides coverage for a certain number of years, mostly 15, 20, or 30. If you live longer than the plan, no benefits are paid out since the coverage automatically expires. However, most term policies allow for a continuation after the initial term though at higher charges.

3.   Universal Life Insurance

This policy is a hybrid of the two. It also allows you to set your premiums and death benefits.

Disability insurance becomes a significant refuge when one or both parents cannot work during a disabling injury or illness. No specified amount can never be enough for anyone. That’s why it’s essential to consult a financial expert to help you explore the best option that will fit your financial capability and excellent financial standing.

3.) Write A Will

Thinking about writing a will can be pretty uncomfortable. In a case of untimely death, the state decides how and with whom your assets are shared. The state’s decisions may probably go against your preferences. This is why a will comes in handy to name the guardian to your kids and who will manage your asset distribution when they become adults.

Have the hard conversations of when they are allowed to chip in, to make healthcare and financial decisions. An attorney will give a good outlook that will help you set up a financial trust that aligns with your situation and goals.

4.) Adjust your Emergency Fund

An emergency fund is essential to ensure your household runs smoothly in the event of unforeseen financial circumstances. The amount set aside varies from family to family but should start with three to six months of living expenses. Your emergency fund should now reflect the cost of having a child versus what you initially saved for.

5.)   Include your child in your Medical Insurance Cover

Having a baby is a qualifying life event that allows you to adjust your health plan to enroll your child.  Most of these plans require you to add your child within 30-60 days post-delivery. Try and add up your child as fast as possible to prevent those recurring cash expenses during pediatrician visits.

6.)   Don’t rush to make a Home Upgrade

Some couples equate good parenting to owning a home. However, financial planners advise couples to wait until 3-4 years to make a move. It would be best to have a better outlook of what you want the future to be like within that time.

7.)   Tax Breaks

Childcare can be expensive for many parents. The [US] government offers tax breaks to reduce the tax burden on individuals, allowing them to keep more of the money that they have worked for. Tax breaks are awarded either from claiming deductions or excluding income from your tax returns. Continue Reading…