General

Put that $6,000 of TFSA contribution for 2020 to work as soon as possible


The federal government kept the annual TFSA contribution limit at $6,000 for 2020 – the same annual TFSA limit that we had in 2019. It’s good news for Canadian savers and investors, who as of January 1, 2020, have a cumulative lifetime TFSA contribution limit of $69,500.

The Tax Free Savings Account (TFSA) was introduced in 2009 by the federal conservative government. The TFSA limit started at $5,000 that year: an amount that “will be indexed to inflation and rounded to the nearest $500.”

TFSA Contribution Limit Since 2009

The table below shows the year-by-year historical TFSA contribution limits since 2009.

Year TFSA Contribution Limit
2020 $6,000
2019 $6,000
2018 $5,500
2017 $5,500
2016 $5,500
2015 $10,000
2014 $5,500
2013 $5,500
2012 $5,000
2011 $5,000
2010 $5,000
2009 $5,000
Total $69,500

Note that the maximum lifetime TFSA limit of $69,500 applies only to those who were 18 or older on January 1, 2009. If you were born after 1991 then your lifetime TFSA contribution limit begins the year you turned 18.

You can find your TFSA contribution room information online at CRA My Account, or by calling Tax Information Phone Service (TIPS) at 1-800-267-6999.

TFSA Overview

The Tax Free Savings Account is a flexible vehicle for Canadians to save for a variety of goals. You can contribute every year as long as you’re 18 or older and have a valid social insurance number.

That means young savers can use their TFSA contribution room to establish an emergency fund or save for a down payment on a home. Long-term investors can use their TFSA to invest in ETFs, stocks, or mutual funds and save for the future. Retirees can continue to save inside their TFSA for future consumption or withdraw from their TFSA tax-free without impacting their Old Age Security or GIS.

Unlike an RRSP, any amount contributed to your TFSA is not tax deductible and so it does not reduce your net income for tax purposes.

  • You can contribute room is capped at your TFSA limit. Excess contributions will be taxed at 1 per cent per month
  • Any withdrawals will be added back to your TFSA contribution room at the start of the next calendar year
  • You can replace the amount of your withdrawal in the same year only if you have available TFSA contribution room
  • Any income earned in the account, such as interest, dividends, or capital gains is tax-free upon withdrawal

How to Open a TFSA

Any Canadian 18 or older can open a TFSA. You are allowed to have more than one TFSA account open at any given time, but the total amount you contribute to all of your TFSA accounts cannot exceed your available TFSA contribution room.

To open a TFSA you can contact any bank, credit union, insurance company, trust company or robo-advisor and provide that issuer with your social insurance number and date of birth.

The most common type of TFSA offered is a deposit account such as a high interest savings account or a GIC.

You can also open a self-directed TFSA account where you can build and manage your own savings and investments.

Qualified TFSA Investments

That’s right: you’re not just limited to savings accounts and GICs. Generally, you can put the same investments in your TFSA as you can inside your RRSP. These types of allowable investments include:

  • Cash
  • GICs
  • Mutual funds
  • Stocks
  • Exchange-Traded Funds (ETFs)
  • Bonds

You can contribute foreign currency such as USD to your TFSA. Note that your issuer will convert the funds to Canadian dollars. The total amount of your contribution, in Canadian dollars, cannot exceed your TFSA contribution room.

If you receive dividend income from a foreign country inside your TFSA, the dividend income could be subject to foreign withholding tax.

Gains inside your TFSA

Some investors may be tempted to put risky assets inside their TFSA account to try and earn tax-free capital gains. There are two advantages to this strategy:

  1. Earn tax-free capital gains
  2. Potentially increase your available TFSA contribution room Continue Reading…

The Advantages and Disadvantages of listing your home in the Winter

Photo by unsplash

By Sean Cooper

Special to the Financial Independence Hub

If you’re thinking about selling your home, you probably believe the springtime is the best time to list it. While that may be true, wintertime can also be a good time to sell. Not only are homebuyers usually more serious then, you’re more likely to have more of your realtor’s attention. Let’s look at the advantages and disadvantages of listing your home in the wintertime.

Advantages

More serious Homebuyers

Although more people may visit your place in the spring, not everyone will be serious. Some will be nosey neighbours who want to see inside your place. Others will be people who are just considering buying a home and haven’t made up their mind yet. This means you can spend a lot of time showing off your home with few offers to show for it.

In the wintertime you better believe homebuyers are more serious. Chances are a homebuyer isn’t venturing out into the cold weather unless they really want to buy a home. Likewise, you’re probably listing your home because you’re serious about selling it. Since both parties are serious, you’re more likely to sell your home.

Fewer Sellers to compete against

When you’re listing your home in the springtime, you better make sure it’s looking its best. If your neighbourhood is popular, there could be quite a few homes for sale that you’ll be competing against for the attention of buyers.

Not so in the wintertime. Since there tends to be fewer people selling their homes, if you’re lucky your home might be the only home for sale in the neighbourhood. This doesn’t mean you shouldn’t stage your home and make sure it’s looking its best, but it does mean if someone really wants to buy a home in your neighbourhood, your home will be the only option, which could lead to a higher selling price for you. Continue Reading…

MoneySense: Mutual funds still have a place, especially those without Embedded Compensation

MoneySense.ca: Photo created by snowing – www.freepik.com

MoneySense magazine has begun to publish a package of three mutual fund articles they commissioned me to write. You can find the first article by clicking on the highlighted headline: DSC mutual funds and the future of investment advice. It ran on January 16th.

The first article looks specifically at the gradual decline of the once-ubiquitous DSC sales structure, or Deferred Sales Charge. It recaps recent regularatory developments surrounding DSC, and addresses the related issue of embedded compensation for financial advisors, or so-called Trailer Commissions. These are gradually being eliminated in various Western nations (notably the UK and Australia/NZ) and they are also being phased out in all Canadian provinces, with the conspicuous exception of Ontario.

The lesser-known “Direct-to-Consumer” mutual fund families

When it’s published, the second article will look at two particular “camps” of mutual fund providers: the big-name Embedded Compensation firms you may have heard from (because they can afford to advertise) and a lesser known camp of Direct-to-Consumer managers whose names may be less familiar because they don’t generally have embedded compensation and whose fees are lower and typically mean they don’t have as much money to throw around on big marketing and advertising budgets. The article focusses on four firms in particular you may not have heard of, except through family referrals and word of mouth: Beutel Goodman, Leith Wheeler, Mawer, Steadyhand.

Space precludes mentioning that in the good old days of mutual fund mania (the 90s) there were several other direct-to-consumer firms that either were acquired or are now a shadow of their former selves: the list includes Altamira, Saxon, Sceptre and a few others. We also look at two deep value firms that are still around but get so much publicity about their performance that they can hardly be dubbed as “firms you’ve never heard of.” They are Irwin Michael’s ABC Funds and Francis Chou’s Chou & Associates. Continue Reading…

Borrower and lending practices deepening the burden of debt in Canada  

By Doug Conick, DUCA Credit Union and Chair of Duca Impact Lab

Special to the Financial Independence Hub

Financial institutions play an important role in Canada’s economic well-being. They support growth in personal wealth, job creation and impact the country’s prosperity overall. It is my firm belief that when it comes to the household debt burden of Canadians, there is an even greater role for financial service providers to play. We have a duty to act in the best interest of our clients and proactively contribute to the financial wellbeing of Canadians.

On Wednesday (Jan 15) DUCA Impact Lab released the results of a first-of-its-kind Canadian study to capture the perceptions of Canadian borrowers and lenders, ultimately shining a light on disparities between the two groups. The research uncovers interesting new details about how Canadian borrower and lenders interact with each other and explains how borrowers are impacted by debt. You can find the full report here.

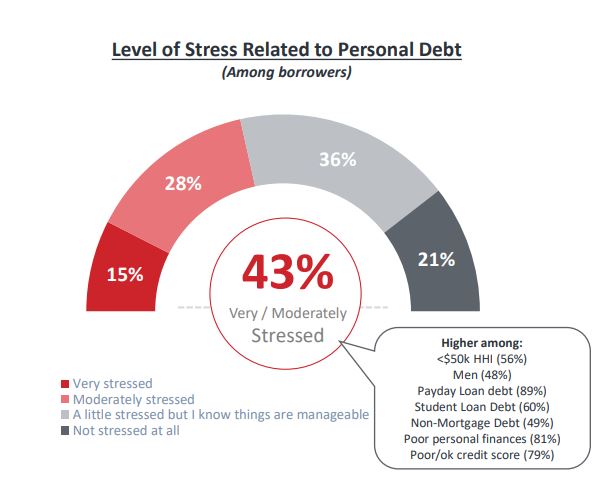
The mounting stress of debt on Canadians

We talked to over 2,000 Canadian borrowers, nearly half of which reported that personal debt has impacted their ability to save and build wealth. It’s concerning that over one-third of borrowers surveyed report avoiding interactions with their financial advisor, despite recent Statistics Canada research which shows Canadians are spending more money than ever on debt payments.

The household debt-service ratio, which represents the percentage of after-tax income used for debt payments, rose to a record 14.96 per cent in the second quarter of 2019. This underscores the increasing need for better understanding among Canadians on how to manage existing debt. Canadians need help but they simply aren’t asking for it.

Our survey also shows debt affects access to healthcare and quality of life. Those surveyed report anxiety, trouble sleeping and poor lifestyle choices like skipping meals, eating unhealthy foods and spending more time alone.

The gap in perception

A quarter of borrowers surveyed say they don’t trust their financial institution to guide them through their debt issues and 37 per cent report avoiding their financial services representatives due to perceived pressures to manage their finances in a way they do not feel comfortable with or because they are recommended products they do not understand. At the same time, 42 per cent of lenders surveyed report they don’t believe their clients fully understand the products they are purchasing.

This demonstrated lack of trust in financial services professionals and gaps in understanding of financial products can lead to a cycle of debt and a missed opportunity to set or prioritize financial goals. Continue Reading…

Q&A with author David Aston about his new book, The Sleep-Easy Retirement Guide

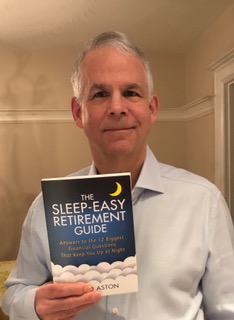
Author David Aston, whose book becomes available today

Today is the formal release date for David Aston’s new book, The Sleep-Easy Retirement Guide. Below is a Q&A I conducted with David to mark the occasion. See also my review of the book at MoneySense that appeared in December, as well as the Hub’s throw to that piece. 

Jon Chevreau: What inspired you to write the book after so many years of writing about Retirement?

David Aston: I have covered most of the key issues in planning for retirement in stand-alone articles I have written over the years.  But I wanted to update that advice for current circumstances and figures, show how all the issues fit together as an interconnected whole, and provide it in a combined reference guide that people could have on their shelf and readily turn to when questions came up.

Q2: What do you think about the FIRE movement?

DA: The Financial Independence Retire Early (FIRE) movement is certainly laudable.  It’s an admirable concept that people should try to achieve Financial Independence as early as possible, which frees them up to do work that is most meaningful to them (rather than being obligated to do work that maximizes income).  As I understand it, it also includes the concept that people should adopt a modest lifestyle that consumes money carefully and wisely without wasting it, which in turn helps make Financial Independence more achievable at a relatively young age.  But from what I’ve read, many of the FIRE scenarios are oriented to extreme examples of people trying to achieve Financial Independence in their 30s.  So it sometimes comes up as a concept for millennials who are looking for Financial Independence as a near-time goal rather than one that is achieved after a long career at work.  That’s only possible for a tiny minority of people.  In my experience, it is far more common for people in their 30s to go through a very difficult financial crunch period where they are struggling to buy a house, then make humungous mortgage payments, and cover the expensive costs of raising kids.  FIRE goals are not realistic and achievable in your 30s for the vast majority of people.  However, the quality of thriftiness and emphasis on saving can be emulated by everyone. I personally think FIRE makes a fair amount of sense for the far more common case of people of average means who might aspire to achieving Financial Independence in their early 60s or possibly their late 50s, but that may not sound particularly appealing to millennials.

Q3: What’s your take on Semi-Retirement and/or Phased Retirement?

DA: The whole world of work for older workers is opening up.  The once accepted norm that people retired from their career job to live a life of leisure close to age 65 has pretty much gone out the window.  There are lots of expanding options for people to do post-career work that is different than their career job.  Often it involves reduced hours, but it can also be full-time work that is less stressful or more fulfilling, or some combination of these attributes.  There are various forms of part-time work, contract work, self-employment, consulting or temp work.  Often it means switching employers or being self-employed, but it can also mean gearing down to reduced hours or a less stressful role with the same employer.   And these post-career options are often started in your early 60s, but they can also happen earlier or later. So there is a vast array of options out there and it’s really up to people to pursue the opportunities that appeal to them the most.

I should mention that “phased retirement” is a term that is sometimes applied to formal corporate programs that allow older employees to adopt a reduced-work schedule or otherwise gear down with the same company prior to full-retirement from their career job.  If you go back about 10 years or so, there was an expectation that these kind of corporate programs would increasingly catch on and be offered by major corporations.  However, it never really caught on as formal corporate programs that are broadly offered to all older employees. What I have seen happen is that you get a lot of these kind of arrangements to offer reduced hours or less stressful/more fulfilling job functions negotiated on an informal, individual basis. They aren’t offered to everybody in the company.  Whether or not an employee can achieve something like that or not depends on the nature of their job, what their boss is looking for, as well as their individual wants and needs. Continue Reading…