General

”Lucky 5” ways to prepare for a post-Divorce financial future

By Meggie Nahatakyan

Special to the Financial Independence Hub

Divorce is not the end of the world. Well, not for you. Being newly divorced signals the beginning of a brand new life and the opportunity for you to redesign and fine tune your life, now as a single person, living under your own terms: the way you want it.

Studies show that many newly divorced women are often left off facing worse financial issues right after divorce. Many are struggling to cope with the demands of being able to provide for themselves and their families, single parenthood, and suffering low self-esteem as well as feeling emotionally battered.

Take stock of your life

Instead of focusing on all the negativity a divorce brings, it is crucial that you take stock of your entire life and place yourself in a positive frame of mind by being grateful for all the great things in your life: like your career, health, family, children, friends, and other support systems you have. After that, make a firm decision to make today the very ‘first’ day of a brand new and better life, looking forward to the future and achieve your fullest potentials in a way that fortifies your core values and beliefs.

Take your time

Take the time out of your usual routine and set your mind free. Relax. Think about how you want your life to look 3 to 5 years from now and what you really need in your life. What if you no longer have to work? What will financial freedom, abundance, wealth, and stability really mean to you?

To bounce back from your past broken relationship and face the future with confidence, you need to be financially stable. You can do this by starting a business that you can juggle while working at home and tending to the kids.

Here are 5 business ideas you can start post-divorce to start empowering yourself:

1.) Start Freelancing

There are websites like People Per Hour or Fiverr that allow you to sell your services for a price. If you are a good writer, bookkeeper, transcriber, or you have specific skill sets that can be outsourced, you can always telecommute and work online. The positive side of freelancing is the work time flexibility; you can work in the given timeframe but the exact hours of work will be up to you.

2.) Start a YouTube Channel

With videos booming these days, people are glued to YouTube and social media. There’s no denying that the future is video. Why not start your own YouTube video channel? Are you a good cook? Start a cooking channel. Are you an expert home DIY hobbyist? Then, let the world know through your very own video channel. There are no limits to what you can do so as long as your channel offers interesting and useful content, you are sure to get viewers and subscribers. Join the bandwagon! Continue Reading…

How Behavioural Economics can help Advisors and Investors meet their goals

By Bernard Letendre 

Special to the Financial Independence Hub

Emotions play a very big part in how we live our lives and have an impact on the decisions we make every day:  including how and when we each choose to invest for our future.

As financial markets move up and down, investors’ emotions follow suit. Emotions and behavioural biases play a role in people’s investment decisions, and often, emotionally-driven investing can leave them with poor returns in the long run. Add a volatile market to the mix and it can make it even harder to reach important investment goals.

Financial advisors know that staying invested during market downturns makes sense. While this recommendation is typically passed on to clients, panic sets in and some clients insist on selling to avoid a loss, despite sound logic and statistics. We all need to be taking a closer look at people’s behaviours and biases and finding ways to counteract them, for the benefit of our investors.

A new Behavioural Economics program for Canadian advisors

With that in mind, Manulife Investment Management wants to help change the investment game for our clients. Through a new partnership with BEworks, a behavioural consulting firm and research institute,we launched a Canadian Behavioural Economics (BE) program to help advisors understand and manage human emotions in volatile markets. The program will be rolled out to advisors over the course of this year with more to come in 2020.

With the help of Dr. David R. Lewis at BEworks, our advisors have access to:

• Scientific-led research and actionable tools to help them and their clients understand the biases in investment decision making Continue Reading…

Retired Money: How the financial industry may use ALDAs and VLPAs as Longevity Insurance

Finance professor Moshe Milevsky welcomes industry’s implementation of academic longevity insurance theories

My latest MoneySense Retired Money column looks at two longevity-related financial products that the industry may develop after the road to them was paved in the March 2019 federal budget. You can access the full column by clicking on the highlighted headline: A new kind of annuity designed to help Canadian retirees live well, for longer.

Once they are created by the industry, hopefully in the next year, these new products will introduce an element of what finance professor Moshe Milevsky has described as “tontine thinking.” In the most extreme example, a tontine — often depicted in fictional work like the film The Wrong Box — features a pool of money that ultimately goes to the person who outlives everyone else. In other words, everyone chips in some money and the person who outlives the rest gets most of the pot. As you can imagine at its most extreme, this can lead to some nefarious scenarios and skulduggery, which is why you occasionally see tontines dramatized in film, as in The Wrong Box, and also TV, as in at least one episode of the Agatha Christie TV adaption of Miss Marple.

Fortunately, the Budget doesn’t propose something quite as dramatic as classic tontines but get used to the following two acronyms if and when the insurance and pension industries start to develop them: ALDA is an acronym for Advanced Life Deferred Annuity.  As of 2020, ALDAs could become an investment option for those currently with money invested in registered plans like RRSPs or RRIFs,  Defined Contribution (DC) Registered Pension Plans and Pooled Registered Pension Plans (PRPPs).

The other type of annuity proposed are Variable Payment Life Annuities (VPLAs), for DC RPPs and PRPPs, which would pool investment risk in groups of at least 10 people. Not quite tontines in the classic academic sense but with the pooling of risk VPLAs certainly have an element of “tontine thinking.”

The budget says a VLPA “will provide payments that vary based on the investment performance of the underlying annuities fund and on the mortality experience of VLPA annuitants.” That means – unlike traditional Defined Benefit pensions – payments could fluctuate year over year.

There is precedent for pooled-risk DC pensions: The University of British Columbia’s faculty pension plan has run such an option for its DC plan members since 1967.

The budget said Ottawa will consult on potential changes to federal pension benefits legislation to accommodate VPLAs for federally regulated PRPPs and DC RPPs, and may need to amend provincial legislation. But it’s ALDAs that initially captured the attention of retirement experts, in part because of its ability to push off taxable minimum RRIF payments.

Up to $150,000 of registered funds can go into an ALDA

An ALDA lets you put up to 25% of qualified registered funds into the purchase of an annuity. The lifetime maximum is $150,000, indexed to inflation after 2020. Beyond that limit you are subject to a penalty tax of 1% per month on the excess portion. Continue Reading…

The best Savings Accounts: based on what you’re saving for

Image from unsplash

By Zack Fenech

Special to the Financial Independence Hub

Saving can be one of the most time-consuming methods of acquiring personal wealth, but if you choose the right account for the right goal, you can make the most out of this lengthy process.

The best way to make your money work over time is by choosing the best savings account based on what you’re saving for.

Picking the best savings account in Canada can maximize your interest return and (in some cases) minimize the amount of taxes you’ll end up having to pay.

How to choose a Savings Account

Generally speaking, there are three main types of savings accounts available: a Registered Retirement Savings Plan (RRSP), a Tax-Free Savings Account (TFSA), and a High-Interest Savings Account (HISA). Considering this, it’s important to establish what exactly it is that you’re saving for, and how much time you’re willing to invest with your money.

While this might seem obvious, it’s a crucial step in the financial planning process. By finding the best savings accounts based on what you’re saving for, you’ll be able to achieve your financial goals much more quickly.

The other side of the coin shows that not choosing the right account can cause roadblocks down the line and sometimes cost you money in early withdrawal fees and taxes.

For example, if your aim is saving on a down payment for your first house, but you have all of your money wrapped up in, let’s say, GICs, you won’t be able to withdraw funds early without a penalty.

But that’s not to say that savings accounts are only propped up for massive investments like homes or your retirement.

Saving up for a car, your wedding, or even a trip can have significant benefits on your interest return, but only if you pick the best savings accounts for your financial goals.

Base choice of Savings Account on what you’re saving for

If you’re unsure what it is you need to save for, consider these two questions before making any firm decisions:

  1. What is my financial situation like right now?
  2. Will I need to access the money I’m investing soon?

Here are a few suggestions why a TFSA, RRSP, and HISA are best suited for your short-term and long-term goals, whatever they may be.

Tax-Free Savings Account (TFSA)

A Tax-Free Savings Account (TFSA) isn’t exactly a savings account. Think of TFSAs as tax shelters. You can put cash, mutual funds, stocks, bonds, or GICs in a TFSA and shelter them from taxes, as long as you remain under your yearly TFSA contribution limit [currently $6,000.]

The contribution limit on your TFSAs depends on how much you contribute each year and the yearly contribution limit allotted by the Canadian Revenue Agency (CRA).

If you exceed your yearly TFSA contribution limit by $2,000, you will not be able to deduct the exceeded amount. Contributions that exceed the $2,000 threshold are subject to a 1% fee for every month the amount remains in your RRSPs.

[Editor’s Note: see reader comment below and refer to this explanation at the Canada.ca website.]

Registered Retirement Savings Plan (RRSP)

A Registered Retirement Savings Plan (RRSP) might seem like a savings account exclusively for retirement planning. However, it’s also one of the best savings accounts for saving for your first home.

An RRSP is somewhat similar to a TFSA. Both shelter your contributions from tax: so long as you remain below your yearly contribution limit. Unlike a TFSA, however, an RRSP does not allow you to withdraw money tax-free. Continue Reading…

Just how steep is housing affordability in Toronto and Vancouver?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

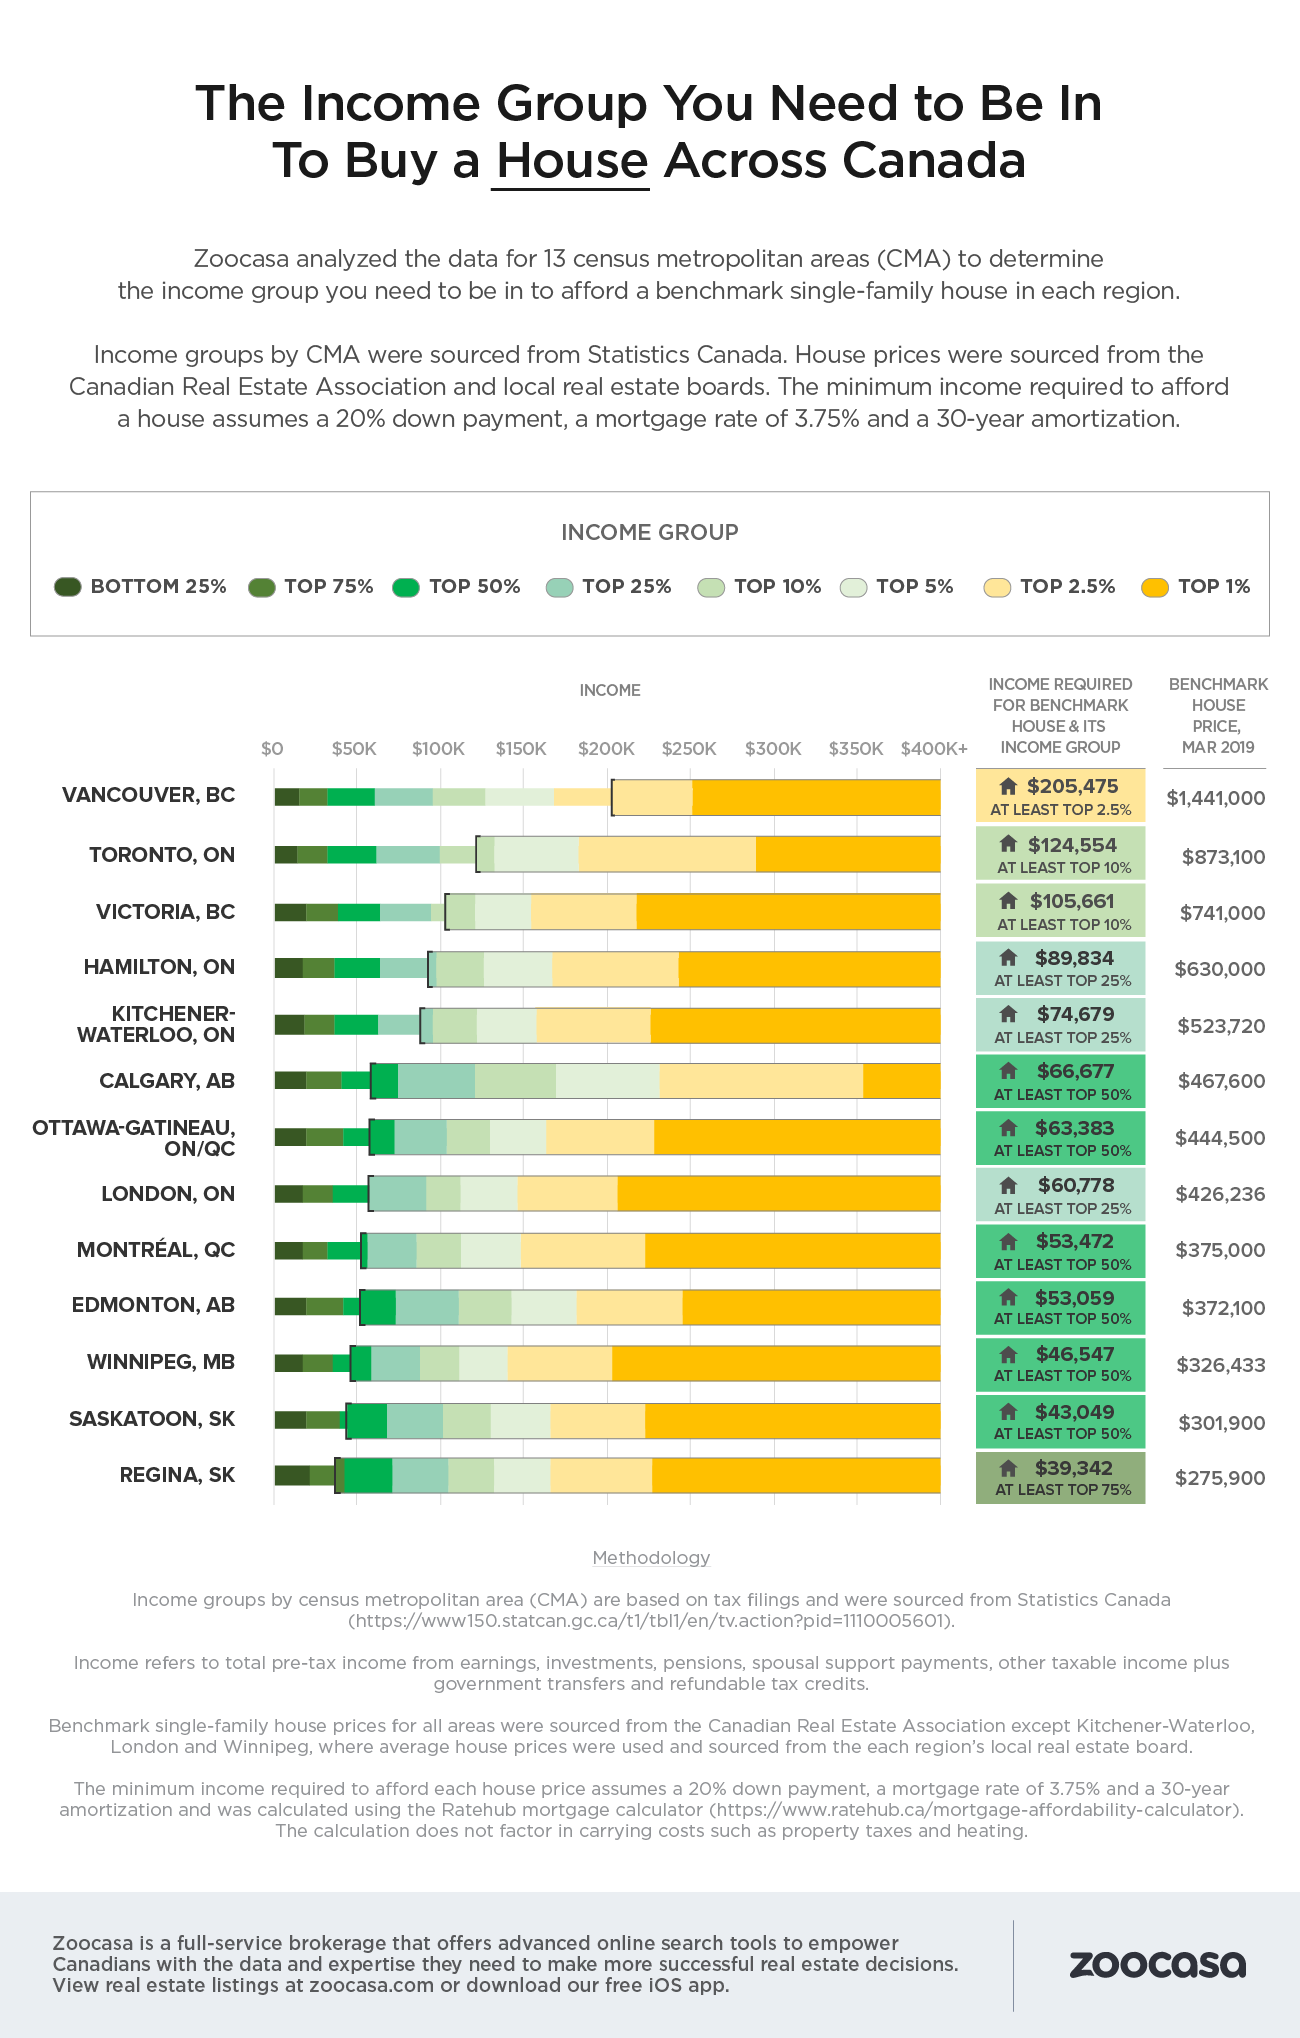
It’s no secret that in order to purchase a house in Toronto or Vancouver, you’ll need to have considerable financial assets; however, a new study from Zoocasa reveals just how elite income earners need to be in order to afford the benchmark single-family home in these cities.

According to the data, which is based on benchmark home prices sourced from the Canadian Real Estate Association as well as income tax filings from Statistics Canada, a Torontonian buyer must be within the top 10% of earners to afford a house priced at $873,100, while only Vancouverites within the top 2.5% could do so for a home priced at $1,441,000.

The numbers also show that prices for entry-level housing, such as condos, remain out of reach for many; buyers must be within the top 25% of income earners to afford the benchmark unit, which costs $656,900 in Vancouver and $522,300 in Toronto, respectively.

Affordability is greater in Southern Ontario, Prairies

However, the study also highlights the comparative affordability in other cities; several of the secondary markets in Ontario, as well as in the Prairie provinces, are much more accessible in terms of housing prices.

For example, those interested in markets within proximity of the GTA, such as Waterloo real estate, need only be within the top 50% to purchase a condo priced at $320,857, though houses are still only in reach for those within the top 25%, at a benchmark of $523,720.

London is also a reasonable alternative for first-time buyers; those looking to purchase a house priced at $426,236 must be within the top 25%, though condos for sale in London are accessible to the top 50%, at $307,359.

Regina takes top spot for affordable Real Estate

Continue Reading…