General

3 Reasons to delay taking CPP until age 70


It might seem counterintuitive to spend down your own retirement savings while at the same time deferring government benefits such as CPP and OAS past age 65. But that’s precisely the type of strategy that can increase your income, save on taxes, and protect against outliving your money.

Here are three reasons to take CPP at age 70:

1.)  Enhanced CPP Benefit – Get up to 42 per cent more!

The standard age to take your CPP benefits is at 65, but you can take your retirement pension as early as 60 or as late as age 70. It might sound like a good idea to take CPP as soon as you’re eligible but you should know that by doing so you’ll forfeit 7.2 per cent each year you receive it before age 65.

Indeed, you’ll get up to 36 per cent less CPP if you take it immediately at age 60 rather than waiting until age 65. That alone should give you pause before deciding to take CPP early. What about taking it later?

There’s a strong incentive for deferring your CPP benefits past age 65. You’ll receive 8.4 per cent more each year that you delay taking CPP (up to a maximum of 42 per cent more if you take CPP at age 70). Note there is no incentive to delay taking CPP after age 70.

Let’s show a quick example. The maximum monthly CPP payment one could receive at age 65 (in 2019) is $1,154.58. Most people don’t receive the maximum, however, so we’ll use the average amount for new beneficiaries, which is $664.41 per month. Now let’s convert that to an annual amount for this example = $7,973.

Suppose our retiree decides to take her CPP benefits at the earliest possible time (age 60). That annual amount will get reduced by 36 per cent, from $7,973 to $5,862: a loss of $2,111 per year.

Now suppose she waits until age 70 to take her CPP benefits. Her annual benefits will increase by 42 per cent, giving her a total of $11,322. That’s an increase of $3,349 per year for her lifetime (indexed to inflation).

2.) Save on taxes from mandatory RRSP withdrawals and OAS clawbacks

Mandatory minimum withdrawal schedules are a big bone of contention for retirees when they convert their RRSP to an RRIF. For larger RRIFs, the mandatory withdrawals can trigger OAS clawbacks and give the retiree more income than he or she needs in a given year.

The gradual increase in the percentage withdrawn also does not jive with our belief in the 4 per cent rule, which will help our money last a lifetime.

You can withdraw from an RRSP at anytime, however, and doing so may come in handy for those who retire early (say between age 55-64). That’s because you can begin modest drawdowns of your retirement savings to augment a workplace pension or other savings to tide you over until age 65 or older.

Tax problems and OAS clawbacks occur when all of your retirement income streams collide simultaneously. But with a delayed CPP approach your RRSP will be much smaller by the time you’re forced to convert it to a RRIF and make minimum mandatory withdrawals. Continue Reading…

The new cost of Divorce

By Elena Hanson

Special to the Financial Independence Hub

On December 22, 2017, the largest U.S. tax reform in over 30 years was signed into law by U.S. President  Donald Trump. The new law brought with it several important changes that affect individual taxpayers who are going through, or have gone through, a divorce. As if divorce isn’t already costly enough!

Prior to the 2017 Tax Reform Act, Section 215 of the U.S. Internal Revenue Code  allowed individual taxpayers to claim alimony payments as a legitimate deduction. The deduction was permitted because section 71(a) of the IRC required the recipient spouse to include the alimony received in his/her adjusted gross income.

For tax purposes, a payment is considered alimony if all of the following criteria are met:

  • Each spouse files a separate return
  • Payment is made in cash (including check or money order)
  • Payment is made to a spouse/former spouse pursuant to a divorce or separation agreement
  • The divorce or separation agreement does not specify that the payment is “not alimony”
  • The spouses/former spouses are not living in the same household when payment is made
  • There is no requirement to continue making payments following the death of the recipient spouse
  • The payment is not treated as child support or a property settlement.

However, under the new Act alimony payments are no longer deductible on U.S. income tax returns if the separation or divorce agreement is executed after December 31, 2018. In addition, the person receiving alimony no longer has to claim these payments on their tax return as part of their gross income.

These changes are permanent, unlike other personal tax measures included in the Tax Reform Act. For those who have agreements in place prior to January 1, 2019, these changes do not apply because the original provisions are grandfathered into the agreement. But, as of January 1, if changes are made to the original agreement, the amended agreement must state that the new rules will not apply, or else they will. In other words, the parties must “opt-in” to the 2017 provisions if there is a modification of the separation or divorce instrument after 2018.

Prior to these changes, the recipient spouse had something of a bargaining chip when negotiating alimony payments. Why? The paying spouse could deduct the payments dollar-for-dollar, making the amount of the alimony payment almost a non-issue as it would come back to the party paying it in the end. Now, it is likely that negotiations will become a more drawn-out affair as divorcing couples struggle to come to an agreement as to what is fair to both parties under the new law.

With any major tax law overhaul, we can always speculate as to the rationale for certain changes. This is one of those situations where there doesn’t seem to be any real benefit to either party and, in fact, simple calculations show that these changes typically result in less after-tax income for both the payor and the payee. Perhaps, U.S. lawmakers were looking out for families by making divorce a less-attractive option in times of trouble?

Overall, these changes are quite a departure from laws that have been in place for decades, and they will bring upheaval and adjustment for divorce lawyers and divorcing taxpayers alike. That’s why it’s so important to consider all the factors, and geographies, involved when drafting up new settlement agreements.

What if recipient spouse resides in Canada?

Now let’s consider a twist to the post-marital arrangement. The spouse paying alimony is a U.S. resident, and the recipient spouse is a nonresident alien, residing in Canada. Domestic laws in Canada remain unchanged in that the Canadian resident receiving alimony from the U.S. must report the income on their Canadian tax return. The result is a situation where the alimony payment is now taxed twice – once in the U.S. where alimony is no longer deductible, and again in Canada where it is taxable income for the recipient. Fortunately, there is relief under the U.S.-Canada Income Tax Convention (1980) which we will call the Treaty. Continue Reading…

Maximizing your CPP benefits: 65 isn’t always the answer

Special to the Financial Independence Hub


As I prepared to write this month’s blog post, I came across an interesting U.S. study exploring how the structure of a company’s self-directed retirement plan might impact its participants’ investment selections.  When investment choices were listed alphabetically, the study found employees were apparently favouring the first few funds on the list. 

Arbitrary?  You bet.  But before we laugh too hard, I’ve noticed similar behaviours closer to home, especially when it comes to making best use of the Canada Pension Plan (CPP).

Assuming you’ve contributed to the CPP during your career, when should you start drawing your benefits?

If you guessed age 65, that’s understandable.  Unless you decide to receive a reduced benefit at a younger age (as early as 60), it’s when Service Canada automatically mails you your CPP application form, as if it’s a given you should fill it out right away.  65 is also the age many younger folks talk about when they dream of the day they’ll stop working.  It’s a number that’s become almost synonymous with “retirement.”  

That said, it’s an entirely arbitrary number when it comes to your own best financial plans. I can cite any number of reasons 65 might or might not be the right number for you.

There’s the prospect of receiving more benefit by waiting until age 70 to get started: currently 42% more than if you start taking it at age 65.  On the flip side, it may make more sense to start drawing a smaller benefit sooner if you are single and in poor health. 

As Financial Post columnist Jason Heath suggests, it’s worth treating your CPP like an RRSP for planning purposes.  To put this in perspective, Heath calculated that a lifetime CPP benefit starting at age 65 and assuming an age 90 life expectancy would be the same as having a $277,000 RRSP, earning 4% per year.  As Heath explains, “Whether you withdraw from other sources, or start your CPP, you are reducing the future income that you can earn from that source.”

So, when is it best to take these significant benefits compared to others that may be available to you?  Instead of simply signing up at age 65 as a given, why not give it some thought (or hire a planner to help you)? Continue Reading…

Key technologies for smarter financial decisions

By Sia Hasan

Special to the Financial Independence Hub

Have you ever considered going paperless? The switch might seem daunting at first, but you will find that electronic options can give you greater freedom and reduced expenses. Whether you’re in business or healthcare, the following technologies will transform your company into a more profitable and financially independent institution.

Cloud Technologies

Cloud computing uses remote servers on the internet for managing data, rather than storing files on a personal computer or external hard drive. When you store data in the cloud, you’ll enjoy higher speeds and greater security. Even if a computer or hard drive crashes, all of your files will still be safely stored in the cloud. In addition, cloud technologies can be a lot cheaper than more traditional options. With cloud computing, you don’t have to pay for unnecessary hardware or software, there will be fewer labor costs. You will also have increased productivity, saving you both time and money.

Strategic Analytics

Implementing analytics can help you better prepare for the future. These forecast technologies use past data to predict future events for your business. With analytics, you can use mathematical approaches to determine the most valuable resources to invest in. Define specific business goals and create strategies that will allow you to test changes on a smaller scale. Analyze costs, advertising, product management, and your ability to meet customer demands. Making small changes now will help you save money in the long-run.

Artificial Intelligence (AI)

Machines are revolutionizing the work industry by learning how to perform human-like tasks. From self-driving cars to bots, AI is making it easier and faster to maximize efficiency. Al offers many benefits, like faster performance, reduced error margins, and lower costs. AI can also achieve breakthroughs by recognizing blind spots and detecting trends. While the initial cost is high, using AI long-term will save you money and increase your efficiency. Instead of replacing workers, AI supplements the work that your employees are already doing. AI can perform smaller tasks, like updating the company website, managing finances, tracking inventory, and finishing payroll. By automating these time-consuming tasks, workers are free to focus on important duties, like human interaction.

Project Management Software

Project management software keeps teams on the same page, while helping managers to better organize tasks and data. Improve your efficiency by storing all of your information in one, easily-accessible location. Simplify team collaboration through crowd-sourced documents and shared to-do lists. Keep track of schedules, budgeting, and resource allocation. Easily communicate questions and concerns to other team members. Track time and expenses, paying attention to areas where you can improve efficiency and cut costs.

Healthcare Software

Going paperless in the healthcare industry has never been easier. With the variety of new software available, you can improve the way you schedule, treat, and communicate with patients. Continue Reading…

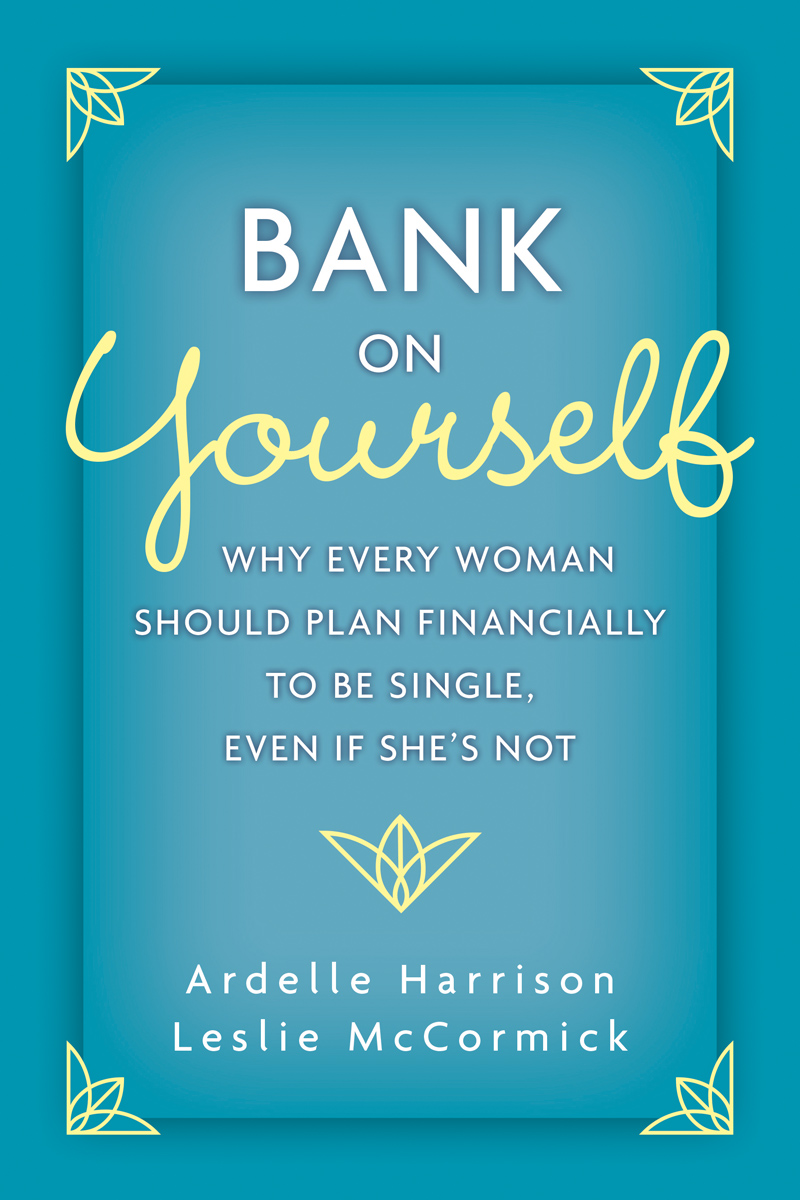
FP: Bank on Yourself — Why women need to focus on Financial Independence with or without a spouse

My latest Financial Post column looks at an upcoming book, Bank on Yourself, which focuses on how Canadian women need to focus on Financial Independence, whether or not they are currently part of a couple. Click on the highlighted headline here for the full review: Why Women shouldn’t let a solo retirement catch them by surprise. The review also appears in the print edition of Tuesday’s Financial Post (page FP 3, April 2, 2019).

The book, which is being published this month (April) by Milner & Associates, is co-authored by a lifelong single woman, Ardelle Harrison, and a financial advisor, Leslie McCormick. McCormick is a Senior Wealth Advisor with Scotia Wealth Management but Ardelle is not a client.

The subtitle says it all: “Why every woman should plan financially to be single. Even if she’s not.”

The authors say 90% of women will end up managing their own finances at some point, whether because of divorce, widowhood or because they never married in the first place. And because women tend to live longer, expect five female centenarians for every male who reaches 100 years (according to the 2016 Canadian census).

Allegedly one of women’s biggest fears is ending up in old age as a “bag lady” destitute on the streets. In fact, 28.3% of unattached women live in poverty and single older women are 13 times more likely to be poor than seniors living in families, the authors say.

They cite Pew Research’s eye-opening finding that when today’s young adults reach their mid 40s and mid 50s, 25% of them are likely to never have been married, and that by then “the chances of marrying for the first time after that age are very small.” (Whether by choice or circumstance.)

But even those who do “couple” earlier in life may not always remain in that state. A 2013 Vanier Institute of the Family report says 41% of Canadian marriages end before their 30th wedding anniversary. 68% of divorced couples cited fighting over money as the top reason for the split. 2011 Canadian census data shows the average age at which women are widowed is 56.

Multiple Streams of Income

A key concept emphasized throughout the book is having Multiple Streams of Income, at least three in Retirement. Employment income is the springboard to other income streams,  including employer pensions.

A second is government benefits unlike CPP and OAS. Other streams are business, investment and real estate income, and annuities. Home owners have a potential backup in their home equity, although the authors rightly say “Debt is not something you want in retirement.”

I asked McCormick if these principles apply equally to single men. General financial planning principles apply across genders, she replied, but women have longer life expectancies, so when you add the gender wage cap, it’s harder for women to build wealth. Female baby boomers can expect to outlive their spouses by 10 to 15 years, “yet so few women plan for it.” While 31% of women view themselves as being financially knowledgeable, 80% of men do.  Her hope is the book will help bridge that gap. So might a planning tool at her Plan Single website (www.Plansingle.ca).


Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.