General

Retired Money: Tontines moving from academia to Retirement marketplace

Annuity and Tontine expert Moshe Milevsky

My latest MoneySense Retired Money column, just published, looks at how the 17th century “tontine” scheme may help solve 21st century angst about outliving your money in Retirement. Click on this headline to retrieve the whole article: Why Ottawa needs to push for tontine-type annuities.

We have described Moshe’s pioneering work in annuities and tontines before: the York University finance professor and prolific author has published entire books on tontines and annuities. As he outlines in Pensionize Your Nest Egg, Milevsky has always emphasized the distinction between what he calls “real” pensions (guaranteed-for-life Defined Benefit pensions) and capital-appreciation vehicles like RRSPs or Defined Contribution plans, which have to be “pensionized” (or “annuitized”)before they can be considered to be “real” pensions.

Milevsky and three fellow Canadian co-authors have just published a paper partially funded by the pension section of the U.S. Society of Actuaries,entitled Annuities versus Tontines in the 21stCentury: A Canadian Case Study. (The other authors are Thomas Salisbury, Gabriela Gonzales and Hanna Jankowski). In it they make the case for the reintroduction of retirement investment income tontines (RITs) into the modern financial supermarket.

For those who haven’t seen the film The Wrong Box, tontines are mortality-linked investments that superficially resemble life annuities but were quite popular in Europe in the 17thand 18thcentury and later America. But they fell into disrepute by the early 20thcentury, in part because of the kind of sordid image they received, often popularized by novels and films like The Wrong Box. The “longest-living” winner takes the pot, which is why creative artists have often used this as a plot device involving skulduggery.
In essence, tontines pool capital and distribute all the capital and investment gains to those who live the longest: those unlucky enough to die early forfeit the capital (i.e. their heirs forfeit it), while those who live the longest benefit with super returns.

While a tontine revival could make sense around the world – the pension and longevity trends are almost universal – they make particular sense in Canada. The authors state they “believe that Canada has a dearth of products for hedging personal risk, compared to the U.S. market.” They know of no Canadian insurance company that offers a true deferred income annuity (DIA or ALDA), not do they offer a variable income annuity or equity-indexed annuities with living benefits: all available in the US. The closest we have are segregated funds, and they really aren’t that great as far as guaranteeing lifetime income, Milevsky told me. Continue Reading…

4 investment strategies every stock investor should consider

By Sia Hasan

Special to the Financial Independence Hub

Portfolio managers and analysts believe that no one investment strategy outweighs the rest. Instead, every game plan has its unique strengths and weaknesses. As such, it’s up to investors to choose the tactic that best works for them. It’s worth taking time to learn to develop strategies if you are considering investing in bonds or stocks. Some of the stock and bond investment strategies include quantitative, algorithmic trading, value investing, growth strategy, GARP investing, and collar options strategy.

Quantitative, Algorithmic Trading

Quantitative, algorithmic Trading involves selection of an investment based on mathematical analysis. In fact, investors don’t need to consider other factors such as how a business operates. All they need is to analyze different variables that correlate with each other to create an algorithm that can help predict how stock or bond prices will change over time. Quantitative, algorithmic trading is one of the newest investment strategies that have become popular in the past few years. It allows investors to engage in different investment styles and come up with a thesis, variables and set of data that they can use to identify and exploit market inefficiencies. It’s up to the investors to develop a model, test it with historical data, and implement it to see if it works. Algorithmic trading is ideal for investors with some mathematical and computer programming background.

Value Investing

Value investing is a strategy where an investor buys stocks that are grossly undervalued. Buying stocks that trade for less value than their net assets and cash profits allows the investor to limit the amount of money he or she could lose on an investment. The strategy is ideal for investors who believe that the market overreacts to emerging trends, resulting in a price decline that doesn’t correspond with an investor’s long-term fundamentals. The stock price could decline beyond its fair value when a market overreacts to bad news. As such, an investor can take advantage and buy stock, and wait for its value to return to its optimal level.

Growth Investing

Growth investing is a more aggressive investment strategy that focuses on capital appreciation. It involves investment in stocks or bonds that exhibit signs of growth even if their current share price seems high. Investors are anticipating that stocks and bonds will grow in value and offset the premium they will pay for the investment. However, this is an aggressive investment approach that investors regard as both highly rewarding and highly risky. Investors have to be confident about the growth and competitive strength of a company to justify that its share value will grow in the future. Growth investing strategy is ideal for futurists who are confident that stocks or bonds will increase in value over time.

Growth at Reasonable Price Investing (GARP)

GARP (Growth at a Reasonable Price) is a hybrid of growth and value investing strategies. However, analysts have often stated that value and growth-based investment strategies are joined at the hip. In fact, there is little difference between growth and value-based investment strategies. The growth of a company will always impact its fair value. It is far better to buy highly valued shares at a fair price than to buy undervalued shares at a lower price. GARP strategies enable investors to identify stocks and bonds that are priced reasonably. As such, they can benefit from the stock’s growth potential as well as enjoy protection against price deviation.

It’s important to note there is no one investment strategy that is best for everyone. What matters is whether the investment tactic is a good fit for your company or not. However, nothing is worse than being inconsistent with each of your investment strategies. You can hardly find the source of error that could be increasing your costs if you invest in different philosophy each time. However, it is vital to minimize your trading costs irrespective of the investment strategy you adopt.


Sia Hasan is a tech entrepreneur by day, and a freelance writer by night. Her passion lies in business technology, efficient and sleek programming, and customer relationship management. When she doesn’t have her nose pressed against her computer screen, you can find her spending time with the loves of her life, her two dogs, Pixel and Vector.

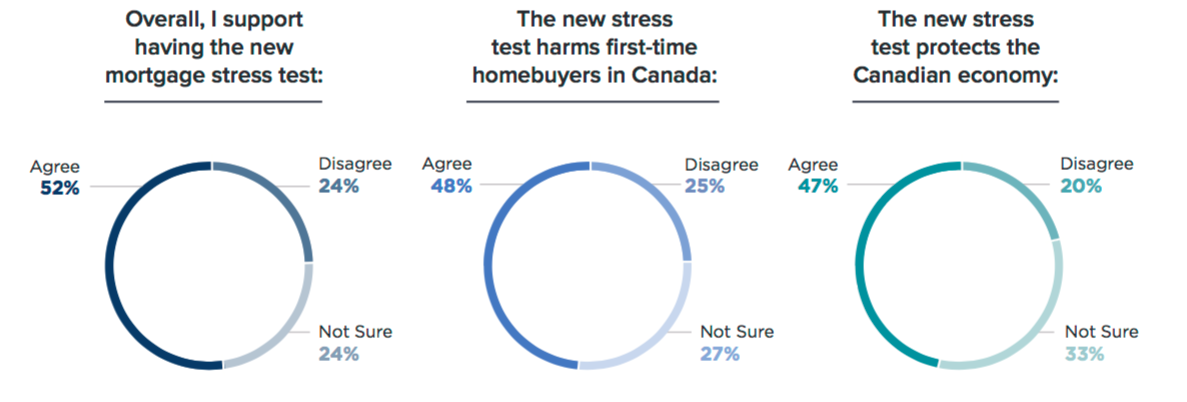
52% of Canadians support new Mortgage Rules

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

It has now been four full months since Guideline B-20 – a slew of new mortgage qualification requirements – hit Canada’s borrowers in the wallet.

Under the new regulations, those applying for a new mortgage, and who are paying at least 20 per cent down on their home purchase, must qualify at either the Bank of Canada’s benchmark rate (currently 5.14 per cent), or their mortgage contract rate plus 2 per cent, whichever is higher. While the mortgage payments will be made at the borrower’s actual rate, this is the government’s way of shock-proofing lending, ensuring borrowers can still make their payments should rates rise exponentially.

Experts have stated that Guideline B-20 would slash the average home buying budget by 20 per cent, and knock as many as 10 per cent of buyers out of the market altogether. Market conditions have proven softer in the months following the new rule, with national prices falling 10.4 per cent in March, and an exodus from more expensive home types to the lower end of the market, such as condos for sale in Toronto.

But have they truly dissuaded Canadian home buyers from entering the real estate market?

To find out, Zoocasa polled just over 1,400 Canadians from all provinces, as part of the second-annual Housing Trends Survey. Respondents were asked for their sentiments and experiences as a result of B-20, and the overall rising interest rate environment.

Majority not impacted by Stress Test

According to the data, the majority of recent home buyers have withstood the introduction of Guideline B-20 unscathed; of those who purchased a home between October 2017 (when the new rules were first announced) and March 2018, 48 per cent say there was no change whatsoever to their buying timeline.

However, 27 per cent reported they rushed their purchase as a result, while 6 per cent delayed buying. An additional 19 per cent who bought homes weren’t actually aware of the new mortgage rules at all.

Also, the impact has been more significant on those who have no yet purchased their home: while 40 per cent stated B-20 hasn’t changed their mind about buying, 15 per cent will delay their home purchase, and a full 15 per cent now feel homeownership is out of reach altogether. Continue Reading…

Do you really need Dental Insurance?

By Wally Thompson

Special to the Financial Independence Hub

April was Oral Health Month in Canada and while we should take care of our oral hygiene year-round, past studies show that a whopping 6 million Canadians avoid the dentist because they simply can’t afford it.

When it comes to dental insurance, a new survey from Manulife revealed:

  • More than one third of Canadians do not have access to private health and/or dental insurance coverage
  • When choosing coverage, 42% said the most determining factor is the cost of premiums, followed by companies offering a variety of coverage options (36%)
  • While 30% of Canadians make sure they visit the dentist for regular check-ups, 29% hate having to do it
  • For those who have visited the dentist, 52% admit to feeling guilty about their oral care habits

A visit to the dentist may not be everyone’s idea of fun but regular visits are beneficial for our overall health. Getting dental insurance for you and your loved ones helps make sure the right care is available on a regular basis and when there is an emergency.

Here are four common misconceptions and what to look for when purchasing dental insurance in Canada:

I’m healthy so there’s no need for dental insurance

If you don’t have dental insurance, don’t wait until you need to deal with a tooth infection, a chipped tooth or to be in serious need of cleaning to start looking into your coverage options. Individuals and their families should consider a plan when they are healthy in order to protect themselves from conditions that may arise in the future. Individuals will need to do a complete assessment on their needs to determine their overall supplemental health insurance coverage. Health status, affordability and the types of coverage are a few key factors that would be part of your overall needs assessments.

If you work with a financial advisor, he or she can also help you and your family complete your overall needs assessment and complete the purchase. You should also ask your advisor how these premiums can be treated as a business expense for your annual tax returns.

I can’t afford insurance

Continue Reading…

Is it wise to sell in May and go away?

“Sometimes it’s necessary to go a long distance out of the way in order to come back a short distance correctly.” — Edward Albee (1928–2016), American playwright

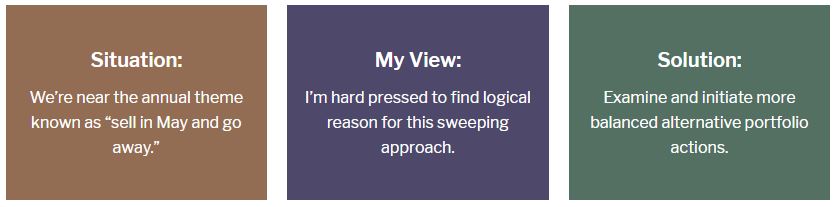
Investing plans that pursue flavours of “sell in May and go away” are not vanishing anytime soon. Simply said, the catchy tune is about to ignite the annual rounds once again. Strategies that believe stock investing from November to April have better prospects than other months.

Keen followers of this practice typically sell their equities around May, such as stocks, mutual funds and ETFs. They then repurchase equity investments near November.

“I don’t recommend clearing the deck willy-nilly. Drastic actions are seldom wise replacements for long-term strategy.”

I’m fully on board with the excitement of getting away to a variety of travel destinations. That is the “go away” part. On the other hand, I just don’t buy into the questionable wisdom of selling the nest egg. For me, the “sell in May” part needs much closer scrutiny. Particularly, outlays of disposition and acquisition. Income tax implications also play a part.

Let’s be clear about the strategy. An investor unloads the entire portfolio, then acquires the new version a few months later. This process is repeated year after year, after year. Sounds like quite a heap of cash to shell out for transactions and tax implications.

Potential pitfalls

If only investing were that simple! Examining these pointers helps assess the prudence of wholesale selling: Continue Reading…