General

Are you financially ready to buy your first home?

By Allan Tran

Special to the Financial Independence Hub

Buying a home is usually the biggest investment you’ll make. Can you afford it?

Recent surveys show that potential buyers are concerned about interest rate increases and new federal lending guidelines. Many people are delaying their home purchases. It can be hard to know when to take the plunge or hit pause. Try these exercises:

Simulate the total expense

When talking to mortgage brokers and real estate agents, you can get preoccupied with rates, what you can get approved for, and listing prices. Those matter, but figure out the bottom line. Can you swing the total costs and still live your life?

Calculate your expected fixed home ownership costs: mortgage payment, property tax, home insurance, utilities, etc. Take that total and compare it to what you’re paying now for rent. The difference is what you’ll need to be able to cover.

Now, set that amount aside every month for a year. That’s long enough to experience all the ups and downs of your annual expenses. See whether you can handlethe monthly savings for the home you want for a sustained period

Take a hard look at your spending

Saving for a home, then managing the ongoing expense, can require a shift in spending habits. You can’t do that without a handle on where you actually spend your money.

Review the last three months of your credit-card statements and other bills. Look at wants versus needs. Think about what costs you could have avoided and how those add up. For instance, many costs that we tap a card for are variable. You can likely avoid some. Try and park that money into savings.

Another strategy is to force savings by tying it into spending. Say you spend $20 a week on coffee. Yes, you can save $1,000 a year by foregoing that. But you want coffee. Well, you also want a home. How about putting the equivalent towards it? It’s just a way of disciplining yourself to save for a bigger dream.

Force accountability

If you’re buying a home with a partner or spouse, get a joint account where you can’t pull out money without both signing off. This will help you think twice about spending and hold each other accountable.

Many couples have different spending and savings habits. The point is to train you to have honest conversations about finances. If you’re going to own a home together, you need to be on the same financial page before, during and after the purchase.

Stress test yourself

The Office of the Superintendent of Financial Institutions has new rules around mortgage underwriting. Potential home buyers must be able to handle a minimum qualifying rate: the greater of the five-year Bank of Canada benchmark rate, or the contracted mortgage rate plus two percentage points. Continue Reading…
What’s your real Risk Tolerance? Chinese Face Reading tells us Listen to your Ears

By Jane Hawley Edward

Special to the Financial Independence Hub

My Google search for “choosing a financial advisor” yielded more than 30 million hits. It appears to be a popular topic. The recommendations over the first 20 pages were variations on:

Education and Experience

Compensation and potential conflicts of interest

Investment suitability to the client

Yet I propose another characteristic for consideration; one that can quickly help assess one’s risk tolerance and show whether a client and advisor are compatible.

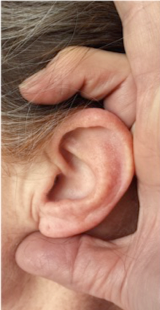
It comes from the ancient Chinese science of Face Reading, where ears are the physical feature that shows how much innate courage and risk-taking ability a person has. The larger the ear, the more comfortable they are gambling physically, in their choice of work or taking risks with money.

To understand the kind of risk-taking you can naturally handle, all you have to do is measure the size of your ear.  Measure it by holding your thumb and index finger in a “C” up to your ear. If it matches in size, you have a small ear.  A large ear is the size of your thumb and middle finger formed into a “C”. A medium ear is between those two sizes.

The broader your ear is across the top, the more comfortable you are with financial and emotional risk.  Chances are that you would be the type who would be more willing to try aggressive growth stocks or volatile markets for potentially larger gains.

In contrast, if your ear is narrow across the top, you’d tend to be a conservative and cautious investor. Your preference would be to invest in safer low-risk vehicles because your main goal is to preserve savings because you feel the pain of losses more intensely than the comfort of gains.

Matching to your financial advisor’s

That’s where matchmaking our ears to our financial advisor’s gets interesting.  A client with cautious, narrow ears may be most comfortable with a similarly narrow-eared, like-minded advisor.  But there’s merit in matching opposite traits; a wide-eared advisor could construct a portfolio that offers protection plus opportunity for moderate growth.  Or a narrow-eared advisor could help curb a high-risk tolerant client from gambling on a poorly diversified portfolio or too speculative an investment.  In either case, together they could temper each other’s risk taking appetite.   The main point is to know what each brings to the equation. Continue Reading…

How Finance Apps & Online Tools will revolutionize Millennial Financial Planning

By Drew Hayles 

Special to the Financial Independendence Hub

When you’re young, you feel like nothing can stop you. You’re in charge of your own destiny.

Things might look different in hindsight, but don’t worry about that now. The most important thing you can do right now is set in motion a plan to achieve financial independence as soon as possible. With the means to do what you want, when you want, you’ll open doors you never even knew existed.

Before you begin in earnest, make sure you have the right digital tools and apps in your corner. These user-friendly resources all have their place in a coherent, comprehensive financial independence plan, provided you use them properly and consistently.

Perhaps you’re using a few already.

 Digital Budgeting Tools: All Your Money in One Place

 This list of the “best simple and free budgeting tools” doesn’t get to actual digital solutions until the third entry, when it calls out the trusty old Excel spreadsheet.

If you’re in the market for something a bit more robust and hands-off than a wall of spreadsheet cells, consider later entries like Mint or PearBudget (which, to be fair, began life as an Excel tool).

These aren’t professional-grade tools by any means, but they’re nevertheless robust enough to accommodate basic household budgeting and ensure that you spend well less than you earn. Remember to download mobile versions and link your bank accounts for automated cash flow tracking.

 Automated Savings Apps: Ditch the Reminders

 Tired of remembering (or forgetting) to make regular savings deposits? Take the uncertainty out of the process with automated savings apps that quietly transfer small sums to your savings accounts without any input on your end.

Tools like Digit exist wholly for this purpose. More robust online banking solutions like Chime Bank typically have built-in automated savings features that round up every debit transaction to the nearest dollar and sock away the difference

 Educational Videos: DIY, But for Money

 Are you a DIYer at heart? You can learn a lot from high-quality investing and financial education videos. After all, there’s no need to pay for entry-level information and strategic advice when you’ve got a YouTube account to your name. If you need help or want to learn more about specific topics, you can always go straight to the source with questions.

Lightweight Accounting Platforms for Entrepreneurs   Continue Reading…

Building flexibility into your Retirement Plan

Prospective retirees want a simple formula for making their retirement plan. There are hundreds of calculators that will crank out numbers showing how many years until you can retire, how much you need to save, and how long your money will last. It’s a good place to start, but don’t stake your entire future on the results.

You spend decades preparing for a comfortable retirement, planning to spend time playing golf or travelling the world. But, if a financial disaster strikes, those dreams may not translate into reality. Unexpected financial crises that disrupt savings are far more common than anticipated.

If your retirement plan only works as long as nothing goes seriously wrong, you are not properly prepared for retirement. It’s important to plan ahead. Knowing how you will handle certain crises can go a long way toward minimizing the financial fallout.

What kind of surprises can derail a retirement plan?

They can include:

  • Lost income.
  • Providing financial support to an adult family member.
  • Paying significant health care costs for yourself or a family member.
  • Divorce or loss of spouse.
  • Investment underperformance, or investment fraud.
  • Unanticipated major home repairs, especially after a natural disaster.
  • Changes in tax rates and legislation.

Let’s look at three situations that can derail your financial plan.

1.) Unpredicted early retirement

How would your retirement plan be impacted if you lost your job due to company downsizing? Do you have the marketability to find comparable employment elsewhere in a reasonable amount of time? Would you receive the same salary, or be forced to accept a lesser amount?

Lost income might be due to forced retirement for health reasons.

Not only would there be loss of income, you might have to dip into your savings earlier than expected. There could be expensive medical costs not covered by your provincial health plan.

2.) Providing financial support to family members

People over the age of 50 have the opportunity to beef up their retirement accounts with additional contributions. What if your child is forced to return home and/or require financial support due to a job loss, divorce, or health crisis? There may not be room in the budget to make those catch-up contributions.

As life expectancies increase, aging parents may require some expensive medical support or long-term care.

A lot of people currently care for two generations of family members.

3.) Investing challenges

Key investment objectives for retires are income and preservation of capital. Liquidity is important. Growth as well.

Investment challenges facing retirees include: Continue Reading…

Toronto Housing: Implications for Canadian Banks

By Jeff Weniger, CFA, WisdomTree Investments 

Special to the Financial Independence Hub

Is the footing getting shaky in Ontario housing? The Teranet–National Bank National Composite House Price Index for Toronto rose 272.8% from its inception in July 1998 to the peak last summer. Everyone knows nothing of the sort happened to wages. The average Canadian earned $579 a week back then and $988 today, a 69% change.1 Something is amiss, and maybe the bell was rung in July 2017.

The Toronto housing market appears to have turned on a dime, and the home price index is off 7.3% through 2/28/2018 (figure 1). Aside from the index’s 10.9% fall during the global financial crisis, this is the sharpest decline in Toronto residential real estate since the index’s inception in 1998.

Figure 1: Teranet–National Bank National Composite House Price Index, Toronto

When home prices quadruple in the span of one generation, with much of the appreciation in recent years taking on a “just buy before getting priced out forever” mentality, the natural concern is that  the 7% drawdown might be just a taste of what is yet to come.

This is where we are reminded that MSCI Canada has 43% of its weight in financials,2 and almost all of that is in the big banks. Canada is unique in that its banking system, for better or worse, is concentrated in the five national champions.3 The U.S. has 4,888 commercial banks,4 so major indexes like the S&P 500 do not have the same domination of Bank of America or Wells Fargo as the big players do on the TSX. In fact, in the developed world, Canada’s degree of sector concentration is akin to only Hong Kong, with hardly any other industrialized economies as reliant on so few key sectors. Continue Reading…