General

Financial Planning for blended families

By Scott Evans

Special to the Financial Independence Hub

It may not be the most romantic topic to discuss on Valentine’s Day but it may be the most valuable for long-term happiness in your relationship. 40% of blended families admit to not discussing finances before moving in together but when you blend families there’s a long list of items for you and your partner to figure out. Your finances should be near the top. Dealing with financial issues early can go a long way to ensuring this next chapter in your life is all you want it to be.

Holding property – together or apart?

One of the first decisions you’ll have to make as a couple is whether to own property jointly or in separate names. What you decide will affect the way you manage money now, and determine how your wealth is passed on.

Some property like an RRSP or TFSA must be registered solely. But for other assets, including investment accounts, GICs or real estate, you have the option of sharing ownership.

Arranging joint title is handy where unrestricted, convenient access for either party is important; daily bank accounts are an example. It can also make sense if you want to share your property with your partner now and leave those assets to them when you die. Holding property as joint tenants with right of survivorship ensures ownership will transition smoothly to the surviving spouse. However, tenancy if your partner makes bad financial choices it could also impact you and your creditworthiness.

Keeping title separate is an option if you’re concerned about clearly tracing who brought which assets, or debts, to the relationship. On the other hand, if you still prefer sharing ownership with your significant other there’s an alternative: holding property as tenants-in-common.

Let’s say you bring assets from a prior relationship which you plan to leave to your children from that earlier union, rather than to your new partner or stepchildren. Instead of having title transferred automatically to your spouse upon your death as would happen in a joint tenancy, as tenants-in-common your share of the property remains part of your estate, meaning title can be passed to your heirs according to your will. You won’t be relying on your new spouse to ultimately decide your children’s inheritance.

Don’t forget to update important documents

Review key documents to ensure they still reflect your intentions. Including:

  • Beneficiary and related designations for RRSPs, RRIFs, TFSAs, life insurance policies and workplace pensions. At death, registered investments can generally transfer to your new spouse without immediate tax consequences.
  • Your will. In BC and Alberta, a will is no longer automatically revoked by marriage. That means any directives stated in your will, including those made benefitting your ex-spouse, stay in effect unless you alter them. However, no matter where you live, it is important to review your will during life events such as divorce or marriage.
  • Power of attorney and executor appointments. In blended family situations where adult children are involved, consider naming a third-party professional like a lawyer or trust company to these roles. Doing so can help head off any family conflict, while ensuring duties are carried out properly.

Options for estate planning
Continue Reading…

Why Saving alone isn’t the best way to Financial Independence

By Elizabeth Lee

Special to the Financial Independence Hub

You’ve been told your entire life that you’ll never be able to accomplish anything unless you have a padded savings account: that every penny you can possibly set aside should be set aside, and you should absolutely never touch it.

You may even have been told that this is the only way you’ll become financially independent. You’ve been told wrong.

Saving is crucially important, but it’s important for entirely different reasons. You shouldn’t go out and spend your nest egg indiscriminately, but spending some of it might help you create a better and stronger independent (“findependent”) future. It all depends on how you strategize.

Why Saving is important

If you’re spending all your money as it comes in, what happens when you run into an expense you didn’t know was coming? Your car breaks down, you need to travel for a destination wedding, you find out you’re going to be a parent a little earlier than you’d originally planned, or you need to go to urgent care for a pesky sinus infection. How are you going to pay for it?

You had no idea that it was coming, and you didn’t budget for any of those things, because you didn’t know they were coming. If you don’t have savings, you might be set so far off track that you need to borrow to pay the bills. Without a savings account, you’re never truly protected from the financial variables life might throw your way.

Why Saving alone won’t make you Financially Independent

You need to spend money to live. Having a pile of money that isn’t doing anything for you won’t unlock a brighter future. Even in a high-yield savings account, the interest won’t amount to much. Financial independence means increasing your income, rather than just having an emergency stash to fall back on when something unexpected happens.

The idea of having savings is not to touch them unless you absolutely need to. The more savings you have, the more protected you are. But they aren’t helping you grow. Financial independence comes through growth, and it’s achieving that goal that will set you up for a smooth ride into your future. Continue Reading…

An Update on the 2017 Corporate Tax Proposals

By Robert G. Kepes

Special to the Financial Independence Hub

You have probably seen that ad on CNN with an apple and chattering teeth sliding in front of it. The voiceover says one is an apple and the other is a distraction. The ad concludes: “But it will never change the fact that this is an apple.”

The ad is a not-too-discreet dig at shenanigans currently taking place in Washington, D.C., and may also have some traction on this side of the border, especially where it concerns the federal government’s tax proposals.

Back on July 18, 2017, the federal government released its first take on tax proposals involving tax-planning strategies of private corporations, including many professional corporations. The feds announced a period of consultations to discuss proposed policy changes involving the taxation of corporate passive investment income, such as interest or dividends.

Income sprinkling a key focus

The government’s wish, which actually went back to the federal Budget released in March, 2017, was to close alleged tax loopholes, bring fairness back to the tax system, and end tax-planning strategies in which the rich may take unfair advantage. The strategy also looked at income sprinkling among family members using private corporations. Income sprinkling  allows the corporation to pay dividend income to the founder’s spouse and children, in lieu of the founder paying tax at the highest rate on all his/her income earned. Overall tax savings for the family is achieved through a combination of the founder’s top tax-rate salary, and low-tax dividends to the spouse and children. Continue Reading…

Rattled by the “Correction?” Diversification keeps your nest egg on the rails

“I know not what the future holds, but I know who holds the future.”
—Homer

We are all aware that portfolio winners rotate position from time to time. Leaders have a habit of becoming laggards. “Must own” darlings become “forgotten” names. Winners vacate the “winner’s circle.” As the timeless saying preaches, don’t put all your eggs in the same basket. Hopefully, this classic advice is being followed.

“Diversification strategies are essential, time-tested tools for every nest egg.”

The main goal of investment diversification is to contain the damages of market volatility from being inflicted on the nest egg. The importance of this is fundamental and always in fashion. I highlight some key observations on portfolio diversification:

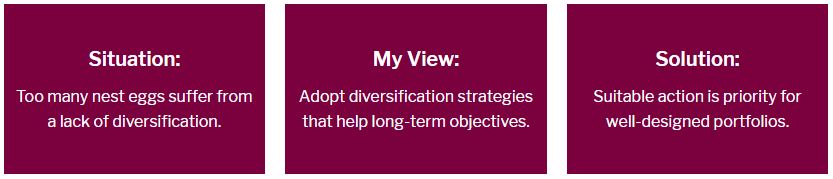
  • Investment portfolios suffer from inadequate diversification.
  • Mutual funds we own often have the same, or similar, stocks.
  • Investors are not aware that they lack diversification.

Diversification strategies are essential, time-tested tools for every nest egg. They improve your chances of achieving better consistency of long-term returns. It’s a focus for every investor to prioritize.

Basic diversification involves spreading your risks across different sectors of the economy. All within the asset allocation targets set by your investment plan of action. Make sure that you are comfortable with the approach so that you don’t have to dwell on regrets. Portfolios I review range from too concentrated to well over diversified.

Overall, diversification is a necessary safeguard. You don’t want problems arising in any asset class to ruin your well-designed portfolio. Especially the one that delivers the family’s retirement cash flow.

Develop sound habits

Diversification increases the odds of you being right more often than wrong. When some selections are suffering, others can step up and help cushion the rest of the portfolio.

Make it your habit to keep your nest egg from slipping off the rails. I summarize my top ways to achieve necessary portfolio diversification:

  • Asset Classes: Choosing different asset classes for the game plan is a sensible and prudent step. Stocks, bonds, cash, commodities and real estate are common picks.
  • Economic Regions: Portfolios may include selections from Canada and other regions around the world. Like the USA, Europe, Far East and emerging countries.
  • Time to Maturity: A portion of the portfolio could have a range of investment maturities. From as short as 30 days to as long as 30 years.
  • Foreign Currencies: Investment selections can be purchased in currencies other than Canadian funds. Such as US dollars, the Euro or hedged to our Loonie.
  • Investment Quality: High investment quality trumps reaching out for questionable yield. Trading quality for higher yields increases the potential to incur large losses.

Portfolios ought to contain a variety of investments that don’t all move in unison. However, seasoned investors know full well that is not always possible.

Broad brush

My table below is far from scientific. Look upon it as a broad brush view of portfolios that own Exchange Traded Funds (ETFs) and/or mutual funds as their primary investments in equities. Each investment selection is referenced as a “basket.” I divide the diversification landscape into three ballparks. Continue Reading…

Canadians think they need $756,000 to retire; failure to plan means most will fall short

My latest Financial Post column looks at a CIBC survey released Thursday that finds on average individual Canadians believe they’ll need $756,000 in order to retire.

Of course, most fall woefully short because they haven’t even crafted a financial plan to get there. And you know the old sayings, “Failing to plan is planning to fail,” or “If you don’t know where you’re going you’ll probably end up somewhere else.”

You can find the full column by clicking on the highlighted headline: The magic number for Retirement Savings is $756,000, according to poll of Canadians.

Considering that on average Canadians hope to retire by age 63, the fact that almost one in five haven’t even begun to even think about retirement suggests a bit of a disconnect. And women are consistently more behind in their retirement planning preparations than men. That’s a problem, considering that women have longer life expectancies and their money will therefore have to last longer.

Depending on aspirations, the “Number” can range from Zero to $2 million

\While the CIBC study looks at individuals rather than couples, the column quotes regular Hub guest blogger Marie Engen, who described three levels of retirement — basic, average and deluxe — in this 2016 blog: How much do you REALLY need to retire?  (The original blog ran on the Boomer & Echo site late in 2015.) Some with modest needs can save nothing and subsist on the $38,000 senior couples can get from CPP and OAS. Continue Reading…