Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

MoneySense Retired Money: Reboot Your Portfolio book review

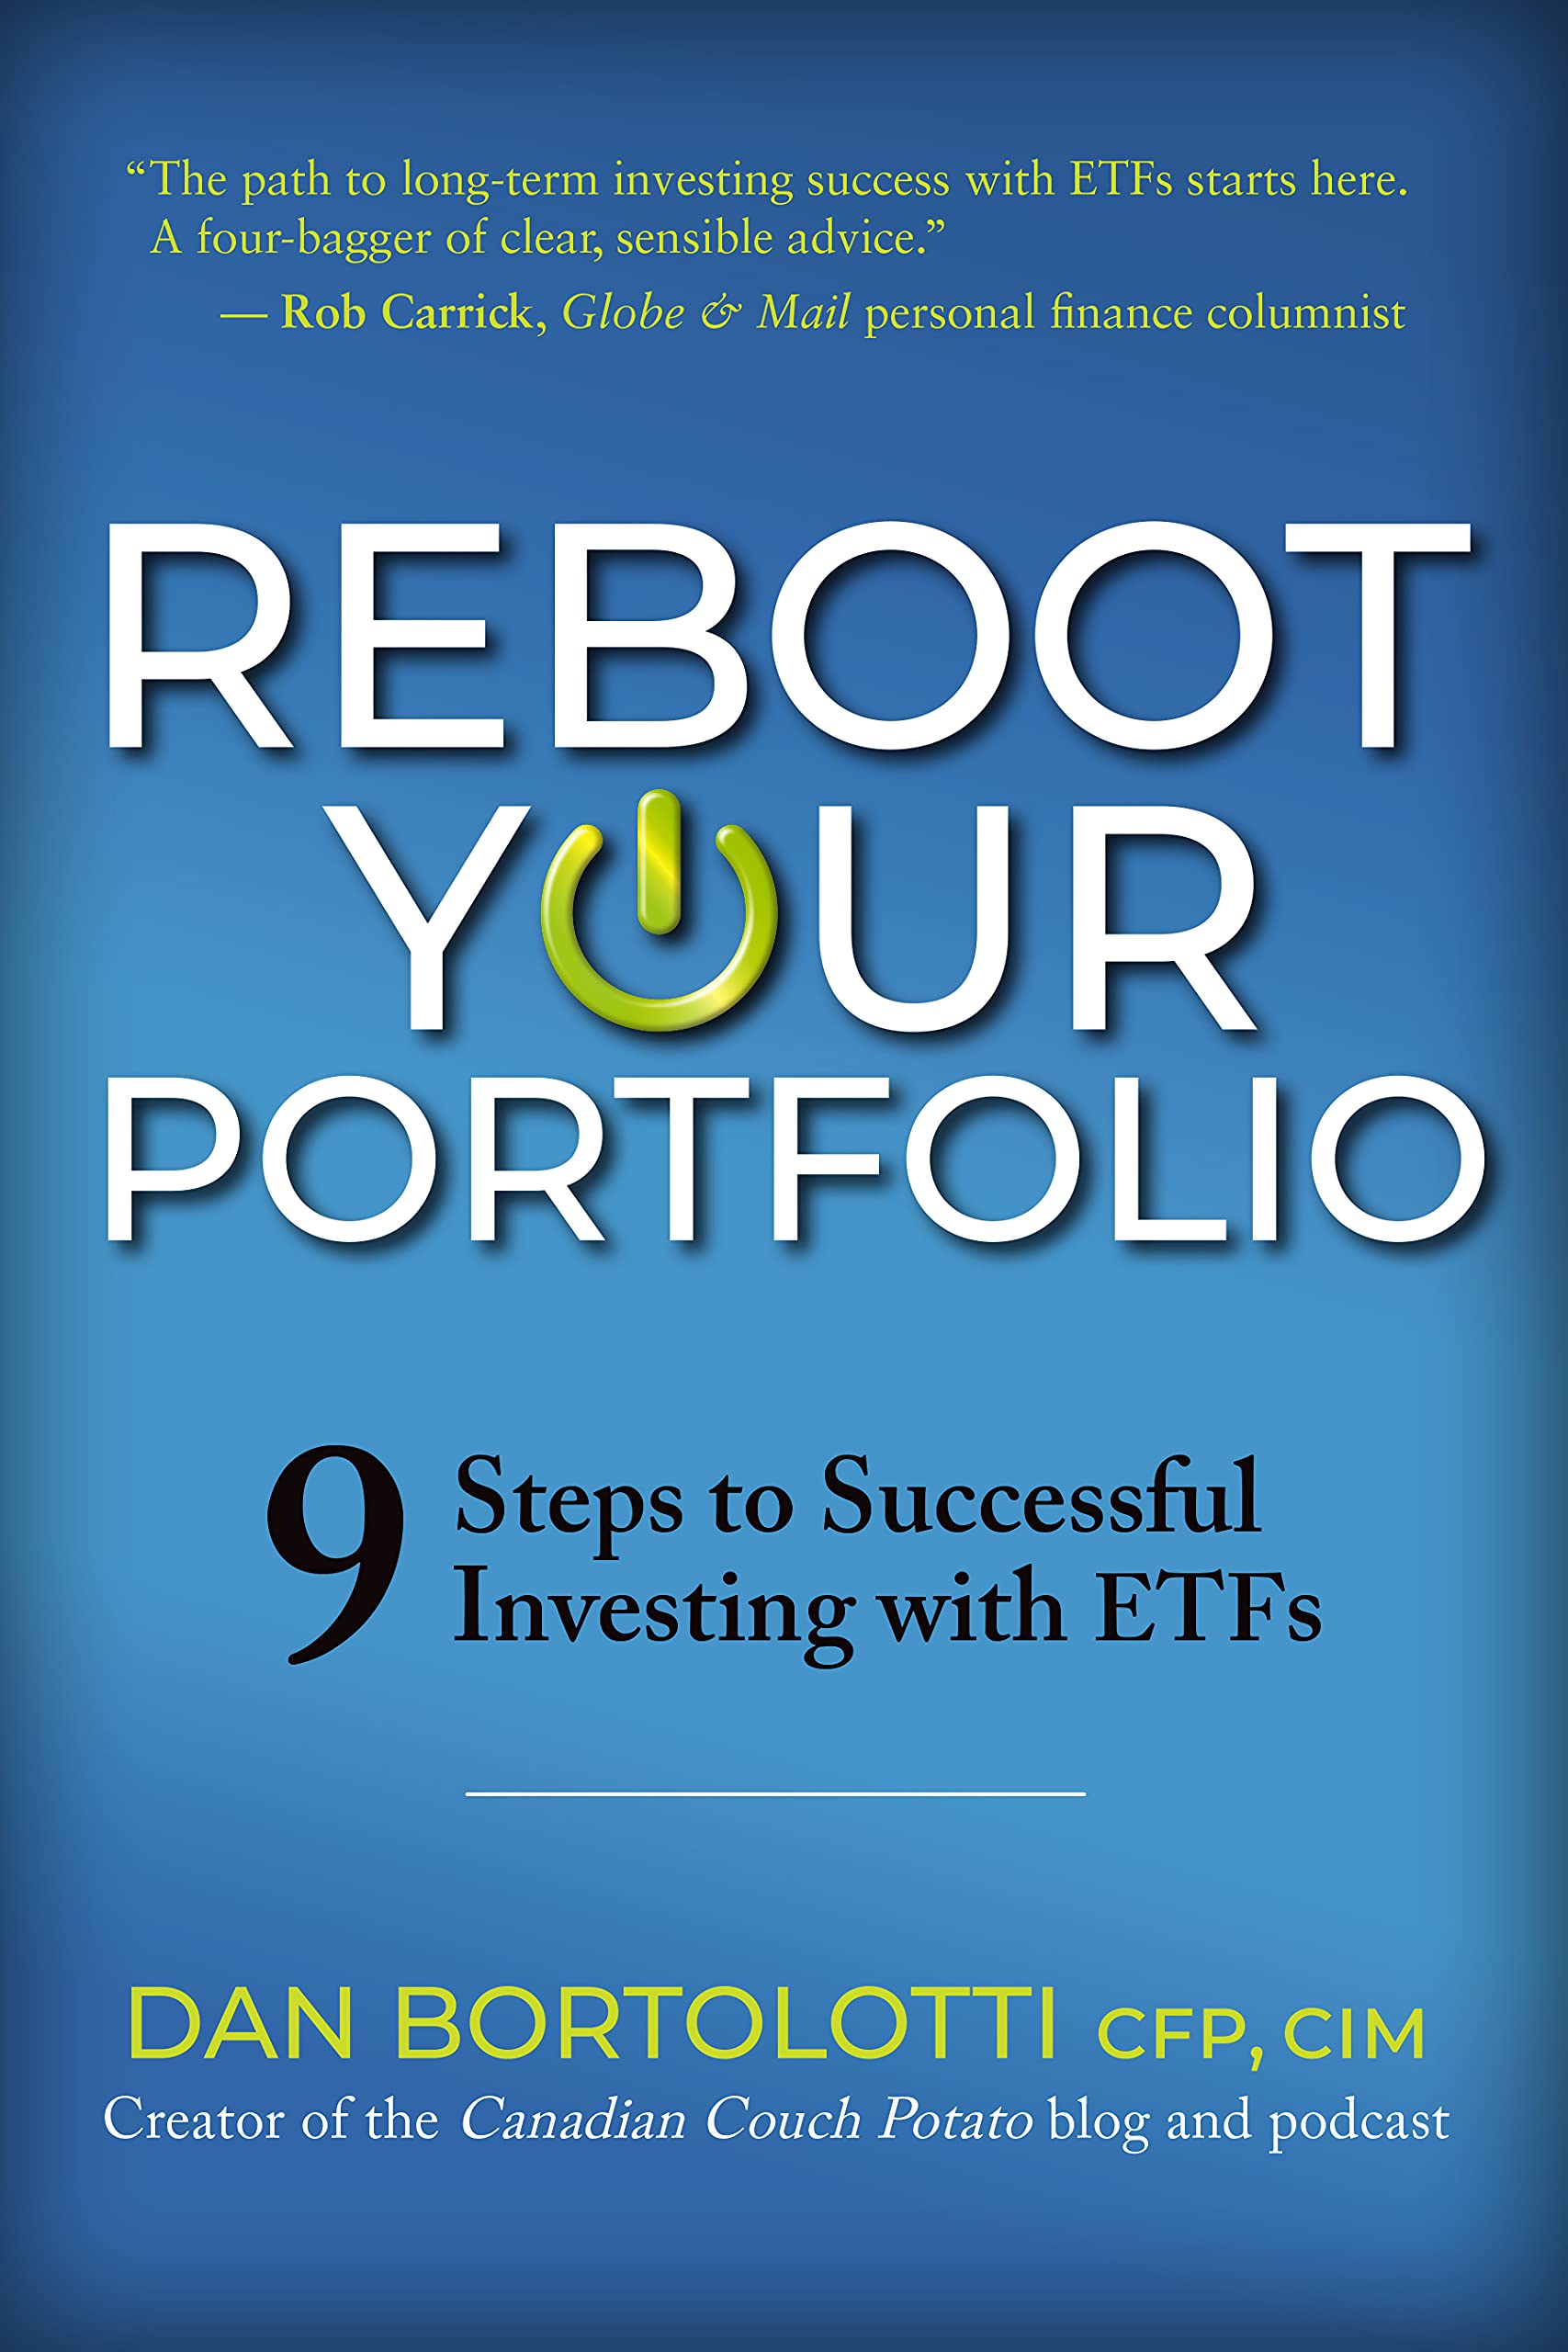
My latest MoneySense Retired Money column is a belated review of Dan Bortolotti’s recently published ETF book, Reboot Your Portfolio. You can read the full review by clicking on the highlighted text: The Canadian Book about ETFs that will have you saying eh-t-fs.

The book has already been well reviewed by prominent financial bloggers: for example, early in December the Hub ran this blog by Michael James on Money’s Michael J. Wiener: Do as I say, not as I do. 

As the column notes, MoneySense readers should find the book a nice complement to the MoneySense ETF All-stars feature that I used to write each spring, and which was initially a collaboration between myself and Dan back when we were both full-time MoneySense editorial staff. The 2022 edition ran last week and is now written by Bryan Borzykowski.

Dan’s book is an excellent primer for any aspiring do-it-yourself investor who wants to buy ETFs at a discount brokerage, or someone wanting to create an ETF portfolio with or without the help of a financial advisor like Dan or his employer, PWL Capital.

Since the dawn of Asset Allocation ETFs early in 2018 (starting with Vanguard, soon matched by iShares, BMO and Horizons), it’s now possible to have an entire portfolio consisting of a single ETF. Those who like the traditional pension fund allocation of 60% stocks to 40% bonds could choose VBAL, XBAL or ZBAL, or Horizon’s slightly more equity intensive, HBAL (with a slightly more aggressive 70/30 stocks/bonds mix).

One-decision funds and automatic rebalancing

Bortolotti is quite enthused with these Asset Allocation ETFs, as are most of the other ETF experts in MoneySense’s ETF All-stars feature. One thing he particularly likes about such funds is the automatic rebalancing between asset classes, or at least between the stocks and bonds that most of them hold in varying proportions. As he says in chapter 8 (Keep it in Balance), “There’s a lot of research suggesting that people do better when the rebalancing decision is taken out of their hands.”

The book takes a holistic approach to financial planning and ETF portfolio creation. In fact, he makes a point of not even addressing ETFs until chapter 5, after first covering the need to cease trying to beat the market, set financial goals, determine the right asset allocation and then fine-tuning.

Like most indexing enthusiasts, Bortolotti takes a dim view of such investing sins as market timing and stock picking.   In his chapters on Asset Allocation, Bortolotti does not restrict his readers to strictly ETFs: there may be a place for GICs and high-interest savings accounts. He says many could put half their fixed-income allocation in GICs and use bond ETFs for the other half.

But he does believe that even very conservative and very aggressive investors should have at least some exposure to stocks and bonds; conservative retirees should still have at least 20% in stocks and aggressive stock investors should have at least 20% in bonds. For those between, he is comfortable with their holding the traditional 60/40 portfolio, which has returned between 6 and 7% a year since 1990.
Beyond stocks and bonds, however, Bortolotti is less enthused. He doesn’t recommend commodities like gold and other precious metals, collectibles like rare coins, fine wine and artwork, or even REITs, preferred shares or Real Return Bonds: whether held directly or via ETFs.

When it comes to ETF portfolios, Bortolotti is primarily focused on broadly diversified low-cost ETFs that use traditional market-cap weighting, although he also sees the case for equal-weighted ETFs. But he does not recommend what he calls “narrowly focused” sector or “theme” ETFs. He covers the pros and cons of “smart beta” ETFs, which usually cost more than plain-vanilla ETFs but will at least be cheaper than actively managed mutual funds.

All in all, any MoneySense reader will probably find the combination of Reboot Your Portfolio and the ETF All-Stars as a nice one-two punch for their portfolio.

How DIY investors can invest in strategic or tactical opportunities with Sector ETFs

By Sa’ad Rana, Senior Associate – ETF Online Distribution, BMO ETFs

(Sponsor Blog)

Sector ETFs provide exposure to a specific industry or market sector and have grown in popularity amongst “Do It Yourself” investors who are looking to add strategic or tactical opportunities to their investment portfolios.

Why ETFs for Sector Exposures?

Sector ETFs have many benefits that ETFs provide in general: diversity, transparency, liquidity, and cost efficiency. Using a sector ETF, investors can tactically add exposure to an entire sector within a single trade. A sector ETF generally holds anywhere from 10 to over 100 different securities providing instant diversification, which minimizes single-stock risk and maximizes exposure to the entire sector. This diversification also helps to lower overall portfolio volatility.

Sector ETFs in Canada

Canada has over 1100 ETFs and 150 of these are categorized as sector ETFs. BMO ETFs has 20 different sector ETFs and was one of the first to list sector ETFs on the TSX in 2009.


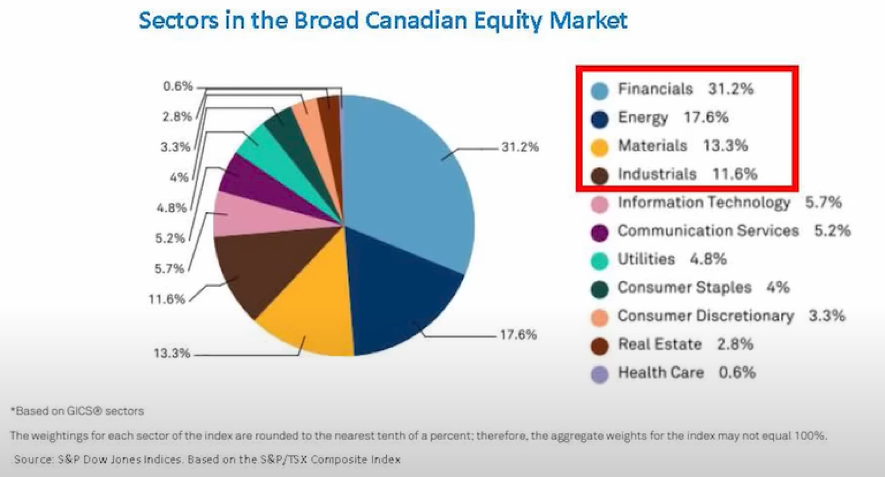
The Canadian market is very concentrated in several different sectors: Financials, Energy, Industrials and Materials. For investors using a broad-market Canadian ETF they may be underexposed to other areas of the market. For example, the Health Care and Info Tech sectors in Canada are extremely small relative to the global economy.  Therefore, Canadian investors may consider U.S. and global sectors for a more diversified portfolio. This completion trade makes sector ETFs in Canada very popular. Continue Reading…

Building the Energy Dividend portfolio


By Dale Roberts, cutthecrapinvesting

Special to the Financial Independence Hub

When it comes to sectors, energy is the most useful inflation fighter. In fact it is the only sector that has delivered positive real returns across every inflationary period, looking back some 100 years of stock market history. Energy stocks also delivered incredible returns during the stagflationary period of the 1970s and into the early 1980s. We have entered a stagflationary enviornment and (like the 70’s show) it includes an energy and commodities price shock. While I have enjoyed some very generous total returns from our energy ETFs, I am set to harvest most of those total returns, and will start building the energy dividend portfolio.

From an RBC report …

We peg free cash flow generation (before dividends) across  the Canadian majors — Canadian Natural Resources, Suncor Energy, Cenovus Energy and Imperial Oil

—at $46.0 billion in 2022 and $48.7 billion in 2023.”

The free cash flow gushers are just ridiculous. The dividends (and investors) are enriched by that free cash flow.

Here’s a Tweet thread from Larry Short that sets the table.

Yes, have a look for my “Don’t drill baby, don’t drill” reply.

You can also have a look at the quarterly update video from iA Private Wealth.

They’ve stopped drilling and now they’re filling – your brokerage account. From that very good video, Larry picks up an interesting chart from our friends at Ninepoint Partners.

You might say this is the money chart, the money shot.

Canadian energy stocks

And here is a post on Cut The Crap Investing that invited readers to consider investing in Canadian energy stocks, from October of 2020. That was about 300% ago. With even more gains available if you invested in the Ninepoint Energy Fund.

I have admitted to being late to eat my own cooking. In our accounts we have gains in the 100% to 150% range. In a TFSA account, I have sold a modest amount of shares in iShares XEG to pay our price at the pump for the next year or two. Being that I am in the semi-retirement stage with my wife being 2-5 years away from retirement, I will make that transition, selling down shares and moving the proceeds to dividend-paying stocks and specialized income-producing energy ETFs. That will take away the price risk for the energy producer sector. But certainly, the financial health of the sector and the companies is still very important. Only healthy companies (and sectors) deliver stable or growing dividends. Continue Reading…

Infrastructure: An alternative solution for inflationary times

By Shane Hurst

Managing Director, Portfolio Manager,

ClearBridge Investments, part of Franklin Templeton

(Sponsor Content)

Inflation has been the major theme dominating the investment world in 2022. Canada’s annual inflation rate reached 6.8% in April, representing a 31-year high. Canada is far from an outlier in this respect, with the U.S., the U.K. and many other western nations also experiencing rapid price growth over the past 12 months. In response, central banks have committed to a series of rate hikes this year, which in turn has raised the prospect of a global recession.

In this uncertain environment, market volatility has been elevated, particularly so in bond markets. Downside protection is front of mind for many investors as a result, but there are options out there to still generate returns for a portfolio without loading on risk.

Infrastructure assets, once the preserve of institutional investors, can now be a useful tool for retail investors and help in limiting risk and providing a stable income stream. Launched in Canada last year, Franklin ClearBridge Sustainable Global Infrastructure Income Fund (available as an ETF through FCII), harnesses the expertise of ClearBridge Investments, one of Franklin Templeton’s specialist investment managers. ClearBridge manages infrastructure income funds in the U.S., U.K., Australia, Europe and Canada, with global AUM of US$4 billion, as of March 31, 2022.

An asset class that makes economies function

Infrastructure as an asset class can be loosely defined as the services and facilities necessary for an economy to function. With the ClearBridge Infrastructure strategy, the portfolio is made up of regulated assets (e.g. electricity infrastructure and sewage pipes) which are characterized by stable cashflows, high income and low GDP exposure, and user-pay assets (e.g. airports, ports, railroads and toll roads) which generally provide lower income but are leveraged to GDP.

The investment team can take on a more defensive posture as circumstances dictate. For example, prior to the extreme sell-off of 2020, the strategy had a higher weighting to lower-risk regulated assets, which served it well during that period when its decline was approximately half that of its benchmark S&P Global Infrastructure Index. Continue Reading…

MoneySense ETF All-Stars 2022

MoneySense has just published its annual feature, the ETF All-Stars 2022. For the first time in several years, I was not the lead writer on this package although I was involved in my role as Investing Editor at Large. We passed the writing reins to veteran financial freelance writer Bryan Borzykowski, who has previously written MoneySense’s annual Robo-advisor feature and is currently writing a new book to be titled ETFs for Canadians for Dummies.

As I point out in another MoneySense column, there is another ETF book published in 2021 that makes a good complement to the All-Stars package.  Reboot Your Portfolio is written by Dan Bortolotti of PWL Capital. Dan was the lead writer of the first edition of the ETF All-stars and served as a panelist for several subsequent years, along with his PWL colleague Justin Bender. In recent years, PWL advisors Ben Felix and Cameron Passmore have served as some of the panelists responsible for selecting the All-stars. The team of 8 panelists is unchanged from last year.

You can find the new edition of the All-stars by clicking here: Best ETFs in Canada for 2022.

As Bryan points out in his overview, by design, the panel didn’t make that many changes from previous years. The idea all along has been to provide a bunch of core low-cost, broadly diversified ETFs that don’t need to be changed every year. Certainly, the panel has never felt obliged to recommend brand new “theme” ETFs just for the sake of change.

Here’s my summary of the main changes:

Canadian Equities

No changes to last year’s lineup.

US Equities

The panel dropped the list of US equity ETFs from ten last year to seven this year.

International Equities

Last year’s picks return, plus the panel added three Emerging Markets ETFs: XEC, ZEM and EMXC.

Fixed Income

While Fixed Income has been a languishing asset class in recent months, the panel didn’t view this as alarming. Its previous lineup of Bond ETFs returns largely intact, with just one casualty: the panel decided to remove the Vanguard Global Bond ETF (VGAB.) For those who are nervous about more losses from rising interest rates, it continues to emphasize short-term bond ETFs like VSB and XSB

Note that in my recent MoneySense Retired Money column on the alleged Death of Bonds, I quote panelist Ben Felix, who still sees a role for fixed income in diversified portfolios. My column suggests those worried by rising rates can either park in treasury bills and wait for further interest rate hikes later this year, or ladder 1- and 2-year GICs every few months. Several 1-year GICs now pay close to 3%. That may be below the rate of inflation of late but at least  its beats losses of near 10% sustained by aggregate bond ETFs. Continue Reading…