Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Long term trends drive global sports and gaming industry

(Sponsor Content)

The global sports industry is worth between US$400 to $500 billion a year and in the five years leading up to the pandemic in 2020 had been growing at an annual rate of 14%, according to NewZoo.

The industry is far more than professional teams in hockey, football, baseball and basketball. These North American favourites are dwarfed by soccer which is the world’s most popular games.

When it comes to pro teams, in addition to game tickets, fans buy branded merchandise and play in fantasy leagues. The teams earn more TV revenues as they advance in playoffs. But sports business is more than that. It also involves online gaming, gaming software developers and internet sports gambling. These last areas are large and rapidly growing. While the United States is the world’s largest sports market, China and other parts of Asia are emerging as leaders in eGaming and iGambling.

Harvest Portfolios Groups Ltd. has launched the Harvest Digital Sports & Entertainment Index ETF (TSX:HSPN) to take advantage of the attractive dynamics of this sector.

In the interview below, Harvest CEO Michael Kovacs discusses the ETF, the sector’s outlook and how the ETF aligns with the Harvest philosophy of creating value through ownership of the best global businesses.

Financial Independence Hub [The Hub henceforth]: Why did you launch the Harvest Digital Sports & Entertainment Index ETF?

Michael Kovacs [MK henceforth]: Sports entertainment is a global industry with great growth characteristics. It is regaining a foothold after more than a year of empty stadiums and lost revenues. At the same time, there have been bright spots, including new forms of sports entertainment such as online gaming and internet gambling where the pandemic has been a catalyst.
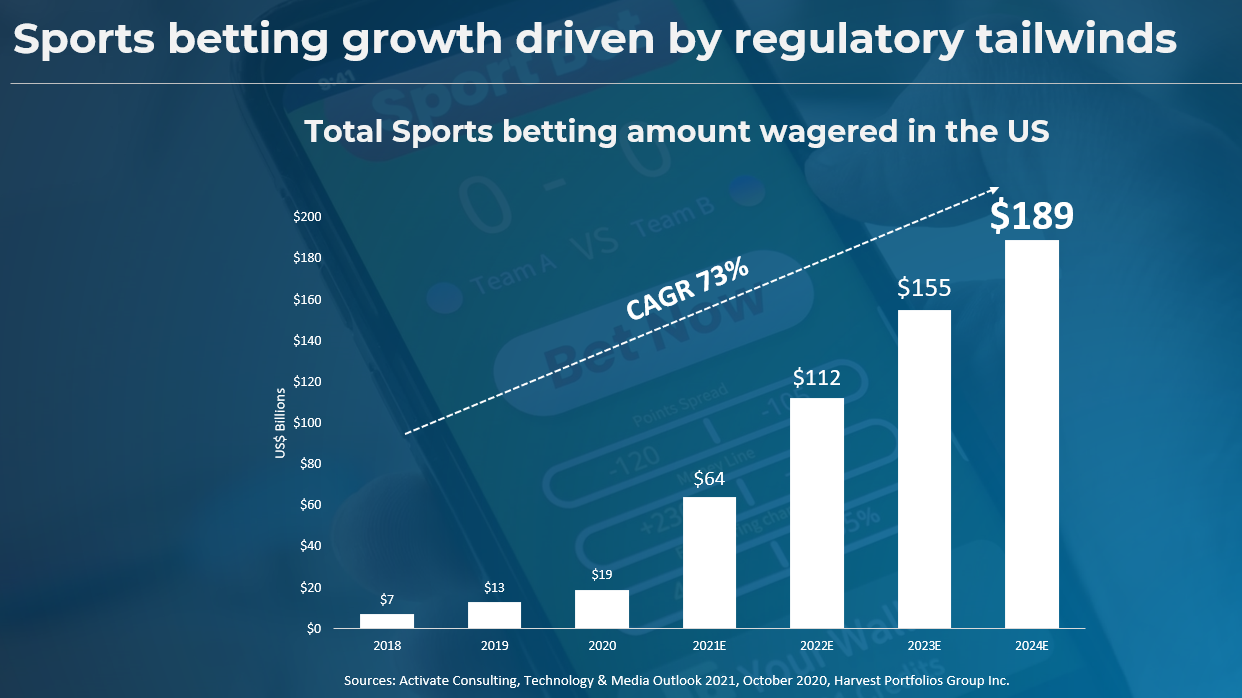
At Harvest, we seek to identify trends like this. Sports is one that continues to grow globally and also offers reopening opportunities as the pandemic issues decline.

The Hub: How is the ETF designed?

MK: It is passively managed ETF with 40 global stocks that follows the Solactive Sports & Entertainment Index. The companies are publicly traded, mostly in North America, with some in Europe. The ETF is diversified across five areas of the sporting world, with different weightings for each area. It is rebalanced quarterly.

The Hub: What is the strategy?

MK: As mentioned, the ETF is diversified to capture all segments of the industry. Professional sports organizations make up five of the 40 holdings, or 12.5%. There are a number that either trade under their own name or as part of companies that own them. The English soccer team Manchester United Plc is one example. It is one of the game’s strongest brands. It is listed in New York and has a market capitalization of about US$2.7 billion. Another example is Liberty Media-Liberty Formula One. which trades on Nasdaq. It owns the Formula 1 racing and has a market cap of US $18 billion. Madison Square Gardens Sports Corp.  is another. It owns the New York Rangers of the NHL and the NBA’s New York Knicks. It has a market cap of US $4.5 billion. These are examples of some of the great sporting franchises out there.

The Hub: Are event and ticket companies and sports equipment and apparel companies another component?

MK: Yes, they are. Together they are about 38% of the ETF. Ticketing makes up five holdings or 12.5%. There are a lot of companies that people would recognize. Live Nation Entertainment Inc. owns the familiar ticketing company, Ticketmaster. Live Nation is a global company that manages ticket sales and resales and also owns and operates entertainment venues and manages careers. In fact, they own and operate several of the premier venues that many Canadians have attended concerts and events.

Sports equipment and apparel is another 10 holdings or 25% of the ETF. Again, many of the companies are household names. Nike Inc. is a global leader in the manufacture and marketing of athletic shoes, branded clothes and equipment. It also sells baseball bats and balls, tennis rackets and golf clubs. Nike’s annual revenues are more than US $18 billion.Adidas which is the second largest global sports apparel company after Nike, owns Reebok and part of the German soccer club Bayern München. Cross ownership like this gives these companies incredible brand power.   Continue Reading…
Wealth & Happiness, Part 2: Happiness is a Thought and can be changed

By Warren MacKenzie, for Canadian Moneysaver

Special to the Financial Independence Hub

In Part One of this series we mentioned how ‘living in the moment’ — that is being free of ideas of self and the things we wish for — is an opportunity for happiness.

In this part we will first explain how happiness comes from our thoughts, not our financial circumstances, and how making money usually generates more happiness than spending it does. We will then look at how money can buy happiness when you give it away, and how it’s not enough to manage money wisely: we also have to use our money wisely.

For example, let’s imagine two people with the same size investment portfolio living in almost identical apartments. In one case, the individual who may have experienced a windfall is overjoyed to be living on his or her own, while the other person, who may have suffered a financial loss, is sad and embarrassed to now be living in such a small apartment. One person is happy and one is sad. The difference is not based on their different circumstances it is entirely based on their thoughts about their situation.

In his book, The Art of Happiness, Dalai Lama says, “Once basic needs are met – the message is clear: We don’t need more money, we don’t need greater success or fame, we don’t need the perfect body or the perfect mate – right now, at this very moment, we have a mind, which is all the basic equipment we need to achieve complete happiness.”

Overcoming challenges

For most successful people, it’s their accomplishments that gives them the greatest happiness, whether that includes looking after their family, accumulating wealth, or showing resilience and problem solving through difficult situations. Successful people know that a happy life is not a life without problems or negative circumstances: rather it is one where we have the opportunity to overcome challenges and problems.

It’s important to realize that most often, the greater the challenge, the greater the happiness that comes from overcoming it. If parents make things so easy for their children that they never have to work hard and learn to overcome challenges, (including financial challenges) their children may not develop the positive self-image and confidence that comes from solving problems and creating their own financial security. Continue Reading…

Can Dynamic Pension Pools strengthen Canadians’ Retirement Income Security?

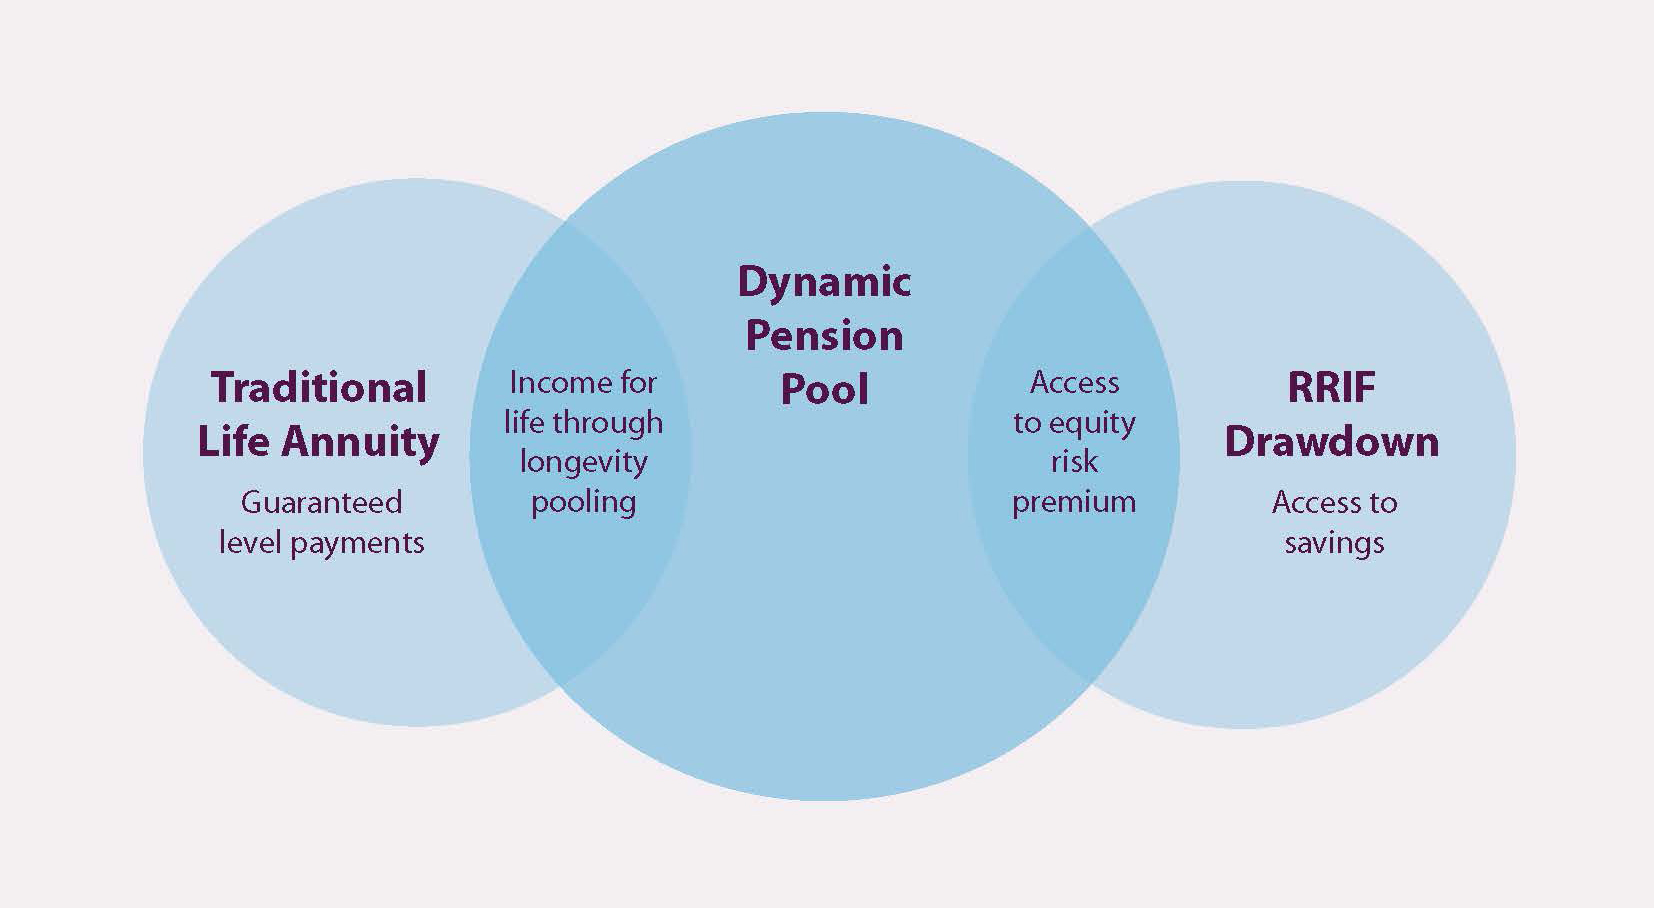
Image courtesy National Institute on Ageing

A new report published by the National Institute on Ageing (NIA) and the Global Risk Institute (GRI) being published today aims to help overcome the $1.5-trillion Decumulation Disconnect in the Canadian Retirement Income System.

Titled Affordable Lifetime Pension Income for a Better Tomorrow, the report makes the case for how Dynamic Pension (DP) pools can strengthen retirement income security for millions of Canadian seniors. Here is the link to the full report.

The urgency is apparent when you consider that 10 million Canadian baby boomers are now entering retirement: with longer life expectancies and a greater dependency on private savings to sustain them. As the report’s authors write, “it’s more important than ever to find solutions that will help retiring Canadians turn their accumulated savings into low-cost lifetime pension income.”

Bonnie Jeanne MacDonald/Ryerson/National Institute on Aging

Lead author Dr. Bonnie-Jeanne MacDonald, Director of Financial Security Research at the NIA, says fears that retiring Canadians’ savings won’t sustain them in retirement are “legitimate …  Financial markets, inflation and health expenses are just some of the big unknowns that retirees will need to face over 10, 20, 30 or even 40 years.”

According to the report, Dynamic Pension [DP henceforth] pools have the potential to transform the Canadian retirement landscape. Their goal is simple: to help people optimize their expected lifetime retirement income while ensuring they never run out of money. In other words, gurantee that they won’t run out of money before they run out of life.

Pooling Longevity Risk

While protecting individuals from outliving their savings (i.e., longevity risk) can be prohibitively expensive, the same protection becomes affordable when spread across a large group. Pooling longevity risk allows retirees to spend their savings more confidently while they are alive, says the report.

In a DP pool, pension amounts are not guaranteed but may fluctuate from year to year. This means retirees can stay invested in capital markets and benefit from the higher expected returns.

DP pools have a risk-reward profile that is fundamentally different from current options and products available for older Canadians: such as guaranteed annuities purchased through insurance companies or individually managing and drawing down savings from personal retirement savings accounts, says another of the report’s authors, Barbara Sanders, Associate Professor at Simon Fraser University,  “Retirees who are comfortable with some investment risk can stay invested in equity markets and reap the associated rewards, which is important in today’s low-interest and high-inflation environment.” Continue Reading…

RBC launches new digital banking tools to help clients manage their money, every day

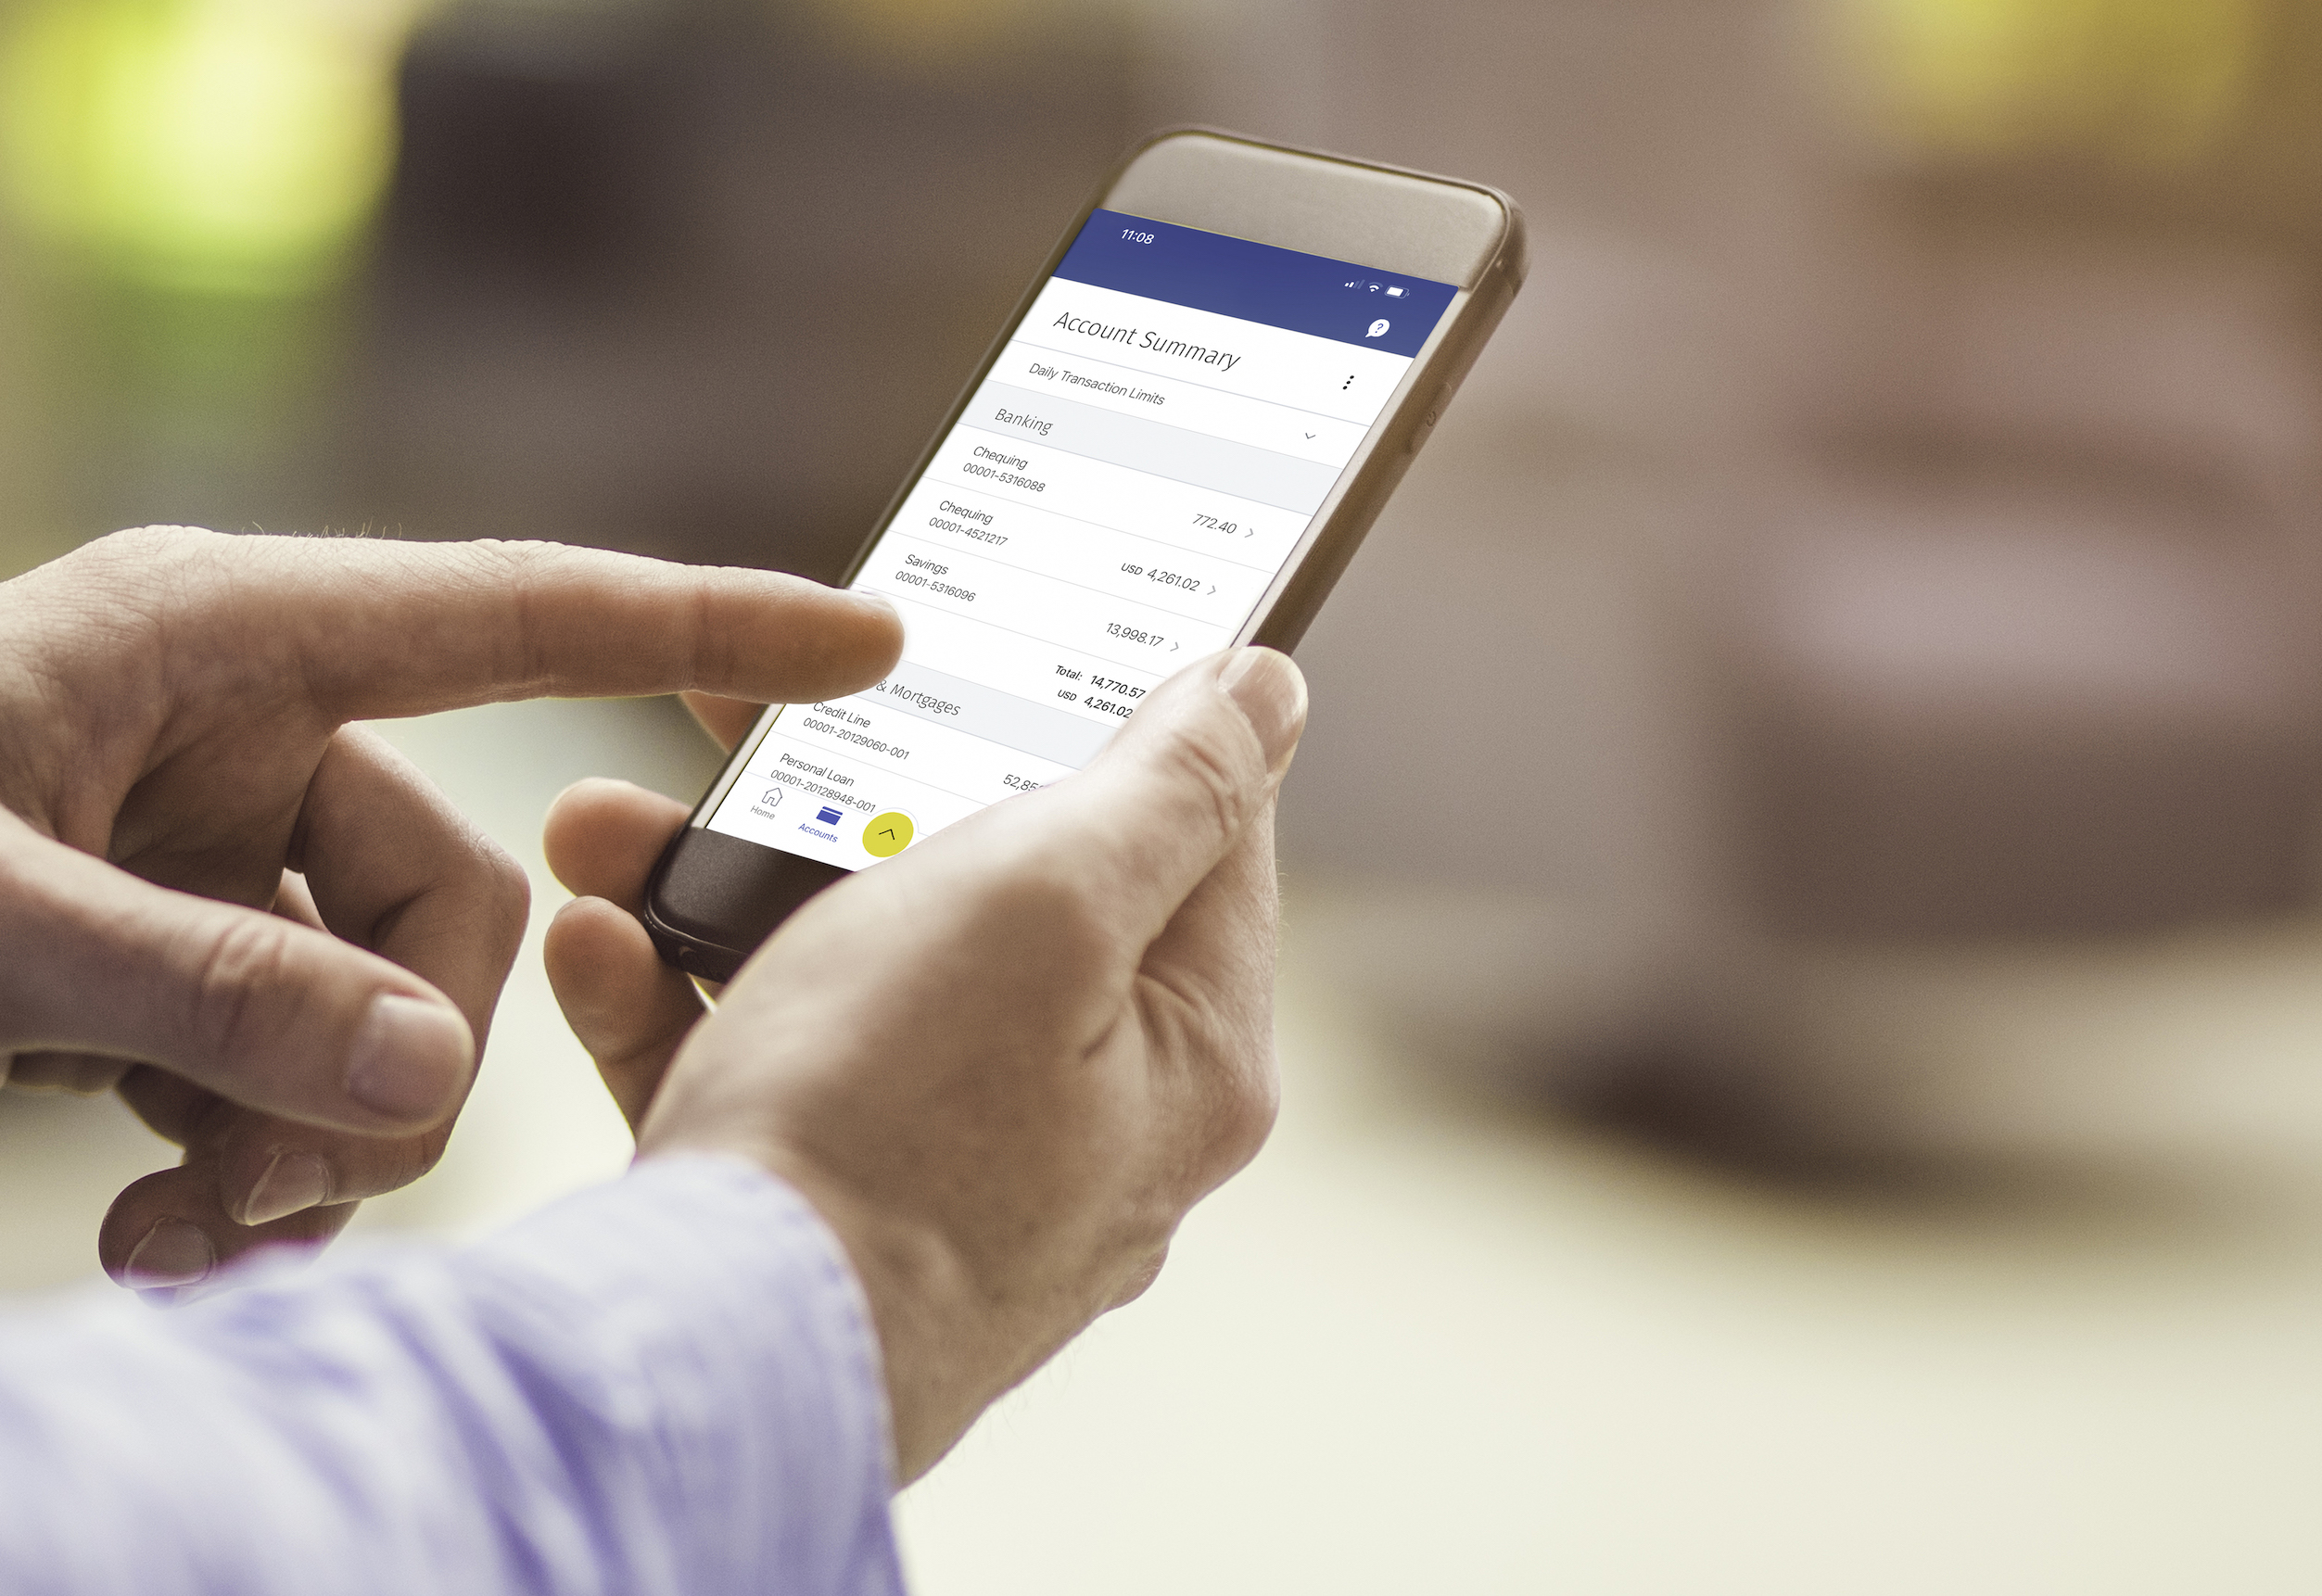
Image from RBC/iStock

By Peter Tilton, Senior Vice President, Digital, RBC

 (Sponsor content)

As the banking landscape continues to evolve and more Canadians choose to bank digitally, it’s more important than ever to empower our clients with the tools they need to confidently manage their money and keep their accounts and information safe.

That’s why we’re continuing to add value while enhancing security for our clients through two new industry-leading digital capabilities.

The first – 2-Step Verification – is the newest security feature within the RBC Mobile app, providing added protection for clients who access their accounts digitally.

The second is the latest capability in our award-winning NOMI offering. With NOMI Forecast, clients can quickly get a seven-day view into their future cash flow and stay up-to-date on upcoming preauthorized payments from any deposit account.

Let’s take a closer look at what these two innovations offer Canadians.

More peace of mind with industry-leading digital security tools

With more options than ever to access our accounts online and through our mobile devices, having the peace of mind that our personal and financial information is protected is critical.

With our new 2-Step Verification we are further enhancing the security features available to our clients by adding new safeguards around identification and authentication.

Embedded directly within RBC’s Mobile app, 2-Step Verification enables clients to set-up their mobile device as their primary channel for their online and mobile accounts. This means when they log into their account from another source, such as their laptop or tablet, they will receive a prompt within the app to verify the session.

With the verification process happening directly in the app, clients no longer need to go through the hassle of manually entering a security code received via email or text. With the press of a single button, they can continue with their banking needs knowing their information and accounts are protected. Since no security code is used, there is no threat of a code being intercepted.

Our new 2-Step Verification is just one of the industry-leading digital security tools our clients can access:

  • With our card lock option within the RBC Mobile app, clients can quickly and easily lock their card if they’ve misplaced it. This eliminates having to cancel a card only to find it later, while reducing the chance that it’s misused if it doesn’t show up.
  • With ID Verification, clients have the ability to digitally verify their identities when opening an account remotely or in-branch. This creates a more seamless account open process for our clients, while further protecting their identity and accounts.
  • Our fraud monitoring and Digital Banking Security Guarantee means our clients can be confident they will be protected when banking online or through the mobile app.*

Leveraging AI for forecasting to bring next-generation digital advice to clients

The financial challenges many Canadians faced as a result of the pandemic have put an added spotlight on our daily finances. We’ve also heard directly from our clients that they want to feel supported with digital tools and personalized insights to help them stay on top of their finances. Continue Reading…

MoneySense Retired Money: Is it too late to jump aboard the Energy bandwagon?

My latest MoneySense column is something I might better have written early in 2021, rather than late in the year. It’s about the the resurgence of the energy sector: not alternative energies like solar or wind but good old-fashioned oil (black gold), natural gas and even coal.

You can find the full column by clicking on the highlighted text: Are Energy stocks a good buy now? 

As I admit there, readers would have been better served by heeding the advice of  MoneySense colleague Dale Roberts, who was early identifying this trend a year ago when he mentioned this Canadian energy ETF back in October 2020. (iShares S&P/TSX Capped Energy Index ETF: XEG/TSX.)

In fact, I did buy a little of it, only to see it fall back later in 2020, and I foolishly sold for tax-loss selling purposes.  But as the column relates, I did repurchase it, as well as BMO’s Equal WeightedOil & Gas ETF (ZEO/TSX) and a few more besides.

Until this year, I was happy to pick up whatever energy plays exist in the “Core” ETF investments. Besides, most Canadians should have healthy exposure to energy just by virtue of owning standard Canadian equity ETFs or even balanced funds. After all, Vanguard’s FTSE Canada All Cap Index ETF (VCN/TSX] is 12.3% in energy, just a tad below the index’s 12.6%.

By contrast, the S&P 500 index has only a tiny 2.33% in Energy. In fact, south of the border, Energy is the smallest of the 11 sectors, which are topped by Information Technology a 27.6%.  However, Energy stocks have well outpaced the S&P500, generating a total return of 42% in 2021, as of October 1st, compared with just 18.4% for the broad index.

Performance chasing or start of multi-year bull market?

So loading up on Energy seemingly this late in the game would be a futile exercise in performance chasing, some would argue. Who knows, but personally I was persuaded by the repeated public utterances of Ninepoint’s Eric Nuttall [notably and repeatedly in the Financial Post] that this may be merely the confirmed start of a multi-year bull run in Energy. Accordingly, earlier in the year I took a modest flyer on Nutall’s NinePoint Energy ETF [NNRG/Neo exchange]. His focus is Canadian mid-cap energy stocks, although there is a small 7.8% weighting to US energy stocks. Continue Reading…