Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Q&A on the new Harvest global bond ETF


By Bradley Komenda

(Sponsor Content)

Harvest Portfolios Group launched a global bond ETF in January 2020 to complement its equity ETF offerings.

The  Harvest US Investment Grade Bond Plus ETF (HUIB:TSX) is managed by Boston-based Amundi Pioneer Asset Management, a subsidiary of Amundi Asset Management, a leading global manager based in France. In a Q&A, Bradley Komenda, the ETF’s portfolio manager, discusses how Amundi’s value investing approach helps guide its strategy. Mr. Komenda joined Amundi Pioneer in 2008 and is also Senior Vice President and Deputy Director of Investment Grade Corporates at the firm.

Financial Independence Hub: What is the demand for these bonds for the Canadian investor?

Bradley Komenda:  Canadian bond market opportunities are pretty narrow and heavily weighted towards energy and financials. Because there is a lot of demand for these bonds, yields are less attractive than in the US.

This bond ETF gives you breadth. It is Canadian dollar hedged, but with access to top quality US, European and Global issuers.  Expectations of further fiscal stimulus will all be supportive of the corporate bond market, so we think that this is where we want to be.

Q: What is Amundi Pioneer’s approach?

A: We are value investors. We invest in credits that we think over a one to three-year time horizon are going to generate a superior return. By value investing, I don’t mean buying the cheapest securities. It means trying to identify the securities that have the best risk adjusted return potential.

Q: How do you assess risk?

A: We look at risk in three ways. We look at nominal risk, which is how much we have invested in a single issuer. Then we look at the maturity of the bonds. We know that if we buy a one-year bond, it is a lot less risky than buying a 30-year. And then we look at duration times spread, (DTS) which is a way to measure the credit volatility of a bond.

Q: Where is the Harvest US Investment Grade Bond Plus ETF on the risk spectrum?

A: From an overall portfolio perspective, this bond ETF is rated low risk, and within the fixed income universe, I’d say it’s medium.

If you want lower risk, you can do a couple things. You can buy government bonds, but after inflation your purchasing power will be eroded even with longer duration bonds.

If you go for a short-term ETF, or cash, you’re going to struggle to get a yield similar to inflation. So, this ETF is for someone with patience, a one to three-year time horizon and a willingness to accept short-term volatility but with the expectation of attractive returns relative to risk-free or very short bonds.
Q: What about bond quality?

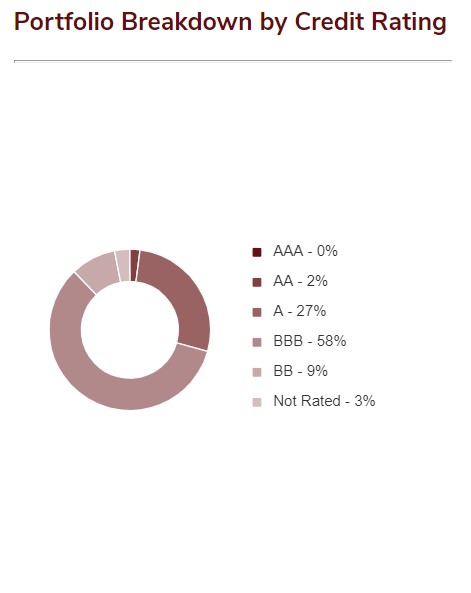
A: HUIB is concentrated in the Triple B space (BBB) or higher. The breakdown is roughly 60% BBB, 30% A or higher and 10% Non-rated.

Q: Who is the core investor for this bond ETF?

A: Anybody who wants exposure to fixed income. That’s because it has a negative correlation to stocks which means they move in different directions.  If you buy a high yield fund, you’re going to get more yield, but you’re going to have a positive correlation to stock market movements.


Q: Investors worry about liquidity. How easy is this ETF to sell?

A: It’s highly liquid. We had a liquidity crisis in the corporate bond market in March of this year. The Fed stepped in and now is backstopping things by purchasing bonds as needed. It means the draw down we saw in March and early April is unlikely to occur again.

Q: What is the relative advantage of this ETF?  

A: This ETF is part of our investment grade corporate bond strategy. Continue Reading…
Fundamental Digital Marketing practices for 2020

By Mike Khorev

Special to the Financial Independence Hub

It’s no secret that the world of digital marketing is continually changing, and every individual marketing channel in it is also rapidly changing all the time. Meaning, if you want to utilize digital marketing to grow your business effectively, you’ll need to stay up-to-date with the current trends. 

Although some digital marketing parts stay relatively the same, like how search engine optimization works and the importance of email marketing, there are also significant changes and even brand new channels that can significantly change the game. 

In creating any digital marketing strategy, however, it is essential to focus on creating a strong fundamental that you can easily expand to other digital marketing tactics; these fundamental tactics can act as a vital building block for your business, so even when you’d need to adopt a new trend, you can easily integrate it with this existing fundamental.

That said, here are the fundamental digital marketing practices in 2020 and onwards:

1.) Content Marketing and SEO

In this age of social media, content is king. 

Whether you can be successful in your digital marketing or not would ultimately depend on whether you can attract and engage enough audience through your content:  

  • You generate leads by attracting prospects with valuable content.
  • You nurture leads by using content to educate your prospects about your product/service and establish your credibility via consistent content quality.
  • You convert leads into customers by using content to convince people to buy 

So, content should be the backbone of your overall digital marketing strategy, and SEO (Search Engine Optimization) would be the primary way for people to find your B2B brand. 

However, since more businesses are now focusing on content marketing, the competition in attracting the audience’s attention with content is now much tighter. Simple and informative, educational content that worked in 2017 simply won’t cut it anymore these days, as readers now expect the highest quality of information and authoritative data. 

Also, consumers now expect various forms of content in textual blog posts and white papers and videos, podcasts, infographics, and other mediums. Diversifying your content is very important and offers more personalized and interactive content for each audience, which will bring us to the next point below. 

2.) Conversational and Personalized Marketing

 The rise of various AI and machine learning technologies has provided us with more ways to implement highly-customized and conversational marketing tailored for each prospect. 

One of such technologies is the chatbot, which has been popular among many businesses in recent years. A 2017 survey by Gartner has predicted that 47% of organizations will implement chatbots for customer service in the years to come. 

Chatbots can allow businesses to implement personalized marketing with different implementations. For example, in a sales inquiry conversation,  the chatbot can ask for preliminary questions about the prospect’s preferences, available budget, and so on, so when the chatbot finally passes this prospect to a human sales rep, the process would be much more seamless for both the sales rep and the prospect. 

According to Fractional CMO Mark Evans, conversational and personalized marketing channels can help marketers create highly-targeted marketing campaigns and gather more information about your prospects and customers. 

3.) Video Marketing

Video is technically a part of content marketing, which we have discussed above. Still, in the past half-decade, video marketing has grown to be a powerful digital marketing channel that deserves its attention.  Continue Reading…

Bullshift Culprits 1 and 2: FOMO and TINA

Bullshift Culprit #1 FOMO (Fear of Missing Out)

For anyone who has been out of the loop, there are a number of acronyms and memes that have popped up over the past decade that help commentators to capture contemporary zeitgeist.  One of the most popular is FOMO – the Fear Of Missing Out.  The basic idea here is that other people are doing something (having fun, getting rich, cheating the tax man) that others want to get in on.

Getting in on things is all fine and well, provided they are legal.  Many aspects of FOMO are indeed legal and it should be obvious that there are social risks associated with wanting to do things that are not.  The thing to note is that there’s strong social pressure to participate – largely because there is some form of social proof that makes it seem as though everyone else is doing it, too (and getting away with it). If there’s one thing that upwardly-mobile people hate, it’s the notion that they are not ‘keeping up with the Joneses’ when they quite easily could be – if they only did whatever it was the Joneses are doing to give them the status / income / happiness edge they have in the first place.

Of all the possible examples of FOMO, getting rich by playing the stock market may well be the most insidious and the most common.  Anyone with seed money can do it.  No matter how rich or poor you are, if there’s a sense that you can make (say) an “easy 15%” on your money by investing in security X or product Y and that Betty and Bob in marketing both did it (and showed you their quarter end statements to prove it), the pull is often irresistible.  This can sometimes be fodder for something called “greater fool theory.”

Most real investors say “buy low; sell high,” but it needs to be noted that there is a segment of the population that makes money by using the principle of “buy higher; sell higher.” As long as there’s a ‘greater fool’ out there who is prepared to pay even more than the outrageous price you paid for something, you can make money by paying an outrageously high price to begin with.  This is a bit like a game of chicken or musical chairs.  At some point, the market runs out of ‘fools’.  In finance lingo, that’s when the bubble bursts. Continue Reading…

Time for investors to look at the Canadian energy sector?

Image by Omni Matryx from Pixabay


By Dale Roberts, Cutthecrapinvesting

Special to the Financial Independence Hub

The Canadian energy sector has been beaten up. Foreign investors have given up and so have many Canadian investors. Where there is incredible pessimism there can be incredible rewards. But there is certainly no guarantee that the pessimism for the Canadian energy patch is not deserved. That said, it is also certainly possible that the pessimism has jumped the shark. There may be incredible value in the energy sector for Canadian investors.

Off the top I am guilty of previously piling on with the pessimism. For Million Dollar Journey I had penned on Canadian energy stocks and their dividends.

The Canadian energy sector ETFs fell by some 70% in the stock market correction of March and into April. We have seen some slight recovery as the North American and Global economic recovery takes shape.

The need for oil and gas is not going away

While I am certainly a fan of the global move to green energy solutions, the shift will take some time. Perhaps it will take decades. And even during a robust transition to renewable energy, oil and gas will continue to play a leading role. We need natural gas to heat our homes and power our economy. And while the shift to electric vehicles attracts all of the headlines and much of the attention of investors, traditional gas powered vehicle sales will continue to dominate. We will need oil for various forms of transportation.

From the IEA …

Sales of electric cars topped 2.1 million globally in 2019, surpassing 2018 – already a record year – to boost the stock to 7.2 million electric cars. Electric cars, which accounted for 2.6% of global car sales and about 1% of global car stock in 2019, registered a 40% year-on-year increase.

It’s certainly a promising trend.

Millions of global sales – Electric vehicles

From that IEA report …

The Sustainable Development Scenario incorporates the targets of the EV30@30 Campaign to collectively reach a 30% market share for electric vehicles in all modes except two-wheelers by 2030.

And all of the above takes place as overall demand for vehicles increases. The need for oil will remain with us for quite some time under most projections. Oil demand will be driven by airlines and other industrial use as well.

We’ll need to move that oil and gas

Let’s start with the pipelines that move the oil and gas around North America. The two leaders are Enbridge and TP Energy (formerly TransCanada Pipelines). These two stocks are starting to get the attention of analysts and writers. Full disclosure: I own these two companies in my concentrated Canadian wide moat portfolio. Continue Reading…

How I used to sabotage my portfolio

By Mark Seed, myownadvisor

Special to the Financial Independence Hub

Some recent reader questions prompted me to update this post – let’s go!

Dedicated readers of this site will know I spend a lot of time writing about what’s working in my financial plan and how incremental money management changes are moving us towards financial freedom every month.

Certainly if you look back at my decade in review you can see we’ve made some tremendous progress towards financial independence over time.

That doesn’t mean I didn’t sabotage my portfolio …

With all the success we’ve had to date, it wasn’t without missteps and mistakes. We’re not immune to bad decisions now and then.

In fact, we used to sabotage our portfolio and our personal finances. We really didn’t know what we didn’t know.

Financial disaster

Over the years we’ve learned some financial lessons and so today’s post updates those lessons so you don’t have to make the same mistakes I did. In fact, should you find yourself in one of these financial ruts below this post will go a step further and offer some tips on how to dig out of them.

I should know, I made these changes below!

Here is how I used to sabotage my portfolio – and what you can learn from it.

1.) Investing in high-priced mutual fund products

In my 20s, I invested in mutual funds that charged money management fees close to 2%. Back then I simply didn’t know how much those fund fees would eat into my investment returns. On top of that, I had no idea that most mutual fund managers had no long-term hope of beating their benchmark index, even after a few years let alone after many years.

This is because of this key reason: it is incredibly difficult to overcome the deficits incurred by some funds due to high money management fees charged.

High fund fees basically mean you’re already striving to play catch-up to market-like returns.

Needless to say, we don’t invest in any costly funds any longer. I ditched the mutual fund industry about a decade back now – a decision you can read about including the costly math behind it here.

This is not to say there are not a few mutual funds in Canada, and the companies that manage them, that continue to shine in terms of long-term performance – thanks to their lower-cost structure and diversified approach over their competitors. Lower-cost solutions such as Tangerine funds, Mawer funds and some TD Bank products (e-series funds) come to mind.

If you’re just starting out, you can read this post about some of those alternatives.

You can also now consider some simple all-in-one funds to help you with your investing solutions.

The bottom-line: since lower money management fees are a major predictor and input into future investing gains, it’s best to keep more of your hard-earned money working and less money going out to management fees that offer little to no long-term value.

Beyond my links above, do check out my ETFs page for some of the best, low-cost, diversified funds to own. I’ve also highlighted which ones I own and why!

2.) Lacking diversification – it’s a free lunch!

Did you see the current pandemic coming?

Can you predict gold prices later this year?

I thought so. Same here.

At the end of the day, I have no idea what the future holds. Don’t let any financial expert tell you they know either.

Nobody can predict the future with any accuracy what will happen next. This is why for long-term investing success we should strive for diversification, but it wasn’t always that way for me.

In those aforementioned 20s, the younger My Own Advisor Do-It-Yourself (DIY) investor threw tons of money into tech stocks in the late-1990s. The internet (for those millennials reading this post!) was actually a new thing then. Continue Reading…