Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Canadian Financial Summit 2020 is now online

The four-day Canadian Financial Summit 2020 edition kicks off at 8 pm EST (5 pm PST) tonight (Oct. 14): an all-virtual event featuring 30 personal finance speakers and financial bloggers. You can get tickets and catch up here. Tickets are free via the website.

After kicking off with a webcast tonight, the online event runs till this Saturday, October 17.

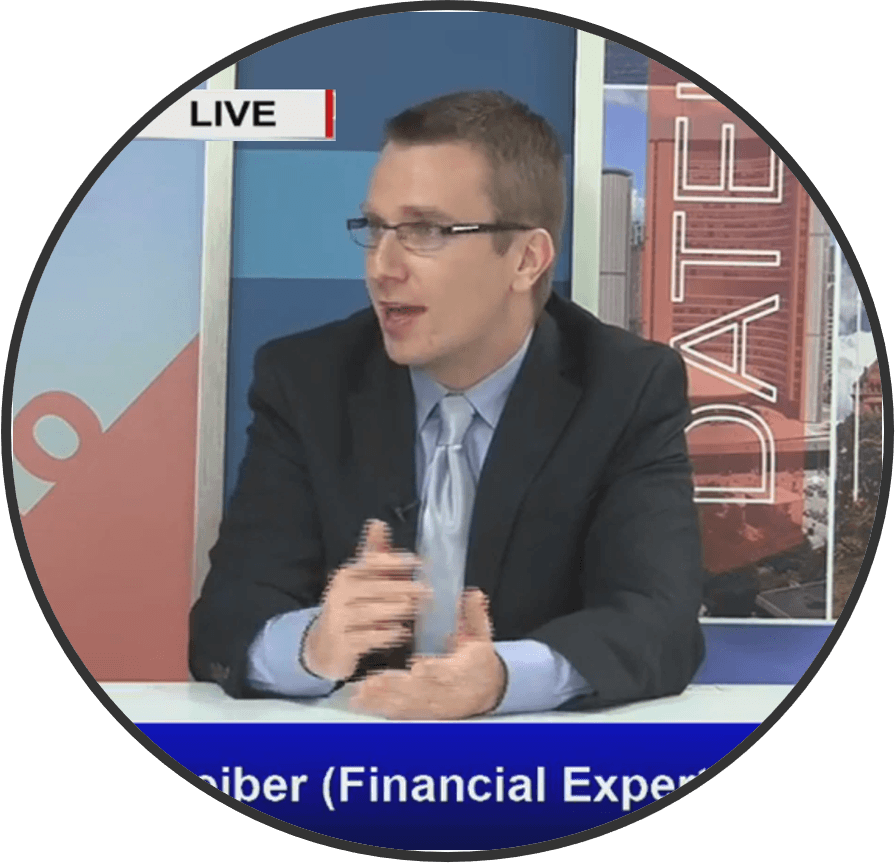
Kornel Szrejber

The summit’s host is Kornel Szrejber, who runs the finance and investing podcast The Build Wealth Canada Show.  Szrejber [pictured right] says on the site that he became one of Canada’s youngest retirees at age 32 (“before I got bored and took on the Podcast and Summit as passion projects,”) following a career in the financial planning and investing industry.

The event will also feature the experiences of two others who are among Canada’s youngest retirees, Kristy Shen and Bryce Leung, who will pass on their wisdom about how they reached retirement at so tender an age.

Scheduled speakers include Rob Carrick of the Globe & Mail, former Toronto Star financial columnist and consumer advocate Ellen Roseman, and Financial Post columnist Peter Hodson.

There are also several names that should be familiar to regular Hub readers: BoomerandEcho’s Robb Engen, MyOwnAdvisor’s Mark Seed and certified financial planner Ed Rempel. (The Hub often republishes their blogs.)

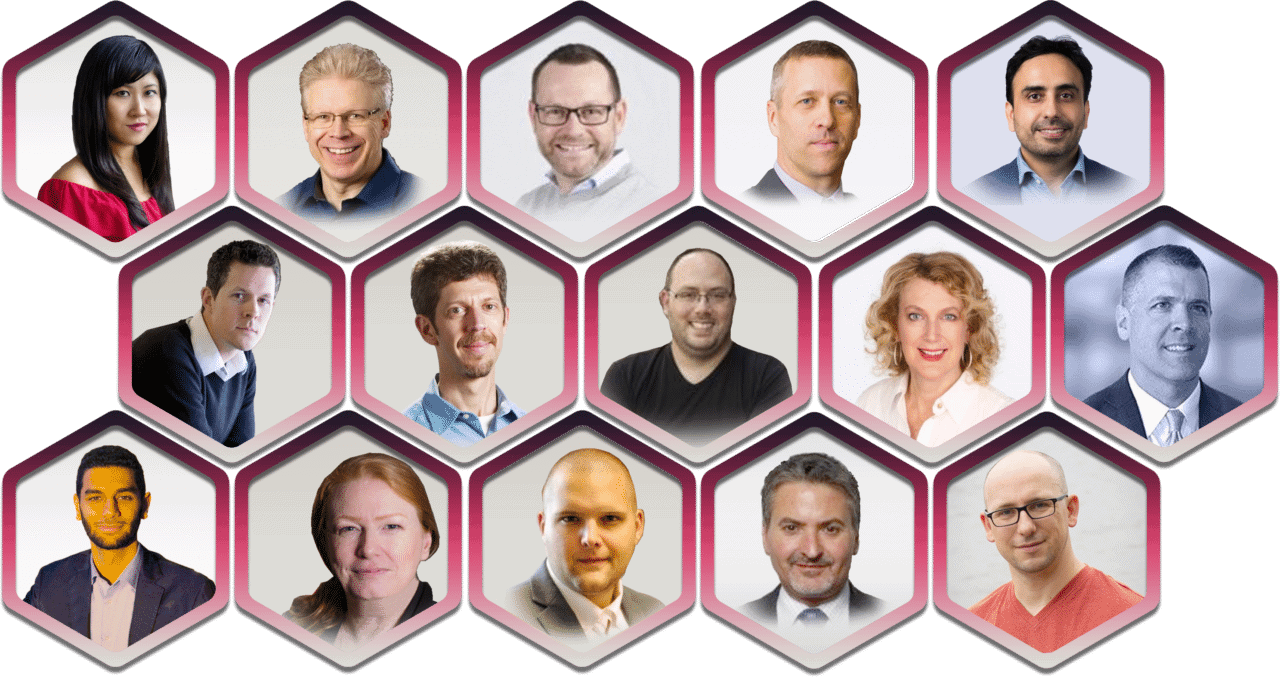
You can see some of the other speakers below, including Tom Drake, Kyle Prevost and other well known bloggers and personal finance gurus.


Continue Reading…

6 ways to save money by upgrading your Place of Business

Photo: Pexels-Pixabay

By Sia Hasan

Special to the Financial Independence Hub

No one likes the sting of putting out money for building repairs, but if your initial investment could save you hundreds, maybe thousands of dollars, it’s well-worth the momentary pain. These same upgrades will also help you avoid costly damage that would end up making a bad situation even worse. If you’re the owner of a business or company, here are six commercial upgrades that could keep you in the green.

Get into hot water

Most people try to stay out of hot water, but the fact is that everyone needs it and it can get expensive if your heater isn’t efficient. When your hot water tank is old, rusty or leaking, don’t try to squeak by for another year. For example, if you live in California, contacting a water heater company in Granada Hills and changing out that old tank, or selecting a newer “tankless” system, will start saving you money right away. Once you’ve got a new tank in, always remember to keep the water temperature just hot enough and never on the highest setting, and you’ll see the difference in your bill.

Change out your bulbs

Changing out your company’s lighting is the easiest tip you probably never thought of. In a place of business, lights are in use all day, every day, so why not save every penny you can? Switching your regular incandescent bulbs to energy-saving LED bulbs will use 75% less energy. They also last 25 times longer than regular bulbs! In a building where the lights are on all day and possibly all night, switching to LEDs will save you significant money.

Weatherize the Building

Just like you save energy at home, you should do the same at your workplace and weatherization is just the ticket. For example, you know that drafty area everyone complains about? That’s hard-earned money going right out the window. Before you lose any more, now’s the time to seal up or replace those loose fitting windows and doors, making the building attractive as well as efficient. If your office gets extremely cold during chilly days, consider brand new insulation or adding to what you already have.

Take advantage of the Sun

More and more businesses are deciding to harness the energy of the sun to help with costs. Using solar power can greatly reduce your electric bill, but is most compatible with larger establishments that have the space to install an adequate size system. Continue Reading…

Strategies for Self-Managed Portfolios

By Del Chatterson

Special to the Financial Independence Hub

First the disclaimer: I am not an expert. Certainly not a certified financial planner or financial advisor. But I have managed my own portfolio for more than thirty years and I’m willing to share the strategies that worked for me and might work for you.

Like the Random Ramblings of Uncle Ralph in my book of advice for entrepreneurs, Don’t Do It the Hard Way [shown on the left], I strongly believe in the value of learning by sharing stories and ideas with my fellow adventurers in life, business and investing. Based on my experience in successfully growing an investment portfolio over several decades, these are my suggestions for your consideration.

Start with educating yourself. Learn from the experts. Read Warren Buffett’s bible, the Intelligent Investor by Benjamin Graham, to understand the basic principles of investment analysis and value investing. (The technical details may be beyond your understanding and are probably more than you need or want to know.) Look at current recommendations and valuation assessments of competent financial analysts to understand their processes and the factors that most affect future prospects for any business. You’ll discover that while there may be consensus, there is never unanimity. Learn to evaluate businesses against the criteria used to identify the top performers in Built to Last and Good to Great by James Collins and Jerry Porras. You will gain confidence and learn to trust your own analysis and instincts to select investments in businesses that you also understand, like and respect. Would you buy from this company? Would you like to work for this company?

Start to build your self-managed portfolio with an online direct-investing resource. You may choose to gradually transition from your current advisor or financial planner as you gain confidence, before deciding whether or not the results justify their fees for portfolio management services. You may decide not to interfere with their good management and avoid taking on the responsibility of managing your own portfolio.

Although I’ve been satisfied with my own portfolio management, I’ve still left some of the family portfolio with an investment advisor. I don’t want all the financial responsibility and it continues to give me a convenient comparative benchmark and resource for evaluating my own portfolio management. But if you’re confident in your knowledge and analysis and in your ability to remain calm, cautious and patient through the inevitable crises and extended downturns, then you’re ready to take charge and do it yourself for some of your investment portfolio.

At this point, the decision depends on your confidence, interest and ability to achieve better performance at lower cost. Although, the rationale for assuming management of a self-directed portfolio can range from loving the challenge and the learning experience to the thrill of taking risks and enjoying the entertainment spectacle of volatile and irrational markets.

If you do decide to start building and managing your own portfolio, it is essential to give yourself some key ground rules related to risk and return, just as you would give your risk tolerance profile and return expectations to your financial planner. Control your impulses with restraining limits on the amount of individual investments and the criteria for risk-reducing diversification. My two overriding guidelines: never more than ten percent of the portfolio in any one investment and never less than fifteen distinctly different investments. Continue Reading…

When the top 1% advises everyone else

By John De Goey, CFP, CIM

Special to the Financial Independence Hub 

Like most Canadians, financial advisors exist all over the income spectrum.  The major difference is that a disproportionate number of them are highly successful.  That should come as no surprise.  Many would-be clients are comforted by this and some even seek out advisors who are conspicuously successful because obvious opulence is a double form of social proof. First, it implies that advisor is good at what he does by using the rough correlation that financial success and financial savvy correlate highly.  Second, it implies that the client has “made it” by being able to afford the services of someone so obviously brilliant.

In 2020, the top tax bracket [in Canada] kicks in at $214,368, which is just below the threshold for being a one percenter.  It’s only natural that smart, forward-looking professional advisors should attract the smartest and most forward-looking clients.  One percenters.  Similarly, it’s only natural that the most desirable would-be clients should seek out the best advisors.

In some endeavours, merit and talent are difficult to discern.  For instance, doctors are paid through public health programs.  That likely makes it harder to tell which are good and which are not.  Other fields, such as law and accounting, allow for a more conspicuous assessment based on the social norms of affluence.  Basically, the superior professionals can signal their desirability through how they dress, the car they drive, the watch they wear and (if it comes to that) the neighbourhood they live in.  For better or worse, many would-be clients look to these social cues as evidence of competence and excellence.

Jury is out on whether advisors should be like the client

This exercise could have implications for the provision of financial advice.  Many people recommend that, when looking for an advisor, one should actively seek out someone who is more or less like themselves.  In terms of demographics, geography, values and the like, the theory goes that there’s simply a better chance of getting a good fit if you look for an advisor who is like you.  I don’t know how statistically robust the theory is, but it makes sense intuitively.  Of course, online dating sites make similar recommendations and offer similar results.  The jury is out.

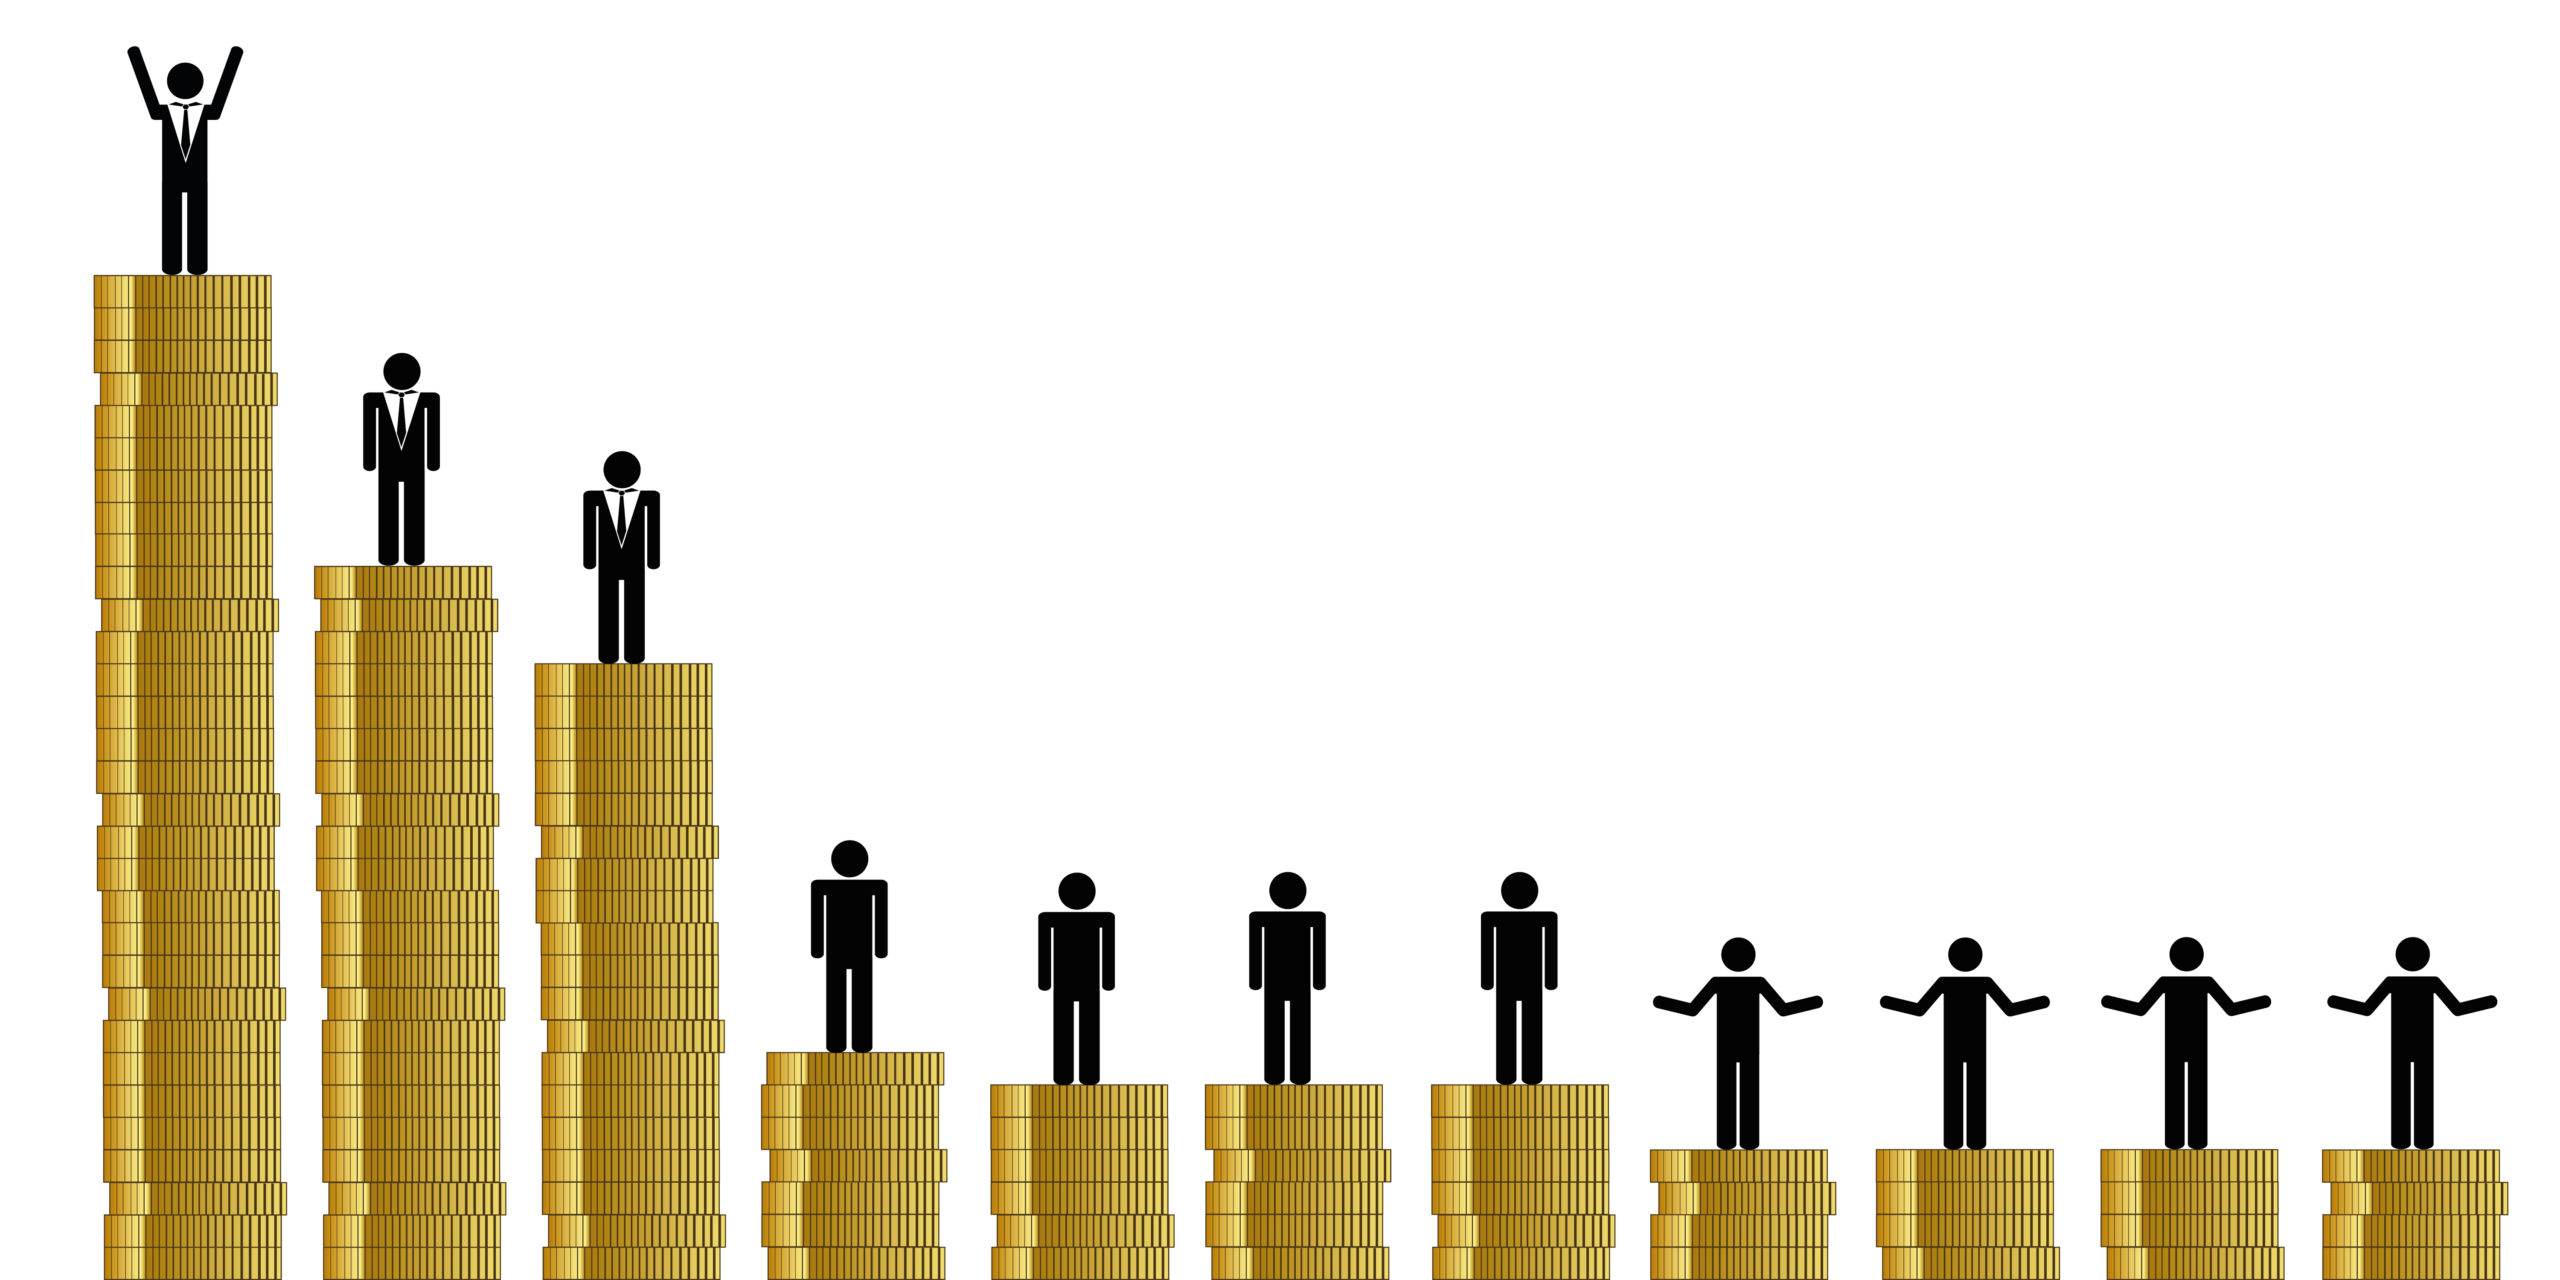
If you were to divide Canadians into five equal groups, with each representing a 20% portion of income earners, the top quintile (80% to 100%) would be earning more than the national average (on average), the second quintile (60% to 80% would be earning about the same as the national average (on average) and the three lowest groups (0% to 60% collectively), would all be earning lower than the national average.

Top 20% earn half the disposable household income

The top quintile (20%) earn about half of all disposable household income in Canada.  Perhaps people in the second quintile (top 60% to 80%) might also want and need advice.  It is the second quintile is the most representative of the Canadian average.  It’s this second 20% of the people that also represents about 20% of the disposable income. Beyond that point, however, many people are simply living paycheck to paycheck and saving little or nothing for down the road.  Continue Reading…

Should I take the Commuted Value of my pension?

By Mark Seed, MyOwnAdvisor

Special to the Financial Independence Hub

Breaking up is hard to do.

Or is it – when it comes to your employer?

Whether that is voluntary leave or involuntary leave, at some point, some people are faced with a very important financial decision: should I take the commuted value of my pension?

This post will hopefully provide some insights, based on a reader question, including my own situation with my pension to share any considerations as food for thought!
Pensions 101

I already have a very detailed post on pensions including the introductory basics on my site so I won’t repeat all details here, but I think it’s very important to understand there are two main types of pensions that we’ll talk about today:

  • Defined Contribution (or DC for short), and
  • Defined Benefit (DB).

The difference?

Think of your DC plan just as the words sound – your contribution is defined but ultimate pension value is not. Meaning, there are no promises. You’ll get what you’ll get based on what you invest in and the returns of what you invest in over time.

Think of your DB plan this way – your (pension) benefit is defined – meaning your pension value at the end of the line is known, usually based on a formula with your company that goes something like this:

Best Average Five Years’ Salary x Benefit Percentage x Years of Plan Membership = Annual Pension Income

So, using real numbers it could be this for some:

$60,000 x 1.5% x 25 = $22,500

Here is a quick pension comparison summary worth noting:

  Defined Contribution (DC) Plan Defined Benefit  (DB) Plan
Philosophy  Assisting employees accumulate retirement savings during their career. Rewarding long-service employees with a lifetime retirement income.
Investment Decision Employees decide how contributions are invested in (usually) a limited number of funds. Professional money managers look after investment decisions based on strict guidelines.
Investment Risk Employee bears the investment risk (since they selected the investments). Employer bears the investment risk.
Income at retirement  Based on employer and employee contributions and investment performance. Based on a formula that includes your annual earnings and years of service.
Valuing Your Pension Simple, as employees have their account balance readily available. Difficult, the commuted value is not readily available for most pension plans (except at termination). Actuaries help calculate.
Other notes My wife has this plan. I have this plan 🙂

What happens when you leave the organization and you have a pension?

When leaving your employer, if you have a DC plan, things are rather straightforward.

If you own a DC plan, the full market value of that plan at the time of your leave can be transferred to a personal Locked-In Retirement Account (LIRA).

I won’t go into too many details on LIRAs since as you guessed it, I also have other blogposts about that subject including how I manage my LIRA. (I used to have a DC plan when I worked and lived in Toronto. I moved my DC plan money into a LIRA when I left my former employer. I’ve had this LIRA ever since.)

With a DB plan, it’s a bit more complex to say the least. Which brings us to our reader case study for today and my thoughts and comments on that.

Reader Case Study (questions and information adapted slightly for the site):

Hi Mark!

I really enjoy your blog! 

I also really like your concept of hourly passive income wage – it’s something I’m now tracking myself!

Thoughts on this for us although I know you can’t offer specific advice but your perspectives would be good given I have read you have a pension as well. Continue Reading…