Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

5 common financial mistakes Millennials are making

By Noel Gonzales

Millennials have many opportunities in their hands today. With their skills and talent, they can earn more and do more with their lives. However exciting this is, it also becomes quite a challenging task for millennials to use wisely what they have.

Today’s trends on consumerism entice people to buy and spend more when they earn more, and this is where the trap of debt begins. Aside from this, here are five other common financial mistakes that millennials are making:

1.) Millennials don’t invest in the stock market or other financial markets

Millennials are tech-savvy, and most own a smartphone. Hence, investing in the stock market is not difficult to do nowadays. However, a lot of people, including millennials, still consider traditional savings as the way to go; they’re unaware that stocks grow more income than savings.

If you’re confused with how to start, you can take advantage of online resources and tools that can do the following:

  • Teach the basics of financial markets and investing.
  • Maximize your income, like a great position size calculator, that decides the estimated amount of currency units to buy or sell.

In investing, the younger you start, the better. If you start early, you’d surely thank your young and smart self 10 years from now.

2.) Millennials don’t invest in health insurance

Health insurance is a good investment for your future, as you have a shield that covers all your costs in the event of any health issues. Remember, health is your greatest asset. Illness can be very expensive, but when you have health insurance, your expenses are covered and you can focus on recovering.

There are now easy payment plans on health insurance, depending on your salary. You’ll be surprised to know that paying your insurance premiums can cost you less than the money you spend on your daily coffee run.
3.) Millennials don’t have an emergency fund  

As a millennial, you’re at the top of your health and age. Hence, you forego saving for an emergency fund. An emergency fund refers to money set aside to cover:

  • Emergency travel, such as when you need to go home because a family member died
  • Home repairs after a natural disaster
  • Sudden job loss

You should have at least three to six months’ worth of your monthly expenses as savings for emergencies. For example, if you spend a total of 500 USD every month to cover living expenses, home loan, etc., 3000 USD should be your emergency fund.

4.) Millennials don’t write a monthly budget

Not writing down a monthly budget is a mistake that can lead you to overspend. When you write your budget down, you can visualize it better and stick to it; hence, you know where and how to allocate your money efficiently. Continue Reading…
Which All-in-one, One-ticket Portfolio Is right for you?

By Dale Roberts, CuttheCrapInvesting

Special to the Financial Independence Hub

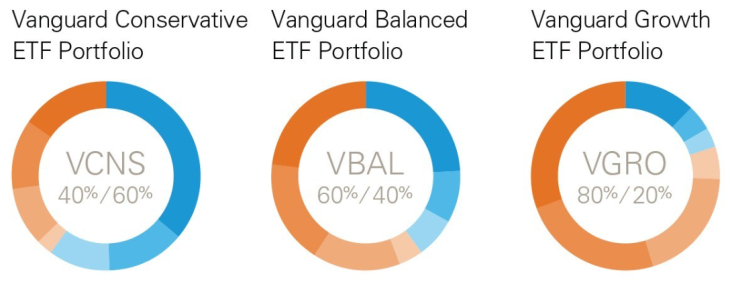
In February 2018 Vanguard Canada changed the investment game in Canada with the launch of complete Balanced Portfolios that you can purchase by entering one ticker symbol. For example, once logged into your discount brokerage account you would enter the symbol VBAL, and press buy to get a complete globally diversified Balanced Portfolio. The Portfolio is 60% Canadian, US and International stocks with 40% of those shock absorbers known as bonds.

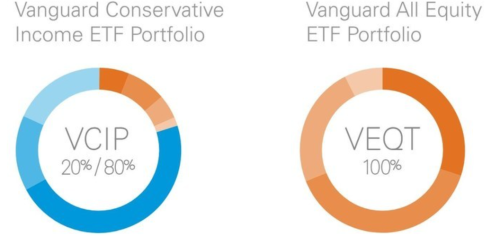
Vanguard offers One-ticket Portfolios at five different risk levels.  With an MER of .22% these portfolios are a game changer. (In the pie charts below, Orange shows equities and blue fixed income percentages). 


iShares has also had One-ticket solutions available for several years. The asset allocation was ‘weird’ and the fees were not that low. considering the low fees on the underlying ETF assets. In response to Vanguard, iShares recently took the scrub brush to the funds, cleaned up the asset allocations and then cut the fees. In fact they undercut Vanguard just slightly with an MER of .20%. Here’s the link to the iShares product page; this will take you to XBAL, their Balanced Portfolio.

And then last week along comes one of the big banks with their own One-ticket offering. Here’s my review at the Hub: BMO keeps it simple with its One-ticket Portfolio Solutions.


The one-ticket solutions are the most cost-effective managed portfolios available in Canada. This should be the final dagger in the heart of the high fee mutual fund industry.

Which One-ticket provider is best?

Let’s call it a draw. The portfolios are equally great. They include the basic and sensible asset allocation building blocks of Canadian, US and International stocks supported by a bond component. All the One-ticket providers use Canadian and foreign bonds to manage the risks.

How to select the right portfolio

Nothing is more important than investing within our risk tolerance level. We could argue it is the most important ‘part of it all.’ The Portfolios do not come with an owner’s manual for when and how to use them. Matching the appropriate portfolio to your risk tolerance level, time horizon and objective is key.

We have to invest within our risk tolerance level; bad things happen when we invest outside of our comfort level – usually permanent losses. We must be comfortable with the percentage and dollar value that the portfolio could decline.

Are you comfortable with a portfolio that could decline by 5% in a major correction, 10%, 20%, 30%, 40% or 50%?

Remember those bonds work like shock absorbers to soften the blow and smooth out the ride during periods when the stock markets tank.  And tank they can; Canadian and US and International markets have declined by some 50% or more twice in the last 20 years. Continue Reading…

Franklin Templeton Canada unveils suite of low-cost passive Regional and Country ETFs

On the heels of BMO’s entry into the low-cost asset allocation ETF space (see Hub blog here), one of the world’s largest active money managers has unveiled a suite of low-cost passively managed regional and country ETFs for the Canadian market.

Franklin Templeton Investments Canada today announced the expansion of its Franklin LibertyShares ETF offerings with its first suite of passive ETFs. (Franklin LibertyShares originally entered Canada in 2017 with four actively managed funds branded as Franklin LibertyShares).

The new passive funds gives investors exposure to a specific region or country at rock-bottom fees (below 10 basis points). It says (and I agree) that the management fees for these new Canada, United States, Japan and Europe (excluding U.K.) passive ETFs are amongst the lowest in the industry, ranging between 5 to 9 bps.

The company says these include the first Japan passive ETF and Europe (excluding U.K.) passive ETF available on a Canadian exchange. The ETFs are market-cap weighted.

In a press release, Franklin Templeton Investments Canada president and CEO Duane Green said: “With market-moving events like trade tensions and Brexit, investors and their advisors as well as institutional investors are looking to precisely act upon specific country and regional market views … These new passive ETFs provide Canadian investors with individual country and regional exposure options … at a very low cost.”

Here are the new ETFs and their ticker symbols:

Franklin FTSE Canada All Cap Index ETF (FLCD) invests primarily in equity securities of Canadian issuers, seeking to replicate the performance of FTSE Canada All Cap Domestic Index. The management fee is 5 bps.

Franklin FTSE U.S. Index ETF (FLAM) invests primarily in equity securities of mid- and large-capitalization U.S. issuers, seeking to replicate the performance of FTSE USA Index. Management fee is 7 bps.

Franklin FTSE Japan Index ETF(FLJA) invests directly or indirectly, primarily in equity securities of mid- and large-capitalization Japanese issuers, seeking to replicate the performance of FTSE Japan Index. Fee 9 bps.

Franklin FTSE Europe ex U.K. IndexETF(FLUR) invests primarily in equity securities of mid- and large-capitalization issuers in developed markets in Europe excluding the United Kingdom, seeking to replicate the performance of FTSE Developed Europe ex U.K. Index. Fee 9 bps. Continue Reading…

BMO keeps it simple with its One-ticket Asset Allocation ETF portfolios

Last week we witnessed another entry into the Canadian Asset Allocation One Ticket Portfolio Solutions.

Welcome BMO.

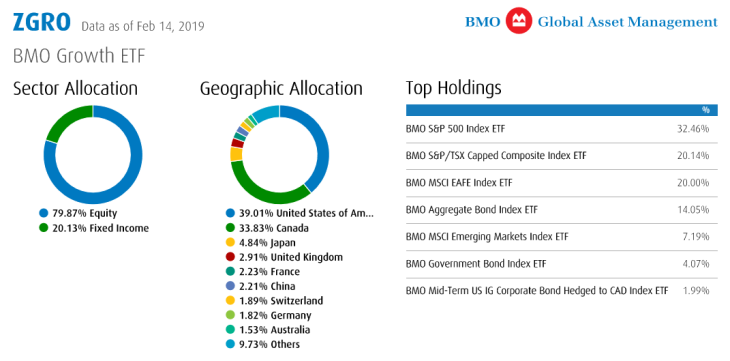
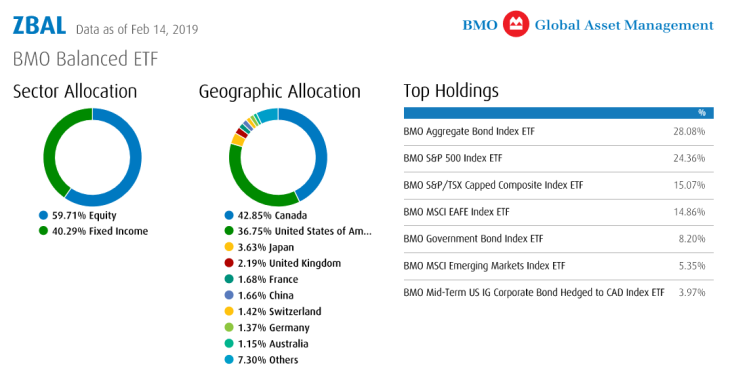
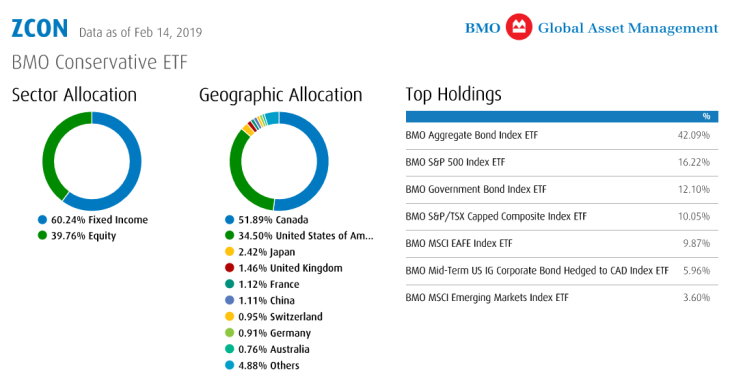
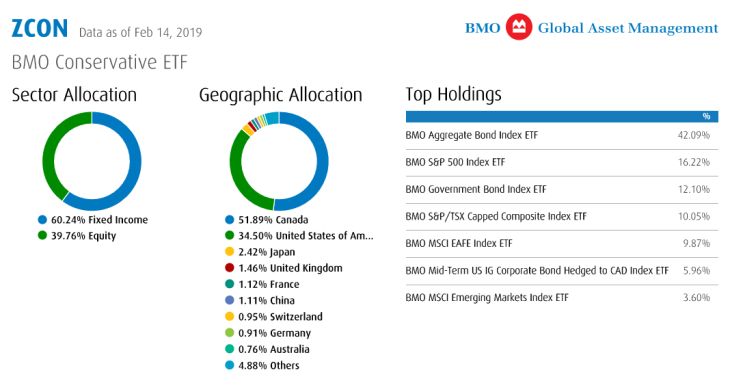
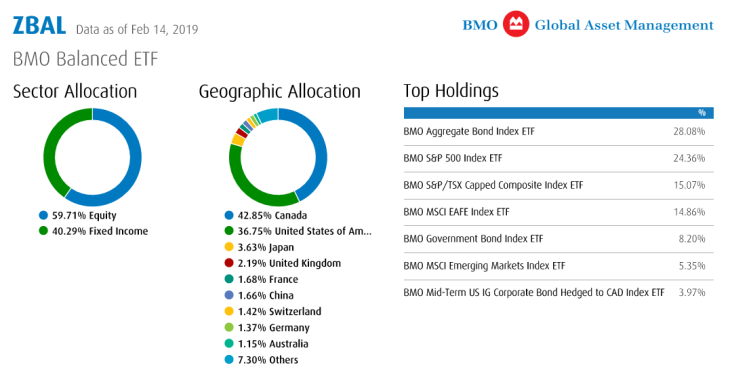
On Friday February 15th BMO launched three asset allocation portfolios by way of the Conservative ZCON, the Balanced ZBAL and the Growth ZGRO.

Here is the overview from the Fact Sheets:

Wonderfully simple or plain vanilla?

Take your pick. These are certainly plain vanilla, they’re not even Lemon Raspberry White Chocolate. But they’re still wonderful.

I am certainly surprised that BMO Global Asset Management kept the portfolios so clean and simple. As you may remember from my review of the BMO SmartFolio. the Robo Portfolios are actively managed. That is to say there is active asset allocation with respect to the core and smart beta ETFs. From my BMO SmartFolio review …

The portfolios will be rebalanced every 2 to 6 months. And back to that human touch, the management team with also make adjustments to that asset mix based on market conditions. They may be more active in periods of market turmoil compared to the current market conditions where we are mostly cruising to the upside for Canadian, US and International stocks. Continue Reading…

Volatility arrived in 2018 but the ETF Exodus didn’t

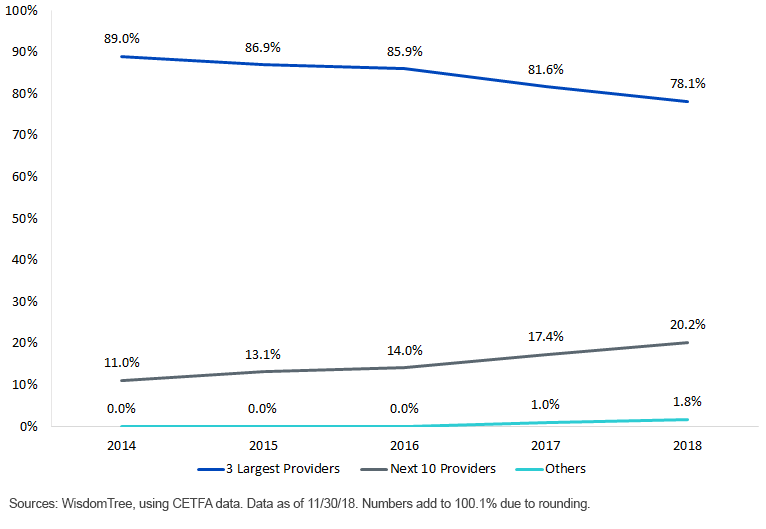
Figure 1: Market Share, Canadian ETFs

By Jeff Weniger, WisdomTree Investments

Special to the Financial Independence Hub

 Money managers had a rough year in 2018. The S&P/TSX Composite Index was off 8.8%, while the MSCI World Index of global equities was down 0.1% in Canadian dollar terms. About the only bright spot was the S&P 500 Index, which was down 4.4% in USD but up 4.1% for Canadians because of U.S. dollar strength. But these tepid figures mask the freefall’s extent; many markets met the bear market definition — declining more than 20% — inside the confines of Q4.

Figure 1 above grabbed attention in our 2019 Canadian ETF Industry & Market Outlook. Many didn’t realize how much market share the smaller players have gobbled up recently.

No doubt, the biggest ETF providers are doing just fine. In fact, we imagine most of the 33 Canadian ETF companies in our corner of the asset management industry must be downright giddy. Many are hitting the sweet spot where track records are becoming seasoned, brand recognition is solidifying and product users are now proselytizing for them.

Grasping at straws

“Active” mutual fund managers have for years been tossing around a prediction that needs to be checked at the door.  To paraphrase them: Wait until we see a downturn in stocks. That’s when everyone is going to dump their ETFs and come back to active mutual funds.

Be careful what you wish for; we think the exact opposite.

The stock market peaked in September, but the exodus from ETFs and into mutual funds never materialized. As an industry, our collective AUM is ever so slightly off its peaks, but that’s because of market losses, not outflows. Continue Reading…