Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

How to build the best long-term stock portfolio for retiring in Canada


Diversification, RRSPs, and compounding interest are important topics for investors building portfolios for retiring in Canada

Long-term stock investment strategies aren’t built to make a fast dollar. They are built to prosper over time, and most important, teach you how to pick the right stocks. Retiring in Canada can be easier if you follow our tips for building a long-term stock portfolio.

Retiring in Canada: Diversify your holdings to create a long-term retirement portfolio

One of our key rules for successful investing is to maintain a diversified stock portfolio. This means spreading your money out across most, if not all, of the five main economic sectors: Manufacturing & Industry; Resources & Commodities; Consumer; Finance; and Utilities.

Here are some additional suggestions to prepare investors for retiring in Canada:

  • When it comes to a diversified stock portfolio, stocks in the Resources and Manufacturing & Industry sectors expose you to above-average share price volatility.
  • Stocks in the Utilities and Canadian Finance sectors entail below-average volatility.
  • Consumer stocks fall in the middle, between volatile Resources and Manufacturing companies, and the more stable Canadian Finance and Utilities companies.

Most investors should have investments in most, if not all, of these five sectors. The proper proportions for you depend on your temperament and circumstances.

Conservative or income-seeking investors may want to emphasize utilities and Canadian banks for their high and generally secure dividends.

Long-term value investing is a key part of building a balanced and diversified portfolio

The core of the long-term value investing approach is identifying well-financed companies that are established in their businesses and have a history of earnings and dividends. They are likely to survive any economic setback that comes along, and thrive anew when prosperity returns, as it inevitably does.

When you look for stocks that are undervalued, it’s best to focus on shares of quality companies that have a consistent history of sales and earnings, as well as a strong hold on a growing clientele.

Here are three of the financial ratios we use to spot them:

  • Price-earnings ratios
  • Price-to-sales ratios
  • Price-cash flow ratios

A long-term investment strategy for retiring in Canada maximizes compound interest

Compound interest — earning interest on interest — can have an enormous ballooning effect on the value of an investment over the long-term. It can be considered the mother of all long-term investment strategies. This tip is especially important for young investors to learn. The benefits of this stock trading tip apply to both dividend-paying stocks and fixed-return, interest-paying investments such as bonds. When you earn a return on past returns, the value of your investment can multiply. Instead of rising at a steady rate, the number of dollars in your portfolio will grow at an accelerating rate.

To profit from this tip, you need to pay attention to steady drains on your capital, even seemingly small ones: like high brokerage commissions. If you’re losing (or missing out on a profit of) even 1% a year, it can have an enormous draining effect on your investments over a decade or two.

Registered Retirement Savings Plans as an option for retiring in Canada

Registered Retirement Savings Plans, or RRSPs, are a form of tax-deferred savings plan. RRSP account contributions are tax deductible, and the investments grow tax-free. When you begin withdrawing funds from your RRSP, they are taxed as ordinary income. RRSPs are the best-known and most widely used tax shelters in Canada.

Bonus tip: If you’re retiring in Canada soon, you should switch your RRSP to a registered retirement income fund (RRIF)

Why should you switch your RRSP to a registered retirement income fund (RRIF) if you’re retiring soon in Canada: as opposed to other options?

If you have one or more RRSPs, you’ll have to wind them up at the end of the year in which you turn 71. We think converting your RRSP to a RRIF (registered retirement income fund) is the best option for most investors. You have three main retirement investing options:

  • You can cash in your RRSP and withdraw the funds in a lump sum. In most cases, this is a poor retirement investing option, since you’ll be taxed on the entire amount in that year as ordinary income.
  • You can purchase an annuity.
  • Proceed with the RRSP to RRIF conversion.

Converting your RRSP to RRIF is the best retirement investing option for most investors. That’s because RRIFs offer more flexibility and tax savings than annuities or a lump-sum withdrawal.

Like an RRSP, a RRIF can hold a range of investments. One convenient thing to note about the RRSP-to-RRIF conversion process is you don’t need to sell your RRSP holdings when you convert: you simply transfer them to your RRIF.

Retiring in Canada can be easier if long-term strategies are used. Have you employed any short-term investment strategies to prepare for retirement, and if so, how have they performed for you?

If you’ve already retired, what investment tips would you offer to those just planning their retirement finances?
 

Pat McKeough has been one of Canada’s most respected investment advisors for over three decades. He is the founder and senior editor of TSI Network and the founder of Successful Investor Wealth Management. He is also the author of several acclaimed investment books. This article was originally published in 2017 and is regularly updated, most recently on July 10, 2018. It is republished on the Hub with permission. 

ETF investors sitting comfortably in the Balanced Growth sweet spot

By Dale Roberts
Special to the Financial Independence Hub

In October I penned this blog post, The Balanced Growth Portfolio. The Investor’s Sweet Spot. A Balanced Growth model with typically be in the area of 70-80% in stocks and the remainder in bonds. It’s a growth portfolio, but with a modest allocation to bonds to reduce the price risks. As I often write, those bonds work like shock absorbers through market volatility or market corrections. They help smooth out the ride.

I’d call this model the sweet spot as it might offer the best balance of very good total return potential with less risk compared to an all-stock portfolio. It many periods it will deliver the best risk-adjusted returns.

In fact, in many periods the Balanced Growth portfolio model can deliver the same returns as an all-stock model, while taking on less risk. Stock market corrections become the great equalizer. The pure equity model will certainly outperform in a long bull market run, but then the stock market corrections come along and bring the stocks down to earth while the Balanced Growth model then moves into the lead. They might play a game of tortoise and the hare for many years or decades.

See my above post link for charts on that comparison.

Let’s look at the ETF holdings of Canadians

Industry statistics are published by the Canadian ETF Association. You can access the December 2018 report and commentary here.

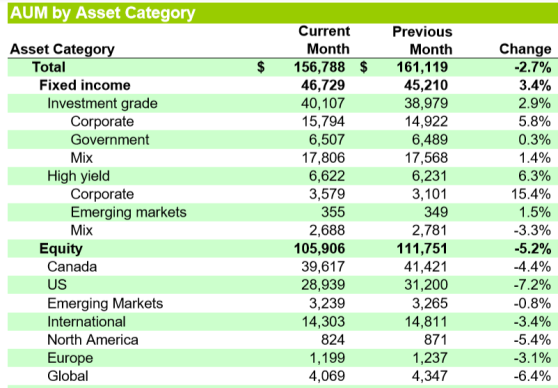
The chart at the top of this blog shows the monthly breakdown of assets held in ETFs. Current Month is month’s end December 2018, Previous Month is November, of course. Keep in mind that the assets will be affected by the total inflows and outflows (purchases and sells) and also the market variance. The stock markets fell in December and that will bring down the total stock assets number.


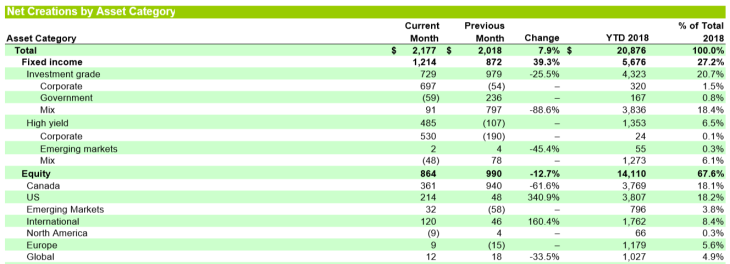
We see that Canadian ETF investors are in that sweet spot of near 70% equities and 30% bonds. And the good news is that while the stock markets were pulling their little December hissy fit, investors were adding new monies to their ETFs: both Fixed Income and Equities. And you’ll see that Canadian ETF investors are acquiring within the Balanced Growth band.

We see that investors did respond to the stock market price risks and moved more monies into the fixed income side of the ledger in December. No problem there. Sometimes Mr. Market gives us a little love tap and reminds us that markets can go down in a hurry. We get a very considerate warning shot across the bow. On that here’s my Seeking Alpha article from one year ago Mr. Volatility is Asking You, Taunting You – So You Wanna Go?

Many of us might be getting a little flabby with respect to our risk taking ability. We have not been tested much in the last decade coming out of the Great Recession. We should always remember that markets can be volatile and they can fall by some 30%, 40% or 50% or more in a major market correction. I reminded readers of those risks in my first post to the Tangerine Forward Thinking blog with Why You Might Still Want Bonds In Your Investment Portfolio.

Ensure that you know your risk tolerance level and that your portfolio is best matched to you risk tolerance level. Have a more than solid investment plan but consider that emotional risk. From that Seeking Alpha article and offered by the most ferocious heavyweight boxer of all time, Mike Tyson …

Everyone has a plan until I punch them in the face.

Yes, Mr. Market may punch you in the face one day. Are you ready? I can take a punch in the market and in the boxing ring. I grew up with a boxing ring in the backyard so that my older brother could practice punching someone in the face as he prepared for and kept in fighting shape for playing Junior ‘hockey’. He only ever lost one hockey fight. Me and my face take full credit. Mr. Market has thrown a few punches too.

All said, be prepared.

How are Robo-Advised Canadians putting monies to work? 

Keep in mind that many investors will create their own ETF Model Portfolios through their discount brokerage. But of course there’s a massive move to the Canadian Robo Advisors, where investors can access digital and human advice that will then lead to the recommendation of risk-appropriate ETF portfolios. That risk assessment is key. Continue Reading…

FP: RRSPs still have at least 3 advantages over TFSAs

My latest Financial Post column has just been published. It being the height of RRSP season, it looks at some well-known and some less well-known advantages RRSPs still have over the new kid on the block: TFSAs. Click on the highlighted text for the full story online: Three reasons why RRSPs still matter — and one of them you probably didn’t know. The article is also in Wednesday’s print edition on page FP6 under the headline RRSPs still matter despite rise of TFSAs.

The Tax-free Savings Account (TFSA), which was introduced just over ten years ago, is often described as the “mirror imaqe” of the RRSP. That is, the RRSP provides an upfront tax deduction by lowering your taxable income for the year you make the contribution. The TFSA does not, which can be a strike against it in some eyes; on the other hand, once you reach retirement, the TFSA comes into its own by NOT being taxable, and therefore not resulting in clawbacks of Old Age Security (OAS) benefits or (for very low-income seniors) the Guaranteed Income Supplement (GIS) to the OAS.

On the other hand, as many seniors are discovering to their chagrin, all those RRSP tax savings you enjoyed during your (hopefully) high-income earning years come back to haunt you: once the RRSP becomes a Registered Retirement Income Fund (RRIF) at the end of the year you turn 71 (the alternative is the unpalatable act of cashing it all out and being taxed then and there, or annuitizing), then you’ll be on the hook for forced annual — and taxable — RRIF withdrawals. Ottawa giveth and Ottawa taketh away.

But, as the FP piece argues, some decades can elapse between an RRSP contribution and the ultimate RRIF withdrawals, and when you add in the ongoing tax sheltering of an RRSP — on top of the upfront tax contribution — then the experts quoted in the piece believe the RRSP comes out, certainly if you’re at or near the top tax brackets.

Below is the arithmetic provided by Mathew Ardrey, wealth adviser at TriDelta Financial, which was too long to include in the FP version. He cites the example of someone who has $10,000 of income and can invest in either a TFSA or a RRSP:


Same tax rate
RRSP TFSA
Income before taxes to save $10,000 $10,000
Tax at 50% $0 ($5,000)
After-tax available to contribute $10,000 $5,000
FV with 5% return for 25 years $33,864 $16,932
Tax at 50% ($16,932) $0
After-tax withdrawal in retirement $16,932 $16,932
Lower tax rate in retirement
RRSP TFSA
Income before taxes to save $10,000 $10,000
Tax at 50% $0 ($5,000)
After-tax available to contribute $10,000 $5,000
FV with 5% return for 25 years $33,864 $16,932
Tax at 25% ($8,466) $0
After-tax withdrawal in retirement $25,398 $16,932
Higher tax rate in retirement
RRSP TFSA
Income before taxes to save $10,000 $10,000
Tax at 25% $0 ($2,500)
After-tax available to contribute $10,000 $7,500
FV with 5% return for 25 years $33,864 $25,398
Tax at 50% ($16,932) $0
After-tax withdrawal in retirement $16,932 $25,398


Tridelta Financial’s Matthew Ardrey

“The part of the example I would focus on, is what is a reality for many Canadians, their income is higher while they are working than in retirement. Because of this, there is a clear advantage of receiving the deduction at a higher marginal tax rate and paying tax in retirement at a lower marginal tax rate,” Ardrey concludes.

Foreign income taxed less harshly in RRSPs than TFSAs

But that’s not all! As the FP column mentions, there are at least two other advantages RRSPs have over TFSAs. One is that foreign income is taxed more in TFSAs than in RRSPs: Continue Reading…

Vanguard unveils 2 more Asset Allocation ETFs

A year after Vanguard Canada shook up the ETF industry with its ground-breaking suite of three Asset Allocation ETFs (VGRO, VBAL, VCNS) it today followed up with two new iterations, bringing the total to five.

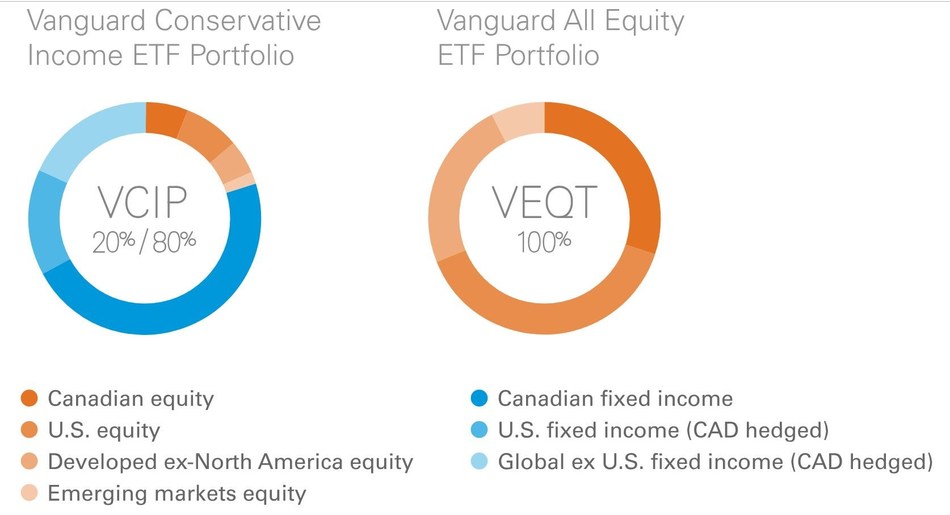
As you can see from the adjacent illustration, the two new ETFs include an all-equity ETF, VEQT; and a very conservative fund, VCIP, dubbed the Vanguard Conservative Income ETF Portfolio, which is 80% in fixed income. (The previous conservative entry, VCNS, was 60% fixed income). Both new ETFs begin trading on the TSX today.

Note that the color key above applies to BOTH funds: that is, Orange refers to four equity ETFs contained in both funds; blue refers to the three fixed-income ETFs that are present only in VCIP, since VEQT is 100% equity/orange. At least one sharp-eyed reader has noted the potential for confusion here.

In any case, the original suite of three ETFs were hailed by the financial press, including Yours Truly here and for the MoneySense ETF All-stars. The newcomers are further along the risk spectrum (100% equities) or further along the conservative income spectrum. And consumers have responded, injecting more than $1 billion into them, according to Kathy Bock, Managing Director of Vanguard Investments Canada Inc. Vanguard Canada now offers 39 ETFs, containing a total of C$17 billion in assets under management.

Here is the description of the two new ETFs contained in a press release:

Vanguard Conservative Income ETF Portfolio (TSX: VCIP) – The Vanguard Conservative Income ETF Portfolio seeks to provide a combination of income and some long-term capital growth by investing in equity and fixed income securities with a strategic allocation of 20% equities and 80% fixed income, made up of seven underlying Vanguard index ETFs.

Vanguard All-Equity ETF Portfolio (TSX: VEQT) – The Vanguard All-Equity ETF Portfolio seeks to provide long-term capital growth by investing primarily in equity securities with a strategic allocation of 100% equities, made up of four underlying Vanguard index ETFs.

Vanguard Canada head of product Tim Huver said “Canadian investors have embraced our ‘all-in-one’ asset allocation ETFs based on their sound portfolio construction, low-cost and simplicity. These ETFs have been among our most popular over the past year and we are committed to giving Canadians greater flexibility by offering two new investing options on both sides of the risk profile spectrum.”

The Beginner’s Guide to RRSPs

More than sixty years after the federal government introduced the Registered Retirement Savings Plan as a vehicle to save for the future, RRSPs still remain one of the cornerstones of retirement planning for Canadians. In fact, as employer pension plans become increasingly rare, the ability to save inside an RRSP over the course of a career can often make or break your retirement.

Here’s a beginner’s guide to RRSPs:

The deadline to make RRSP contributions for the 2018 tax year is March 1st, 2019.

Anyone living in Canada who has earned income can and should file a tax return to start building RRSP contribution room. Canadian taxpayers can contribute to their RRSP until December 31st of the year he or she turns 71.

Contribution room is based on 18 per cent of your earned income from the previous year, up to a maximum contribution limit of $26,230 for the 2018 tax year. Don’t worry if you’re not able to use up your entire RRSP contribution room in a given year: unused contribution room can be carried-forward indefinitely.

Keep an eye on over-contributions, however, as the taxman levies a stiff 1 percent penalty per month for contributions that exceed your deduction limit. The good news is that the government built in a safeguard against possible errors and so you can over-contribute a cumulative lifetime total of $2,000 to your RRSP without incurring a penalty tax.

Find out your RRSP deduction limit on your latest notice of assessment or online using CRA’s My Account service.

You can claim a tax deduction for the amount you contribute to your RRSP each year, which reduces your taxable income. However, just because you made an RRSP contribution doesn’t mean you have to claim the deduction in that tax year. It might make sense to wait until you are in a higher tax bracket to claim the deduction.

When should you contribute to an RRSP?

When your employer offers a matching program: Some companies offer to match their employees’ RRSP contributions, often adding between 25 cents and $1.50 for every dollar put into the plan. Sadly, many Canadians fail to take advantage of this “free” gift from their employers: giving up a guaranteed 25-to-150 per cent return on their contributions.

When your income is higher now than it’s expected to be in retirement: RRSPs are meant to work as a tax-deferral strategy, meaning you get a tax-deduction on your contributions today and your investments grow tax-free until it’s time to withdraw the funds in retirement, a time when you’ll hopefully be taxed at a lower rate. So contributing to your RRSP makes more sense during your high-income working years rather than when you’re just starting out in an entry-level position.

Related: A sensible RRSP vs. TFSA comparison

A good rule of thumb: Consider what is going to benefit you the most from a tax perspective.

When you want to take advantage of the Home Buyers’ Plan: First-time homebuyers can withdraw up to $25,000 from their RRSP tax free to put towards a down payment on a home. Would-be buyers can also team up with their spouse or partner to each withdraw $25,000 when they purchase a home together. The withdrawals must be paid back over a period of 15 years; if not, the amount is added to your taxable income for the year.

You can claim a tax deduction for the amount you contribute to your RRSP each year, which reduces your taxable income. However, just because you made an RRSP contribution doesn’t mean you have to claim the deduction in that tax year. It might make sense to wait until you are in a higher tax bracket to claim the deduction.

When should you contribute to an RRSP?

When your employer offers a matching program: Some companies offer to match their employees’ RRSP contributions, often adding between 25 cents and $1.50 for every dollar put into the plan. Sadly, many Canadians fail to take advantage of this “free” gift from their employers, giving up a guaranteed 25-to-150 per cent return on their contributions.

When your income is higher now than it’s expected to be in retirement: RRSPs are meant to work as a tax-deferral strategy, meaning you get a tax-deduction on your contributions today and your investments grow tax-free until it’s time to withdraw the funds in retirement, a time when you’ll hopefully be taxed at a lower rate. So contributing to your RRSP makes more sense during your high-income working years rather than when you’re just starting out in an entry-level position. Continue Reading…