Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Closed-end funds vs. actively managed ETFs

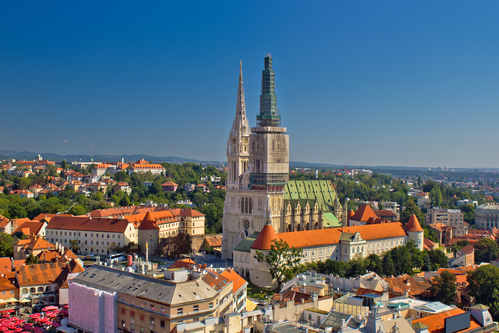
Zagreb, capital of Croatia, HQ for closed-end fund manager OTP Bank.

By Tony Porcheron

Special to the Financial Independence Hub

The current popular conversation in investments is about Exchange Traded Funds (ETF) versus normal mutual funds. The conversation is always about low fees vs high fees. The one version that never seems to come up is about Closed-end Funds, which are the granddaddy of all managed money.

The brief history of the modern managed money industry — which included mutual fund, hedge fund, and exchange-traded fund (ETF) industries — started formally with The Investment Company Act of 1940.

It clearly defines the responsibilities and requirements of investment companies as well as the requirements for publicly traded investment product offerings including open-end mutual funds, closed-end mutual funds and unit investment trusts. It primarily targets publicly traded retail investment products.

The next major development was the first index fund. This was a Wells Fargo fund formed in 1971. In 1974, the first mutual fund index shares were offered to retail investors.

Finally, exchange-traded funds came along in 1993 with the invention of TIPs (Toronto Index Participation Units) on the TSX.

The ETF is now growing tremendously globally with investors looking for lower fees during strong market cycles.

You can now get ETFs in a variety of investment focuses, types, industries, countries, security selection bias, etc.

The majority of ETFs are passive, where the manager simply follows the direction of the fund outline with no or extremely little input from the manager. These ETFs are usually with the smallest fees down to less than 0.1% on large US Indexes or Fixed Income Funds. As the funds are very large and need little management input, they can still be very profitable for the fund companies to manage.

Actively managed ETFs

There are also ETFs that have an active management approach. The manager then has some or a tremendous amount of involvement in stock selection and management of the fund. Active ETFs are usually in sectors where it is difficult to get an index return or average. These would be in situations such as emerging markets, small or microcap stocks or sub investor grade fixed income. Continue Reading…
3 ways to organize your new business

By Sia Hasan

Special to the Financial Independence Hub

If you have a new business, then it is crucial that you organize it in the right way. Otherwise, you could end up missing out on more productivity.

So ensure that you get the most done possible during the day and increase profits while reducing problems with workflow. Set up your business for massive success by organizing your business better in the following three ways:

SOP (Standard Operating Procedure)

The first thing you need to do when organizing your new business is determine what kind of roles everyone has. There should be specific and unique classifications as to who is responsible for what.

The best way to do this is with SOPs. These are documents that show everyone what is expected of each role. You can have certain protocols as to how to handle consumer service, sales, and more.

The idea of the SOP is that anyone can plug right into your business and know how to perform that role without much hassle. It’s a step by step list of instructions so there is no confusion regarding what needs to be accomplished to deem that particular part of the business a success. Of course, this kind of thing won’t happen overnight!

It is best to sit down and make time to create your own SOPs. You might even read a few books or resources on the subject. This way, you have some guidance. There are a lot of different ways to do it, but you need to choose one that works for you.

For instance, some people find that they prefer to record a video and upload the files online. Then, it acts as a training resource. Others like to write down the procedures and share them in the cloud. Do whatever seems right for your new business.

The right software

We live in a world where software is more important than ever. It is vital that you use the right software tools or you could risk falling behind. Oftentimes, the right software will allow you to get more done, save time, save money, and stay on the cutting edge so you can generate new ideas for even more innovation. Consider the various types of software out there.

For instance, accounting software for nonprofits helps you keep an eye on your transactions. This is crucial for a company. If you lose sight of what you need to be doing for your income or expenses, then it could come back to bite you later. This is true regardless of what kind of business you run.

Another type of software is a great CRM. Being able to communicate with your team and upload information about customers is invaluable. It shaves time off the communication cycle and gives everyone what they need in the cloud.

Sales and Marketing Automation

Long gone are the days where marketers had to sit down and write out a new email, post, or ad by hand. Today, you can use automation software to make these assets in a scalable way. After all, your team can’t be there every second of the day.

You want your team focused on the higher-level aspects, so let them do that. Enable them with marketing software that automates your funnels. It can test your ads right away. Continue Reading…

If you have no faith in the future, should you invest?

By Billy Kaderli

Special to the Financial Independence Hub

As many know, I am more than willing to offer financial advice in order to help others to become financially independent (aka “findependent.”) The sooner the better” that’s good for everyone, right?

I met a lady at a recent event that Akaisha and I attended, and in our visiting together I steered the conversation towards finances. Knowing that she lived in Hawaii and seeing that she was probably in her 40s, I falsely assumed she had some knowledge of money and how it works.

I was wrong.

After I shared with her that we retired at the age of 38, I asked what her financial plan for retirement was. She told me that she did not have much faith in the future, therefore she had no plan.

I asked her, “What if you are wrong?”

Her response was “I do not think I am wrong”

The Dollar is going to collapse

I have been hearing of the impending collapse of the Dollar for the last forty years.

First it was going to be replaced with the German Mark, then the Swiss Franc, then the Russian Ruble, Chinese Yuan, and now Bitcoin. Maybe someday they will be right, but so far, betting against the Dollar has been a costly investment.

I like to tell people that the Dollar is the cleanest shirt in the dirty laundry bin. Maybe you have some special inside trading information, but for me, I’ll stick with the U.S. currency.

Various apocalyptic scenarios

Maybe it’s part of being human, but it seems that society creates ominous future scenarios of various sorts to scare the living bejesus out of everyone. Continue Reading…

Stock portfolio management and planning for your Heirs

Our work with stock portfolio management clients sometimes gives us a window into problems that can arise with the death of parents and the distribution of their personal belongings and financial assets.

For instance, siblings may assume they were supposed to get particular items of jewelry or furniture. When they learn that somebody else asked first, they can harbour a grudge that can last for decades.

Planning for your heirs: Head off sibling conflict with frank discussions

The best way to spare your family this problem is to head it off while you’re still alive. Tell your kids that you want to be fair to everybody. Ask them to send you a note or an email to express interest in any particular article. But don’t put too much emphasis on who asked first, and don’t feel you need to rush into making a list of who gets what. Some of your children may be slow to think of what items matter most to them. Or they may feel shy about asking for them.

Everybody should understand that if one child gets valuable household items from the estate, they may wind up receiving less cash.

Unpaid loans from parents can also cause dissension. Sometimes adult children run into money problems and wind up having to sell their home, for instance. Later, they may want to borrow the down payment to buy another home. If you grant that request, don’t simply write a cheque.

Instead, have a lawyer register a mortgage on the new home for the full amount of the loan. Explain to your child that this protects the money from attachment by creditors if new money problems come along, and keeps it in the family. You should also be aware (no need to mention it to your child) that this step also keeps the money in the family in the event of divorce.

Dissension can also arise when a child stays in the family home long after his or her siblings have moved out. Living at home and taking care of a parent can hold a child back from career advancement, and may get in the way of the child’s social or romantic life. But siblings may see it as simply taking advantage of free room and board. If you think it’s appropriate, you may want to add a line or two in your will that acknowledges the personal contribution of the stay-at-home child.

It’s hard to avoid all tension that grows out of these all-too-human conflicts. But if you think about them and talk about them with your children, things will go much more smoothly than if you leave them for the kids to sort out on their own.

Planning for your heirs: Invest based on your heirs’ timelines

If you have substantially more money than you’ll need for the rest of your life, and you plan to leave the excess to your heirs as part of your retirement planning, it makes sense to invest at least part of your legacy on their behalf. That is, invest based on their time horizon, not yours. And above all, choose investments with our Successful Investor philosophy in mind.

For instance, if your heirs are in their 40s, your retirement planning should involve holding at least part of your portfolio in a selection of investments that would suit investors in their 40s, and that follow our Successful Investor approach. Of course, you’d still want to invest conservatively. But you’d want to take advantage of the many years that 40-somethings have till they reach retirement age. Continue Reading…

Which Robo Advisor differs from the other?

I recently penned the blog What and who are the Canadian Robo Advisors? That blog outlined how, true to the moniker, a robo advisor is an online financial advisor without the human.

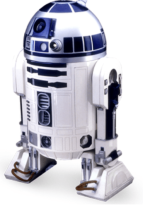
Well, let’s say that at times there is no human present. In actuality the robo advisors are all quite human and they all have a unique personality. Think Star Wars and the loveable tin cans known as R2-D2 and C-3PO. They are very different in voice and personality.

Above left is R2 …

And to the right is my robo mascot …

The answer to the question posed in the headline is that all of the robo advisors are different, at times very different from one another. That’s why it’s important to know and understand these differences so that you might be able to find the robo that’s right for you. Getting in the ‘right robo’ might make a difference of thousands to tens of thousands of dollars or more over an investment lifetime.

The ‘robots’ don’t think in a pure sense. In most cases, this is not artificial intelligence at work. The process involves investment concepts and approach(es) and then mountains of computer programming applied so that the robo platforms can follow the direction of the human financial gurus who set the course for each robo advisor.

The Chief Investment Officers and their teams can and do also make adjustments on the fly. Some may react to market conditions. That may seem ironic given that the robo advisors will mostly embrace and use mostly passive Exchange Traded Funds, but they will then get a little more active with regards to asset allocation and types of funds used based on changing market conditions. All said, that will be one of the factors that I track moving forward as we compare the performance of the Canadian robos.

Robos can be passive or active

Some robos are more passive, some robos are very active.

One of the robo advisors, responsive, is considered AI-based as the platform will automatically change the asset allocation (mix of stocks and bonds) based on many market and economic indicators. Continue Reading…