Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

WealthBar Q&A: How one Robo-advisor handles Retirement Income Planning

WealthBar CEO Tea Nicola

What follows is a sponsored Q&A session between Hub CFO Jonathan Chevreau and Tea Nicola, Co-Founder and CEO of WealthBar, a robo-adviser.

WealthBar provides financial planning with low-fee ETF portfolios and actively managed Private Investment Portfolios.

Through their financial advisers, easy-to-use online dashboard and financial tools, they are making investing more accessible for Canadians from coast to coast.


Jon Chevreau

Jon Chevreau: Welcome, Tea. While many so-called robo-advisers seem to focus on young people building wealth, what about the end game? How do you handle the shift for older investors from accumulation into spending your savings in retirement? 

Tea Nicola: Once a client who is accumulating assets decides that retirement is on the horizon and they let us know, we lead them into the retirement transition process. At this stage, they probably have a pretty good idea as to what they would like to spend after taxes. Their goal is to understand now if their savings and all their sources of income will be enough to fund their retirement years.

The conventional wisdom is to collect all the sources of income that the client will have and analyze it year by year. This step is essential to make sure that the goals are met. That includes the monthly cash flow for basic expenses, the annual travel budgets and one-off purchases as well as any legacies that they may desire.

We then make sure their savings can meet all those goals. If there are shortfalls, we adjust the savings rate to meet the goals by the time they want to stop working. Then, we iterate this every six months or so, both before and after the retirement date. We do this to make sure the transition is smooth and that routines are appropriately established.

Jon: You’re talking about managing expectations?

Tea: I would call it being realistic about expectations. For instance, we need to be careful about talking about a monthly income when it comes to drawing down on retirement savings.

What we typically see is an uneven drawdown, with extra spending in the first few years of retirement. The client is in a rush to do all the things they held off on while working. So, they go on world tour, get a golf membership, enjoy some fine dining, or generally treat themselves to something special. But after a few years, their spending habits ‘normalize.’ The initial exuberance declines and their expenses follow suit. You get cases like one client in her 90s, who is literally worth millions, who now has monthly expenses of about $2,000 a month.

With that in mind, our financial plans help clients to achieve the goals they want to achieve, without necessarily boxing them into a lifestyle category that doesn’t really apply for most of their retirement. This involves very realistic, practical planning that I would say goes into a bit more depth than other robo-advisers, or even many traditional wealth management firms.

Jon: Sometimes you’ll hear a kind of magic number bandied about for how much people need to retire. $1 million. $2 million … Is there a guideline that really makes sense?

Tea: It depends on the person, which is why financial planning needs to be tailored for each individual. Just like with salaries, we know that someone making $75,000 can feel like they’ve got as much money as they could possibly need. Continue Reading…

A snapshot of Canadian investors’ appetite for risk: Vanguard’s Canadian risk speedometers

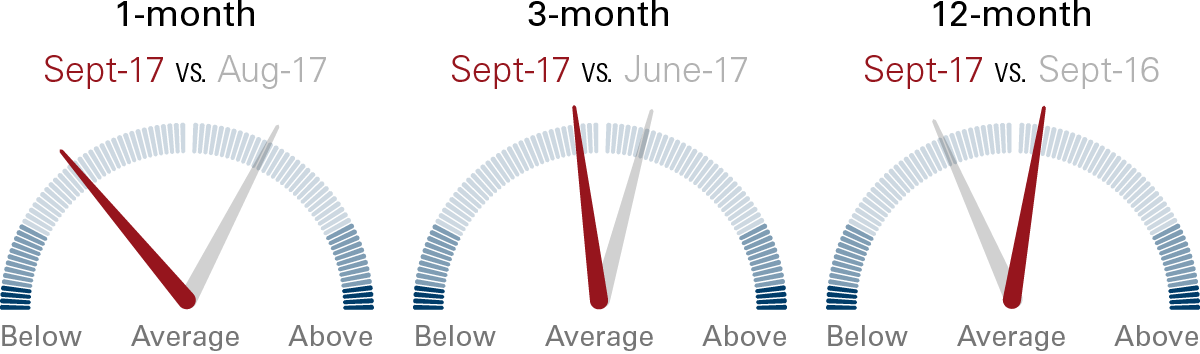
Figure 1: Vanguard’s Canadian risk speedometers, September 30, 2017

By Todd Schlanger, Senior Investment Strategist, Vanguard Canada

(Sponsor Content)

As part of Financial Literacy Month in Canada, we are proud to announce the launch of Vanguard’s Canadian risk speedometers.

These speedometers were originally designed by my colleagues in the United States to provide a factual representation of how investor risk appetite is trending today, relative to the past.

In order to generate the speedometers, we calculated net cash as a percentage of total assets under management, (in this case, within the universe of Canadian mutual funds and ETFs) into high-risk and low-risk asset categories. We then looked at the relative cash flows into high- versus low-risk asset classes, relative to history.

The end result is a risk measure that can be tracked through time and displayed in a risk speedometer index, as shown in Figure 1 over the 1-, 3-, and 12-month periods ending September 30, 2017. When risk appetite is above its historical average — such as over the 12-month period — the needle is to the right of centre, indicating higher risk appetite. When the needle is to the left of centre, risk appetite is below average. In addition to the current risk appetite readings, we also display the prior 1-, 3-, and 12-month readings for comparison.

Notes: Vanguard’s risk speedometers measure the difference between net cash flows into higher-risk asset classes and lower-risk asset classes, in this case within the universe of Canadian mutual funds and ETFs. The lighter-shaded areas represent values that are within one standard deviation of the mean, which means they occur roughly 68.2% of the time (34.1% higher and 34.1% lower). The middle shades represent readings between one and two standard deviations from the mean, occurring 27.2% of the time (13.6% higher and 13.6% lower). The dark edges represent values more than two standard deviations from the mean, occurring the remaining 4.6% of the time (2.3% higher and 2.3% lower). Speedometer values for previous periods may change from what was initially reported as the current value in prior periods because of changes made in Morningstar, Inc., data, and to the updating of the five-year average.

Along with the risk speedometers, we will be providing underlying asset category details (the top winners and losers in each category) in terms of net cash flows and changes in assets under management that resulted in the current risk appetite readings, as shown in Figure 2 (for the same periods, ending September 30, 2017).

Figure 2: Highest net inflows and outflows Continue Reading…

Mobile Personal Finance apps for Millennials seeking Financial Independence

By Reviews Bee

Special to the Financial Independence Hub

Smartphones and apps have enormously affected our daily life and financial management. And despite the fact the elder generation may still have some doubts about tracking incomes and expenses,  millennials are more likely to connect their financial independence with these apps.

The fact is many mobile apps nowadays enable quickly entering data on incomes and expenses, and to find information about completed operations, make changes, export the database or restore it from a backup, and track your expenses and income. They give you some perspective on major and minor decisions in life so it becomes much easier to make  right decisions on the flow of your personal money.

When choosing a program, it’s important to consider not only functionality and convenience of interface but also safety. To be sure the financial apps will not let you down, we have considered  functional peculiarities and user reviews of many similar mobile apps, on the basis of which we present some of the best ones:

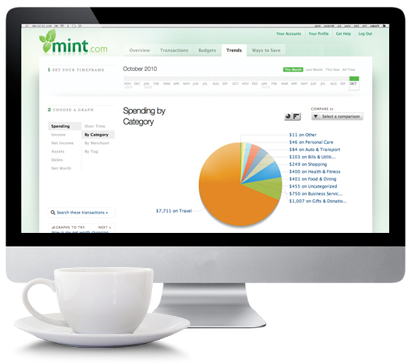
Mint

The Mint application helps to form a budget, track expenses and achieve financial goals. Costs and savings can be easily tracked in a special list, where different types of financial transactions are marked with different colors, as well as in the tables and charts that the application forms.

Users can also track movements on their bank accounts and credit-card balances in real time, monitor investments and even break their expenses into categories.

In addition, you can set up alerts if it’s time to pay bills, or if users have exceeded their budgets. Another convenient feature: a weekly consolidated report of the movement of your funds is available.

Wally

Continue Reading…

Building Wealth: Human Capital vs. Financial Capital

Back in 2003, when I began my career as a young sales manager in the hospitality industry, I earned an annual salary of $26,000. Little did I know at the time that my human capital – as in, the present value of my expected future income throughout my working lifetime – would be worth nearly $3,000,000!

I did some back-of-the-napkin calculations and was surprised to learn I’ve already earned a million dollars over my 15-year career. I find that incredible, given that I’ve never earned a six-figure salary and, in fact, my wages have been stagnant for the past four years.

Projecting my income forward using a modest 3 per cent annual growth rate reveals the potential to earn another $2 million by the time I turn 55.

Human Capital vs. Financial Capital

Put in different terms, however, and you can see that my human capital is shrinking each year. That’s because the value of my human capital peaked the day I started my career (back in 2003) with my entire lifetime of earnings ahead of me. Since then I’ve steadily used up my earning power and the value of my human capital has gradually declined.

The idea of eroding capital doesn’t sit well with me, but that’s where the second form of wealth building – your financial capital – comes into play. See, I’ve been a diligent saver for most of my career, which means converting my human capital (earnings) into financial capital (investments). Continue Reading…

Should buyers make a move in slower Autumn housing market?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

Depending on where you live in Canada, purchasing real estate in recent years hasn’t exactly been a cakewalk. Tight supply and rampant buyer demand (and alleged speculative investing) have pushed home prices to what some experts argue are unsustainable levels in the nation’s hottest markets.

However, following a slew of new policy changes introduced over the last year — such as Metro Vancouver’s foreign buyer tax and the Ontario Fair Housing Plan — those red-hot conditions have changed, with real estate boards from both markets reporting slower sales in the months following.

That’s made a dent in the national numbers, reveals the latest analysis from the Canadian Real Estate Association: with a 11 per cent drop in sales from last September. This is despite the typically busier autumn market, which is often the last chance for buyers to make a serious go of it before the snow — and holiday season — sets in. Seasonally adjusted activity was up slightly month over month at 2.1 per cent.

Too soon to call for market stability: CREA

While this could indicate market conditions are starting to settle after what has been a turbulent spring and summer market, it’s too soon to call it a trend, say CREA’s analysts.

“National sales appear to be stabilizing. While encouraging, it’s too early to tell if this is the beginning of a longer-term trend,” stated CREA President Andrew Peck.

Calmer sales activity hasn’t translated to greater affordability, though: home prices continued their ascent, with benchmark prices rising in 13 of MLS’s tracked markets. It’s the first time in seven years that all markets have seen simultaneous growth, with the national average price coming to $487,000.

However, prices are increasing at a slower pace than at the market’s peak, and that’s mainly due to the lost steam in the detached house segment since March. One- and two-storey single family homes appreciated by 7.9 and 7.2 per cent respectively, compared to the sizzling condo market, which saw 19.8 per cent appreciation, and townhouses at 13.5 per cent.

Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.