Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Create a Money Machine: The Effect of Compounding

effect_of_compounding1
Billy Kaderli, RetireEarlyLifestyle.com

By Billy Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

Our adventures around the world allow us to interact with many younger travelers in cafes and restaurants. Travelers are a great source of information about where they have been, places to stay and where to avoid. Things to do and the best way to get to a destination are often the topics of conversation.

Many times we are asked about how we can afford to travel for so long and then there’s the predictable wistful response: “I wish I could do what you’re doing.”

That’s when I tell them they can.

I explain in simple terms about investing and how they can create their own pension or annuity or as I like to call it a “personal money machine.” It is right about now when their eyes glaze over like they are speaking with their crazy uncle at a Thanksgiving Dinner.

I bring their attention back by saying they have something that I do not have; time. Usually I get a nod and a blank stare. I go on and ask if they know what “compounding” is. More often than not, they do not have a clue. These are college grads or they are taking a break from school to pursue their traveling bug. But to my surprise they do not understand the concept of compounding, which, in my opinion, is the easiest way to build wealth.

According to Investopedia, the definition of compounding is “the ability of an asset to generate earnings, which are then reinvested in order to generate their own earnings. In other words, compounding refers to generating earnings from previous earnings.”

Bingo!

Sweet simplicity.

The earlier you invest, the sooner Findependence
Continue Reading…

Understanding Your Retirement Benefits: Part 1 – CPP

MarieEngen
Marie Engen, Boomer & Echo

By Marie Engen, Boomer & Echo

Imagine celebrating at your retirement party without a clue as to how much you can expect to receive in pension income. It sounds incredible, but many people who will end their career in a few years are in just that situation.

When you work for an employer you receive your salary, but once retired your income can come from multiple sources. You need to know how much you will receive from these sources.

Since CPP is one of the cornerstones of retirement income, this is where I will begin.

A brief history of the CPP

The Canada Pension Plan (CPP) is a national public plan that covers people in all provinces except Quebec. It was created in 1966 by the government under Lester B. Pearson. Quebec wanted its pension monies to be under their control and so became the only province with its own program.

When CPP was created the contribution rate was 1.8% of pensionable earnings, to be shared by employers and employees; self-employed persons were on the hook for the full amount. The first deductions were so minuscule that they were unsustainable to fund the retirement costs of the baby boom generation that was just beginning their working years. Also, life expectancies were starting to increase substantially. Continue Reading…

Who gets the Porsche — you or your investment firm? … Fees Matter! Introducing FWB TV

The Financial Independence Hub is excited to unveil a new Internet video project on investing made possible by FWB TV,  a unit of Toronto based Financial Wealth Builders Securities.

Starting today and on a regular basis, the Hub’s sister site, Findependence.TV, will be housing video content provided by FWB TV Paul Philip CLU, CFP and his associates.  These high-quality videos generally run between two and four minutes and focus on investment strategies that are quite consistent with the content normally run on the Hub blogs.

You can find the first one by clicking on this headline:  Who gets the Porsche — you or your investment firm? … Fees Matter! Expect the next instalment in a week or two.

Q&A on the rationale for FWB TV

To introduce the series and explain the rationale, here is a Q&A between myself and FWB TV owner Paul Philip CLU, CFP:

Continue Reading…

Weekly Wrap: Horizons escalates ETF price war, Questrade expands active ETFs, CSA to review robo advisers

PRICE WAR red Rubber Stamp over a white background.

Three significant developments in the ETF and robo-adviser space late this week, the full recap of which can be found in my new Weekly Wrap that may run online Fridays in the Financial Post.  You can find the link for the first one here.

Horizons ETFs has rejigged fees on its popular Canadian equity fund, Horizons S&P/TSX 60 Index ETF [ticker HXT,] to just 0.03% or three basis points (plus taxes, down from the previous 0.05%. Previously the low-fee threshold was 0.05%, shared with three other providers.

Meanwhile, Questrade Wealth Management launched two actively managed ETFs, a global equity fund plus a fixed income ETF  subadvised by institutional money manager, Jarislowsy, Fraser Ltd. These expand the lineup of six Questrade Smart ETFs launched in March.

On Thursday, the Canadian Securities Administrators (CSA) issued CSA Staff Notice 31-342 directed at portfolio managers providing online advice, popularly known as robo advisers.   The CSA says it may conduct compliance reviews of online advisors within one or two years following launch, particularly as operations become more complex than the first generation that had basic ETFs or mutual funds as its underlying  investments, and “uncomplicated” asset allocation models.


Millennial is mortgage free at 31. Next goal: Findependence Day by 35

DSC02324
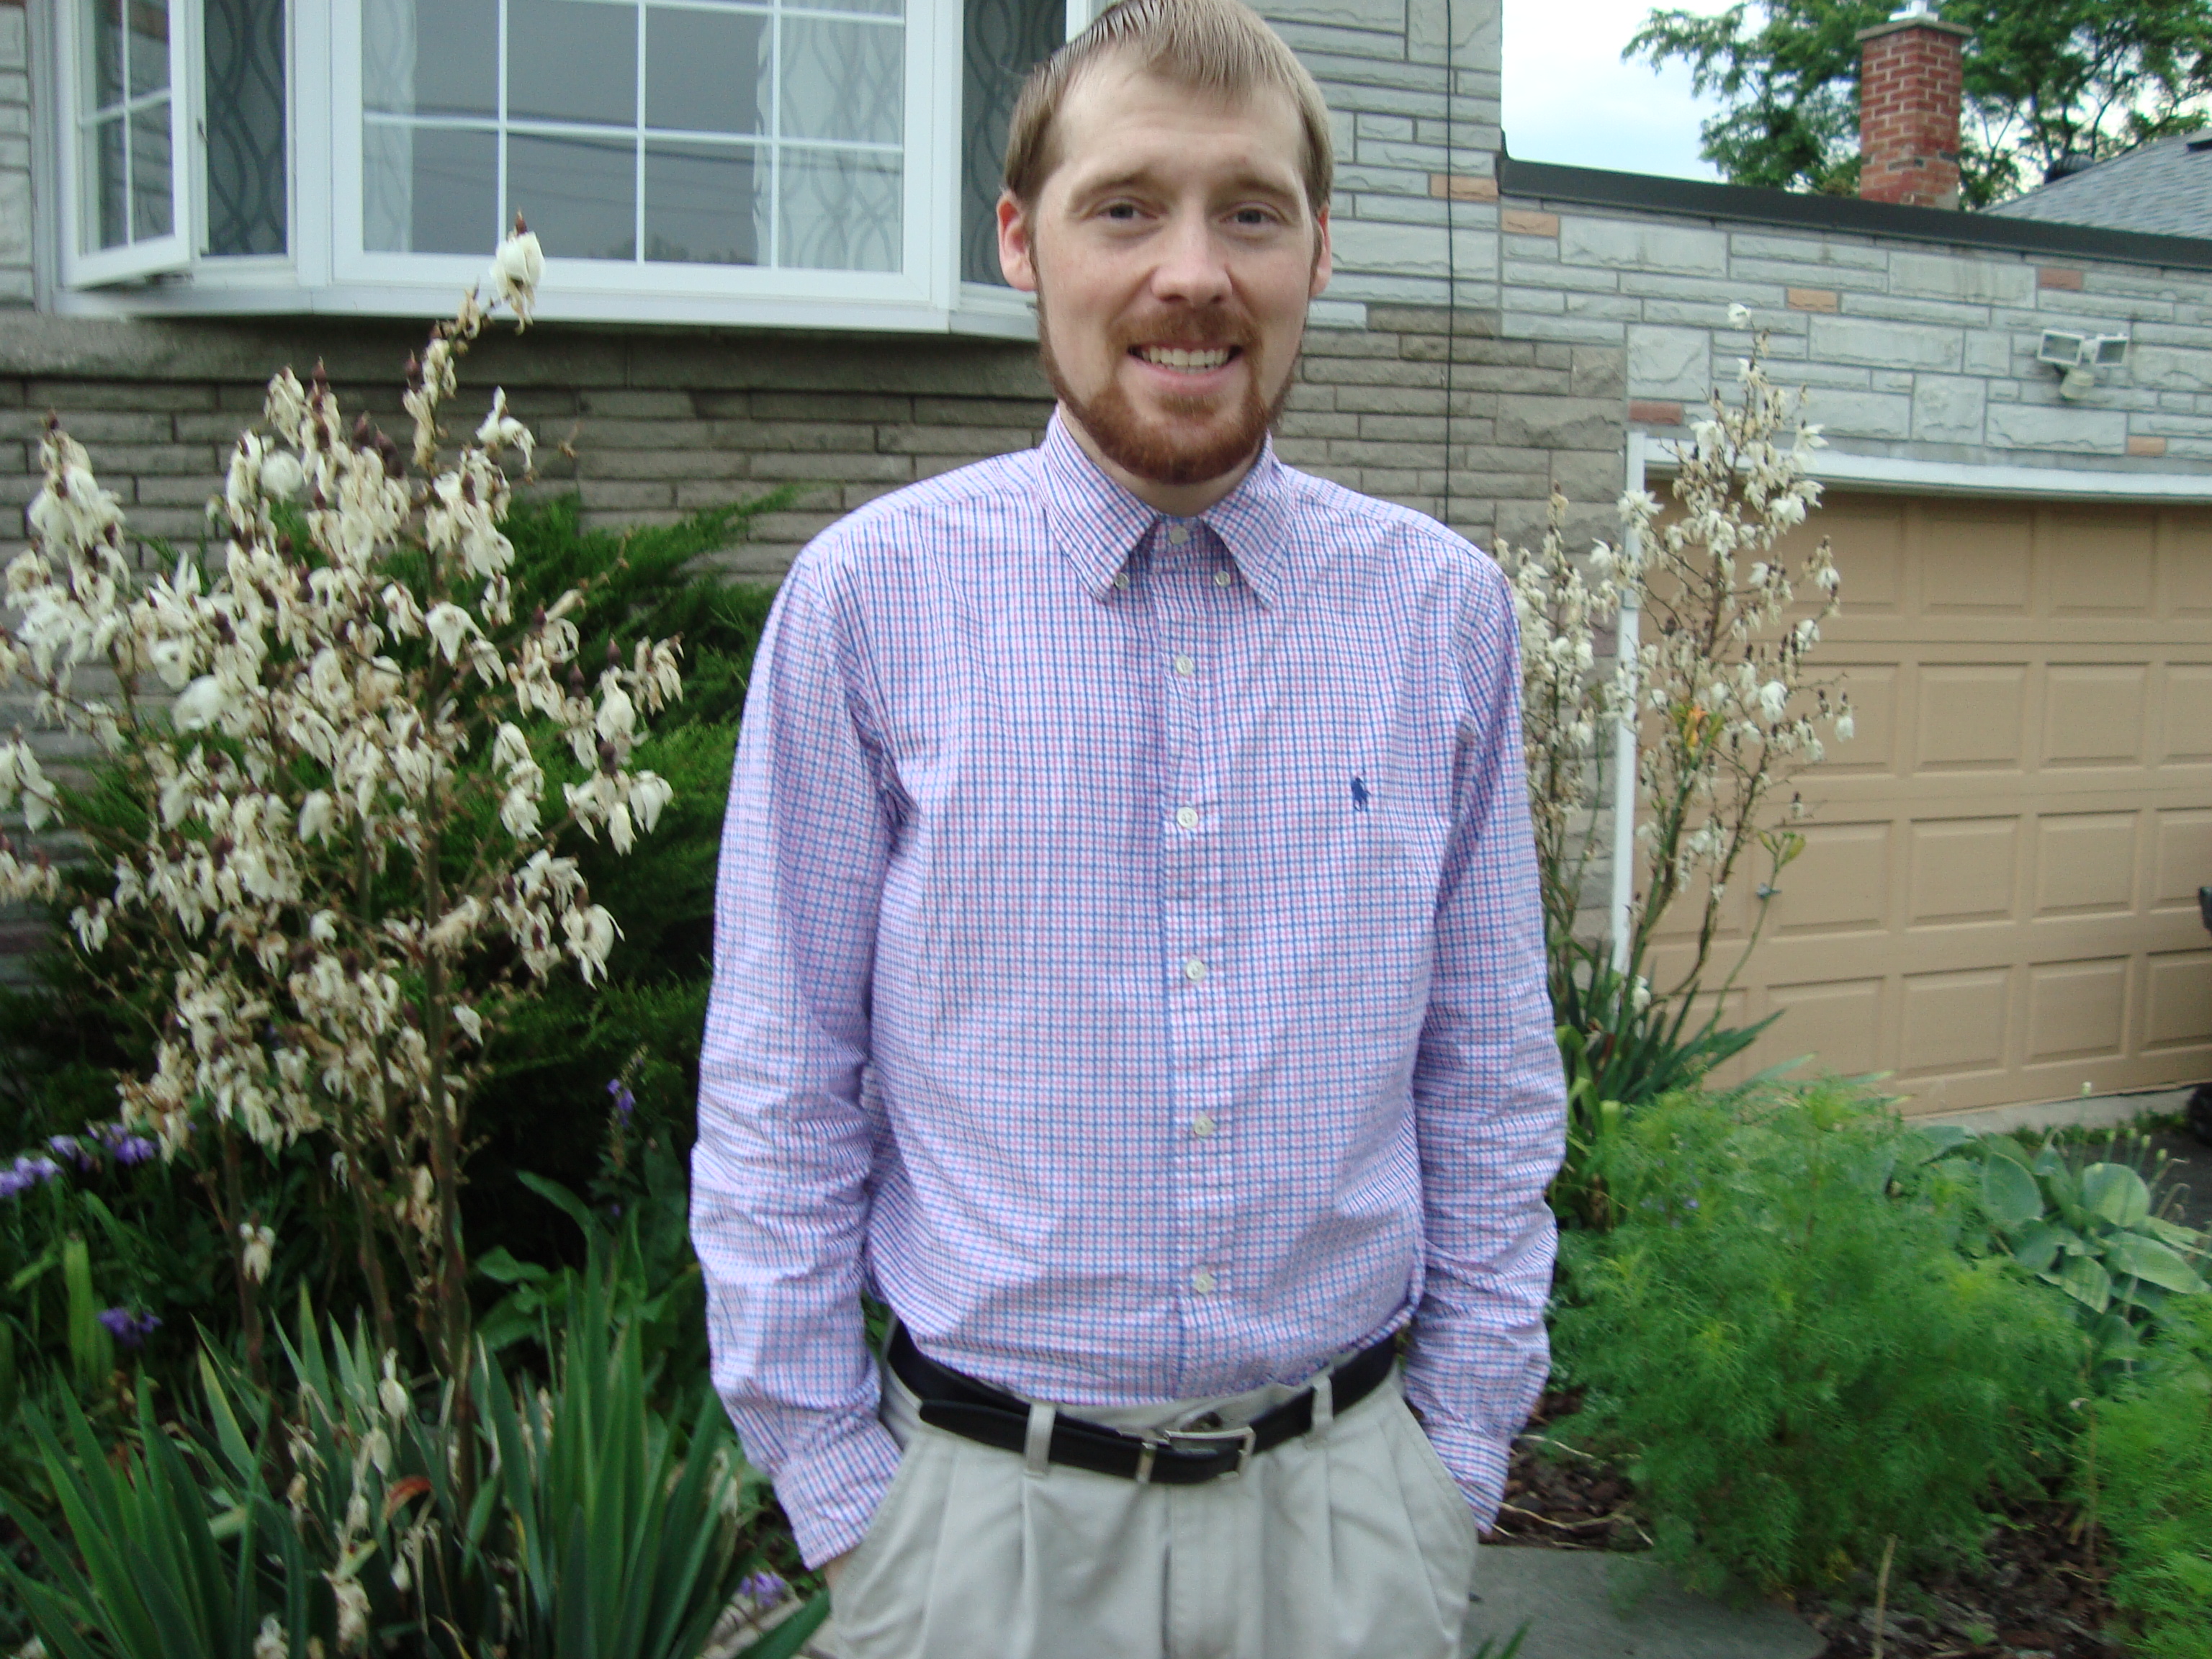
Sean Cooper in front of his paid-for home

My latest MoneySense blog features 30-year old millennial and financial writer Sean Cooper, who is having a mortgage-burning party tonight to celebrate his paying off his mortgage in just three years. See Mortgage free by 31.

In an early guest blog here at the Hub, Cooper credited my financial novel, Findependence Day, with inspiring him to seek early financial independence himself. See also a second millennial’s story at Two millennials well on the way to achieving early Financial Independence.

The book argues in particular that “the foundation of financial independence is a paid-for house.”

Cooper apparently took this message to heart because. He doesn’t even turn 31 for a few more months and has set his next goal to achieve a net worth of $1 million within four years. Well done, Sean, may you serve as an inspiration to your generation!

Click on the above link at MoneySense to find the full Q&A I conducted with Sean, or see this mirror blog at sister site FindependenceDay.com.