Tag Archives: Financial Independence

Time: your most valuable asset

Everyone is born with an expiry date; the problem is that date is kept hidden from us, and when it happens, it just happens. But everyone also has a best-before date, a date up to which you are still physically able to do most things you enjoy: studies have shown this period can be influenced to a large extent by a person’s lifestyle.

When I think about the word “retirement,” and my definition for retirement is admittedly very narrow, I tend to think about that period that lies after a person’s best-before date up to their expiry date. This is the period where a person is no longer capable of being independent, and are dependent on others for care and support for their remaining years.

My main focus in my own Victory Lap is to make good investments of my time to create an optimal lifestyle with the goal of pushing back as far as possible my own best before date.

Each day has only 24 Hours – Use them well!

It’s important to understand how limited our hours are on this planet and to get a good feel for the problem watch the You Tube video “You have 28,835 days. Here’s how you will spend them.”

The video was a real eye opener for me. After watching it, I began to really appreciate the value of my remaining time. I promised myself  I would take the appropriate corrective actions, but habit change is never easy and it is a work in progress for me. Please be assured that I will talk more on this important subject in future posts.

It takes ten years to become an overnight success

One day at a yard sale, I bought some old poker chips with the intent of using them to help track the time invested in pursuit of some of my goals. I came up with this idea after reading the book “Outliers” by Malcolm Gladwell and his chapter on the 10,000 hour rule, which is the hours of practice required to achieve mastery in anything.

A key component of my Victory Lap is the job I created for myself (my reason for getting out of bed in the morning) and creating the VLR community. To succeed, I need to improve my writing, blogging and public speaking skills. I also need to get healthy again so I will have the energy to get it all done.  I have committed to investing 10,000 hours on this project, which equates to 1,000 hours per year over a 10-year period.

Those poker chips I bought? I counted out 520 chips, which represent the number of weeks covering a 10-year period and keep them in a glass jar in my home office. Each Sunday night after reviewing what I accomplished with my time that week I throw that week’s chip away and replace it with another one from the jar.

Watching that jar of chips shrink over time makes me focus on the important things in my life. It creates awareness especially as I carry the current week’s chip around in my pocket. When I hold it, it reminds me to focus on doing what I need to do in order to make things happen.  Sometimes I might write something on the chip to serve as a theme for the week. It helps me to focus on what’s important and to forget about the rest.

The most important decision that you make each day is how you are going to invest your time. If you can’t see a reasonable return from your time investment don’t make the investment period.
Drak 2014Mike Drak is an author, blogger and speaker based in Toronto. He can be reached at michael.drak@yahoo.ca. Victory Lap Retirement, co-authored with Hub CFO Jonathan Chevreau, is now available for is now available for orders online. It’s also available now as a Kindle e-book, and on Kobo. The paperback edition will be available in bookstores in the second week of October. This blog is reprinted from Mike’s site with permission.  

Millennials may need to save 22% of income just to retire by 70

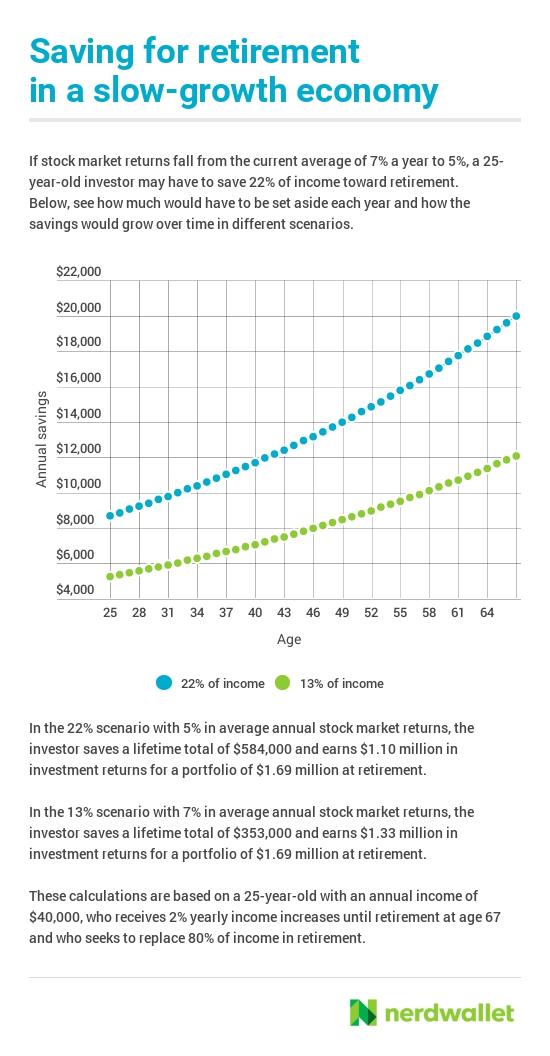
chart-1As my Financial Post blog today recaps, a new study being released today by the San Francisco-based personal finance site NerdWallet warns that just to retire by age 70, today’s millennials would have to save a whopping 22% of yearly income. Click on the highlighted text for the FP piece: Millennials may have less time on their side, U.S. retirement study shows.

The adjacent chart shows the math and how much millennials would need to save every year, depending on whether the stock market generates its historic 7% annual rate or the more pessimistic projections of 5%.

“Era of supernormal returns is over”

Continue Reading…

Debt-free in 30 podcast on Victory Lap Retirement

jonmikecropped
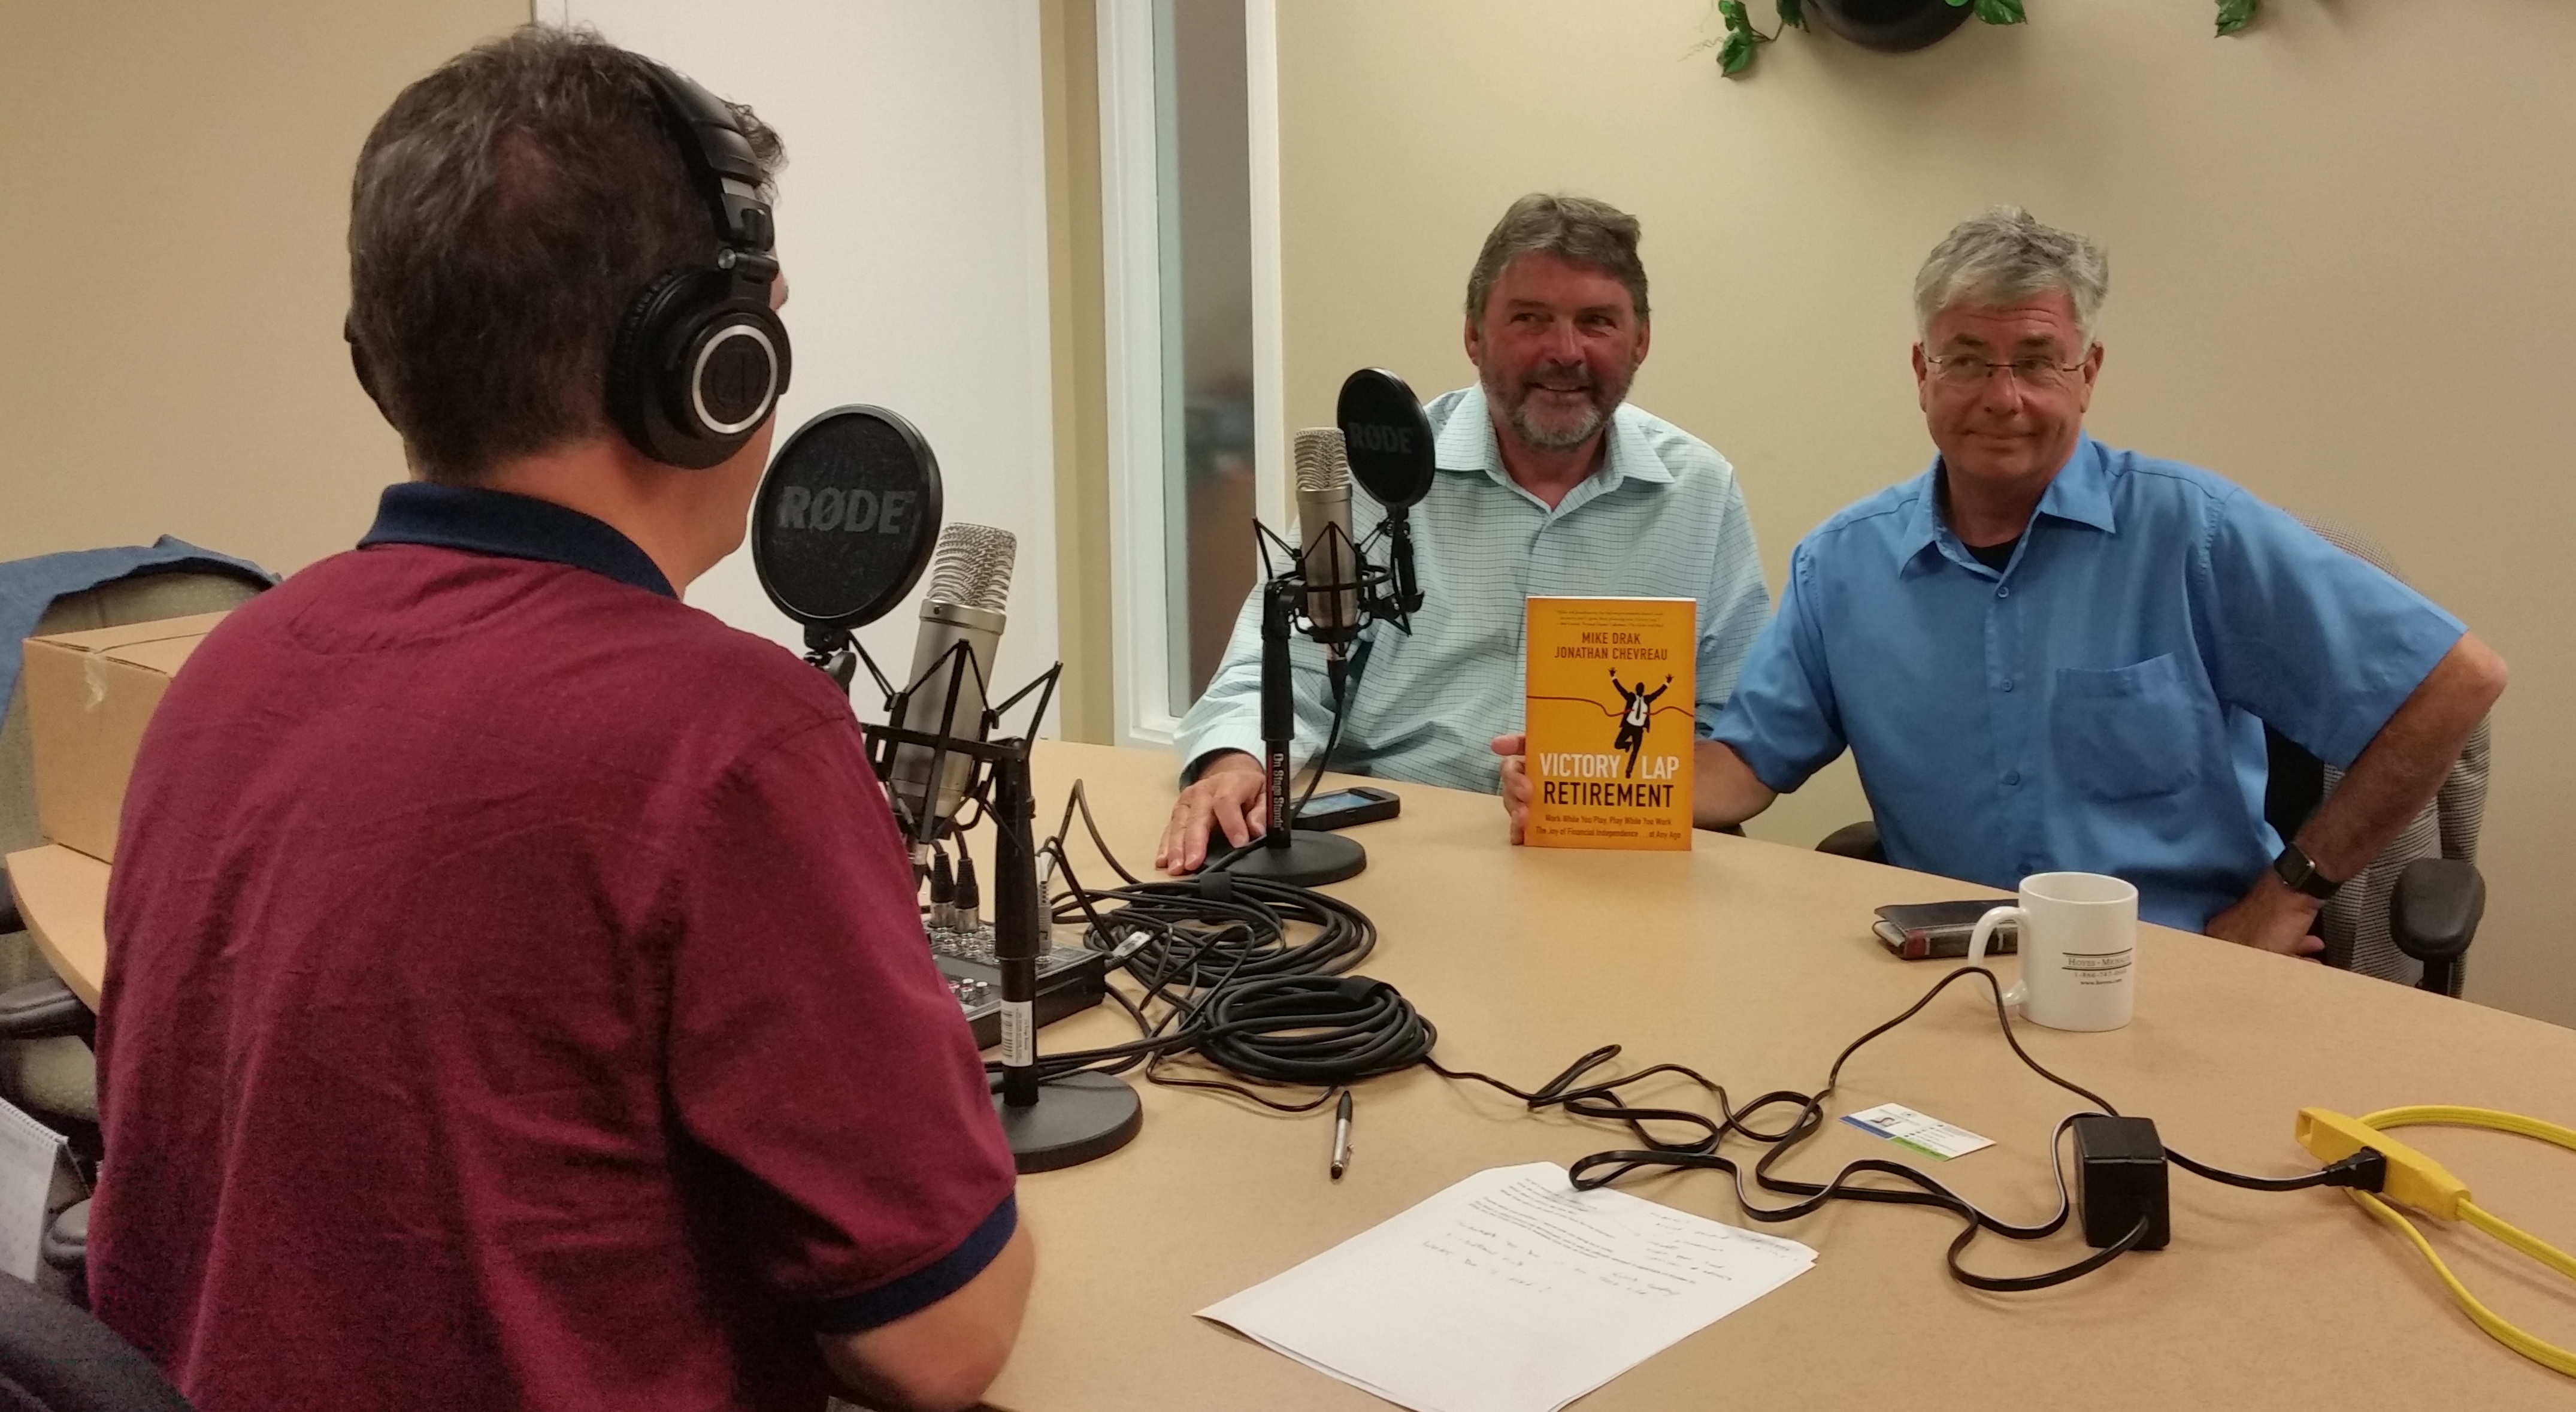
Doug Hoyes (in red), Mike Drak (C), Jon Chevreau (R)

As of Saturday morning, you can find a half-hour podcast conducted by Debt-free in 30’s Doug Hoyes about the new book, Victory Lap Retirement.

My co-author, Mike Drak, and I were in Waterloo last week to tape the session and sign a few books.

Click on the highlighted text here to listen to Victory Lap Retirement. EXCLUSIVE First Podcast Interview.

Or you can scroll down below for a lightly edited transcript of the proceedings.

But first, here’s an overview written by Doug Hoyes, co-founder of insolvency trustees Hoyes Michalos:

DougHoyesCanadaTrustee
Doug Hoyes

Doug Hoyes:

Today’s podcast is the first ever podcast interview with Jonathan Chevreau and Mike Drak together, talking about their new book Victory Lap Retirement.  This is so exclusive an interview that the book won’t even be officially released until October 10, 2016 but it is available for pre-order at amazon.ca, and the Kindle version is available now.

Jonathan was a guest back on Show #5 where we discussed his previous book, Findependence Day.

Mike Drak created the concept of a Victory Lap as an alternative to retirement, and teamed up with Jonathan to write their new book.

So what is a Victory Lap?

You will have to read the book for a full description, but as Jonathan and Mike and I discussed the concept of retirement has changed significantly.  Our grandparents and parents had a good chance of working at the same company until aged 65, and then retiring with a full pension before dying at age 70.

Today almost no-one works at the same company for their entire working life, and most employers no longer offer full pensions, so the old fashioned view of retirement at age 65 with a full pension is no longer reality for most workers.

Instead, we are working longer, and living longer.

The essence of Victory Lap Retirement is to leave corporate employment, which usually entails working for someone else, and enter a new and different phase of your life.

Mike and Jonathan wrote Victory Lap Retirement to show readers how to transition from a high stress work environment to a low stress sustainable lifestyle to enjoy a happier, healthier life.  For many, that may involve turning a hobby or passion into income during your “retirement” years, or working part time to “stay involved.”

Debt and Retirement

Debt is a prominent subject in Victory Lap Retirement, including this quote:

…make breaking free from the chains of debt your first priority.  Not only will debt limit your financial freedom severely, it will suck the life right out of you.

As we discussed, debt and retirement don’t mix.  When you retire your income decreases, so it’s likely you won’t be able to afford payments on a mortgage or other debt in retirement.  Get out of debt long before retirement.

Unfortunately that’s not always possible, which is why seniors are the fastest growing age group of people filing bankruptcy and consumer proposals. Older debtors, aged 50 and older, now account for 30% of all insolvency filings, up from 27% two years ago, and that number keeps growing.

Senior debtors, people aged 60 and over, have the highest amount of unsecured debt of any age group when they go bankrupt, almost $70,000.  A growing percentage of them even resort to payday loans to stay afloat.

If you’ve got debt, retirement is very difficult.  If you have trouble making your debt payments while you are working, it may be impossible to keep up when you retire and your income drops, which is why we all agree that eliminating debt is essential long before retirement.

In addition to eliminating debt, Mike and Jonathan suggest you ask yourself “what do I like to do?” and start planning your Victory Lap now. 

For more, listen to the podcast or read the transcript.

Transcript: 

Continue Reading…

How much will my Defined Benefit pension pay in Retirement?

depositphotos_5971382_s-2015I contribute to a defined benefit pension plan at work. How much will I get from the pension plan in retirement? That depends on when I retire or leave the plan. Hang on, we’re about to get math-y.

Normal retirement age is 65 and I joined the pension plan in 2009 at age 30. Retiring in 2044 (the year I turn 65) would give me 35 years of pensionable service.

The pension plan has a retirement calculator on its website. Curious about the amount of retirement income I’d receive at various ages, I took a look. The calculator just needed a couple of inputs: current salary, plus an assumption for future annual salary increases (I used 2 per cent).

Retiring at age 65 would max-out my pensionable service and give me an annual retirement income of $46,000 in today’s dollars. But what happens if I don’t make it until 65? Retiring five years earlier at age 60 changes the equation substantially.


Retiring at 60

Continue Reading…

Top 5 Credit Card myths Busted

5-myths-blog-img

by Kevin Chu, RateHub.ca

Special to the Financial Independence Hub

Credit cards, much like any financial product, seem to create anxiety for many. With so many rumours surrounding credit cards, we decided to turn to top influencers in the community for help on busting these myths and sharing the facts.

Here are your top 5 credit card myths busted once and for all:

Myth #1: Having a credit card means you are financially irresponsible

Credit cards are a great way for you to start building credit and earn rewards from everyday purchases. If you’re spending wisely and are paying off your balance each month, credit card debt won’t be an issue.

Myth #2: Getting a credit card will hurt your credit score

The exact opposite is actually true here. The best way to establish credit is to start by getting a credit card. By paying off your debt in full each month, there’s nowhere but up for your credit score. Be wary of credit utilization though. A high utilization ratio will affect your credit score negatively.

Continue Reading…