It’s not easy being a Canadian investor, is it? Given recent elections, we’re unlikely to see a pro-business surge anytime soon … to say the least. (It’s not investable info, but did you notice I happened to accurately forecast this?)
Plus, we’ve had to watch other countries’ stock markets beat the pants off our own during the past decade. U.S. glamour or FAANG stocks (Facebook, Amazon, Apple, Netflix and Google) have been living especially fat and larger than life lately.
It’s no wonder I’ve been fielding questions about how to best allocate among the global equity markets these days. How much is too much in Canada? Should we just dump everything into the U.S. market? Is diversification dead?
My short answers are: It depends. No. And, I wouldn’t bet on it. This is an admittedly incomplete response, so let’s consider four points and counterpoints to fill in the blanks.
1.) Canada’s market cap is tiny, and concentrated
While we’re rich in land mass, Canada represents just 3% of the world’s stock market capitalization. Plus, that 3% isn’t very well-diversified, with relatively heavy exposures to banking and natural resources.
2.) Canadians and everyone else have a home bias
Home bias means we prefer familiar objects close to home. If (like me) you’re rooting for your kid’s hockey team, cheer on. But in the markets, this tempts most investors – and many financial professionals – to pile too heavily into their own countries’ stocks.
For example, despite recent underperformance, the typical Canadian still allocates 60% of their investments to Canadian stocks. The Behavioral Investor author Daniel Crosby reports that U.S. investors typically allocate 90% of their holdings to the U.S. market; U.K. investors allocate about 80% of their holdings to the U.K. No matter where you roam, home bias is right at home.
3.) Markets are unpredictable
Before you ship all your investments across the border or overseas, remember: Markets can turn on you, abruptly and without warning. While it might seem like a distant memory, it should be noted, from 1999–2009, Canadian stocks (S&P/TSX composite) returned 7.7% per year, whereas U.S. stocks (S&P 500 in Cdn$) seemed cursed in the new millennium, delivering –2.5% per year … yes that is a negative return for 10 years! Continue Reading…
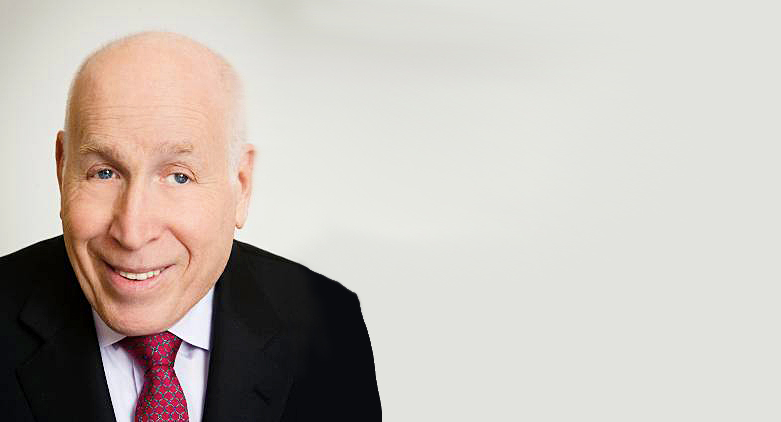
Last month, I had the privilege of meeting legendary investor Larry Hite.
Larry was born into a lower middle-class family, had a major learning disability, did poorly in school, and was completely blind in one eye and half blind in the other. In his own words, “I was not handsome. I was not athletic. Whatever I did, I sucked at it badly.”
In 1981, after dabbling as a music promoter, actor, and screenwriter, Hite founded Mint Investments. Mint was a true pioneer, eschewing human judgment and instead basing its investment decisions on a purely systematic, rules-based approach rooted in statistical analysis.
By 1988, Mint registered average annual compounded returns of over 30%. In its best year, Mint registered a gain of 60% (1987, the year of the stock market crash), and in its worst year, it produced a gain of 13%. By 1990, Mint was the biggest hedge fund in the world, with a record-breaking $1 billion under management.
When it awarded Larry the Lifetime Achievement Award, Hedge Fund Magazine wrote:
“Larry Hite has dedicated the last 30 years of his life to the pursuit of robust statistical programs and systems capable of generating consistent, attractive risk/reward relationships across a broad spectrum of markets and environments and has inspired a generation of commodity trading advisers and systematic hedge fund managers.”
Although Hite began his investing career in the early 1980s, his philosophy of markets and approach to investing are remarkably similar to our own, which are summarized below.
Failure: A Foundation for Success
Hite maintains that his early failures were instrumental in his eventual success. He believes that accepting that failure is sometimes inevitable led him to develop an investment strategy that would limit losses.
In his book, The Rule, he wrote:
“I believe the success I’ve had arrived because I always expected to fail big. Solution? I engineered my actions so that a failure could not kill me. I won because I expected to lose. Failure became my advantage. Once you understand your potential for failure – that is, there are times you can’t win – you know when to fold your cards and move on to the next. You will do this more quickly than others who stay in the game too long, hanging on and hoping that their losing bet will turn around.”
It’s not all about Being Right
Many investors focus on being right as much as possible – on maximizing their ratio of winning vs. losing investments. On its face, this seems like a good idea – all else being equal, if you win more than 50% of the time, then over time you will make money.
Hite takes a different approach. Whereas he has no issue with trying to be right as often as possible, he is far more focused on maximizing the average magnitude of his winning positions relative to that of his unsuccessful ones, asserting that:
“Becoming wealthy and successful isn’t simply about being right all the time. It’s about how much you win when you are right as well as how much you lose when you are wrong…. The Mint trading system did not prioritize being right all the time. We prioritized not losing a lot when we lost but winning big when we won. But as a result, we were frequently wrong. We understood and expected this and taught our clients the wisdom too.”
Risk: A No Fooling Around game
Hite places a greater emphasis on risk management than on generating profits, claiming that mistakes regarding risk can lead to catastrophic results. He asserts that, “Risk is a no fooling around game; it does not allow for mistakes. If you do not manage the risk, eventually it will carry you out.”
His approach to investing clearly reflects his respect for risk. Specifically, Hite divulges that “We approach markets backwards. The first thing we ask is not what we can make, but how much we can lose. We play a defensive game.”
One of my favorite anecdotes regarding risk is Hite’s reflection on a conversation he had with one of the world’s largest coffee traders, who asked, “Larry, how can you know more about coffee than me? I am the largest trader in the world. I know where the boats are; I know the ministers.” Larry responded, “You are right. I don’t know anything about coffee. In fact, I don’t even drink it.” The coffee mogul then inquired, “How do you trade it then?”, to which Larry answered, “I just look at the risk.”
Five years later, Larry heard that this magnate lost $100 million in the coffee market. Upon reflection, Hite states, “You know something? He does know more about coffee than I do. But the point is, he didn’t look at the risk.”
Larry Hite
Market Predictions, Storytelling, & Good Copywriters
Larry is skeptical that anyone can predict markets. He in no way bases his approach to investing on making predictions, which he believes is an exercise in futility. In his own words:
“I respect the sheer intelligence and devotion of economists who have attempted to develop a unifying theory of market dynamics. But I don’t believe any such theory will hold up to scrutiny in the real world of money on the line. When you start believing you have remarkable market predicting powers, you get into trouble every single time.”
Hite is also critical of Wall Street research reports, claiming that they possess little investment value and are designed to exploit people’s natural tendencies to listen to entertaining narratives, stating:
“Stories began at the dawn of human society to entertain and instruct the next generation. We are wired to learn from well told stories. And unfortunately, Wall Street preys off our basic human weakness to want stories.”
In his typically blunt and straightforward manner, he adds, “When you start following slick reports filled with predictions, you’re just finding out who has good copywriters.”
A Computer can’t get up on the wrong side of the bed in the morning
Larry was a pioneer in his exclusive reliance on a data-driven, systematic approach, using statistical analysis of historical data to develop trading rules, which are the basis of his investment decisions. When he launched Mint Investments in 1981, his goal was “to create a scientific trading system that would remove human emotion from buying and selling decisions and rely instead on a purely statistical approach built on pre-set rules.” Continue Reading…
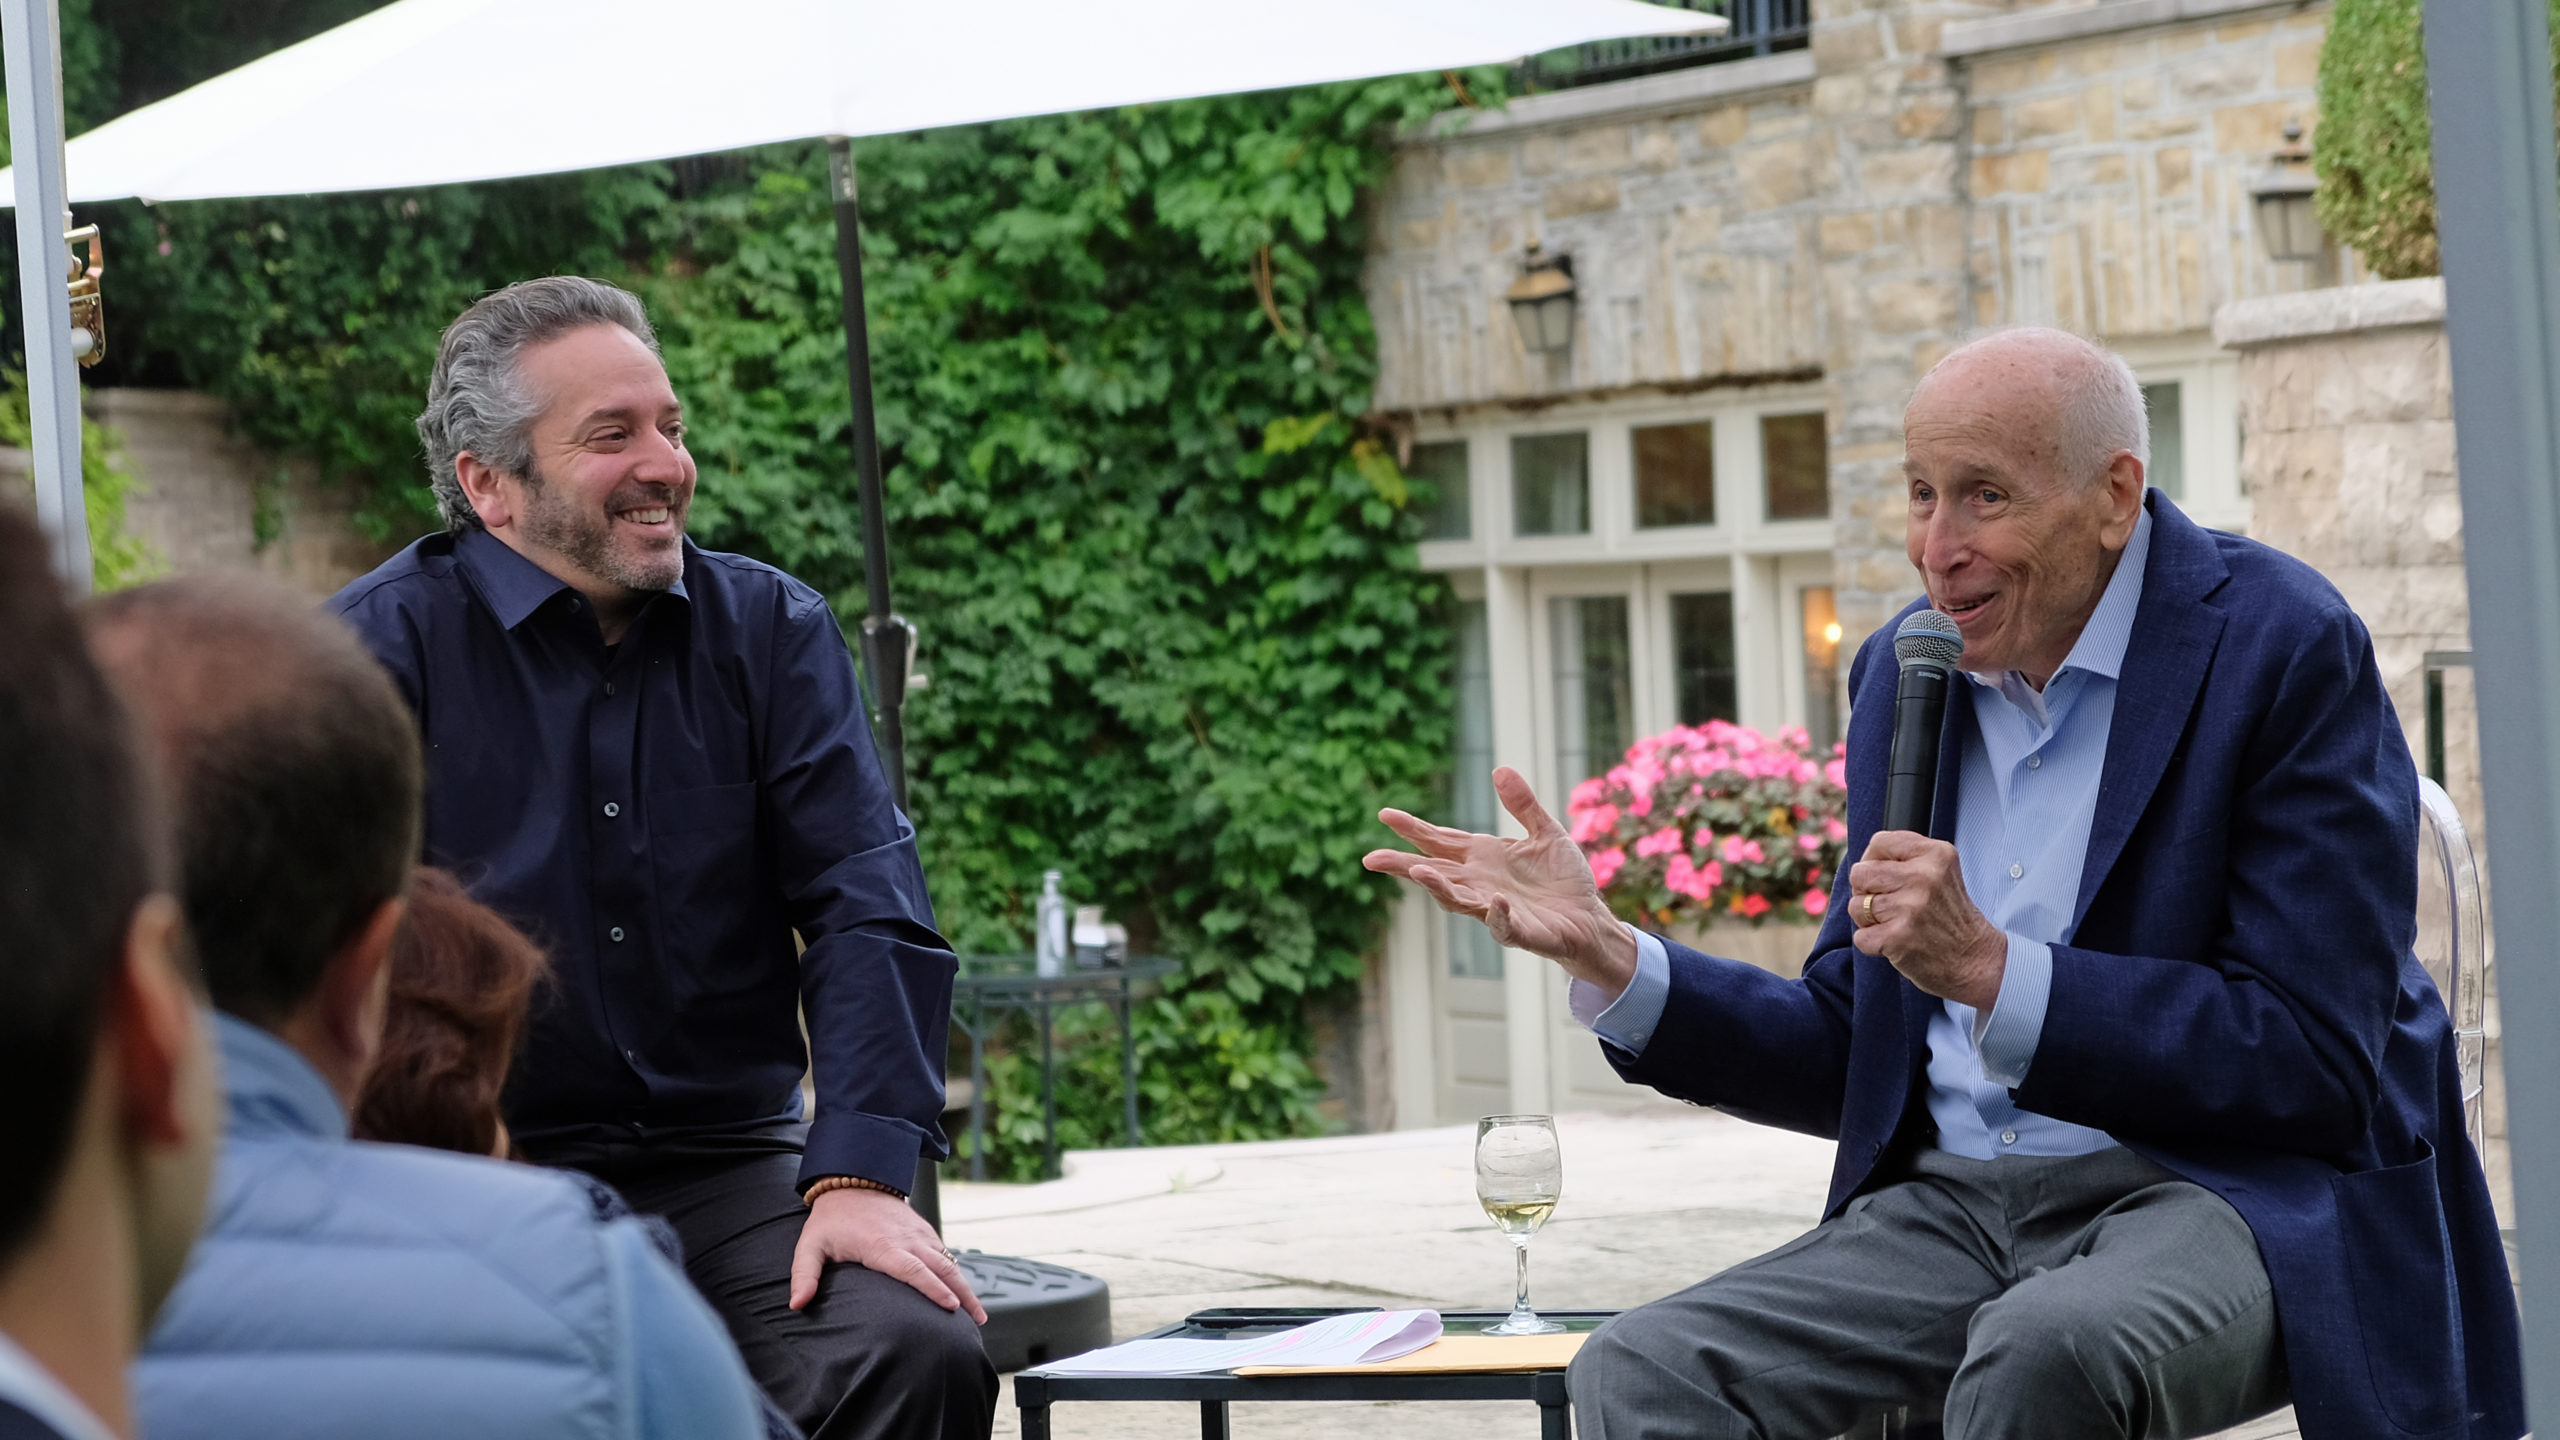
Kornel Szrejber’s Canadian Financial Summit 2021 is a virtual event that will go live next Wednesday, Sept. 22. There are dozens of financial speakers featured, including many well-known financial bloggers, including Yours Truly.
My 45-minute Zoom interview with Kornel was pretty wide-ranging but focused on Retirement Income, as opposed to Wealth Accumulation. The working title for the discussion was Semi-Retirement: the Halfway House between Employment and Full Retirement. Or as Doug Dahmer and other retirement gurus have dubbed it, the “Work Optional” phase of our working careers.
Certainly our chat was informative and entertaining: I certainly revealed a lot of how our family’s own personal finances are handled and I learned that Kornel — like Michael James and Robb Engen — has long been a “pure” indexer as opposed to a hybrid investor who mixes core ETFs with a bit of dividend investing and speculation in individual stocks.
We will reprise the full interview and supply a link once the event goes alive. In the meantime, check out Robb Engen’s preview of the event that ran on the Hub earlier today.
The Canadian Financial Summit is back once again this fall with a terrific line-up of 35+ personal finance experts, including yours truly, to tackle the burning financial questions facing us today.
You’ll hear from PWL Capital’s Ben Felix, Millionaire Teacher Andrew Hallam, The Globe and Mail’s Rob Carrick, consumer advocate Ellen Roseman, along with long-time personal finance bloggers Barry Choi, Tom Drake, Mark Seed, Bob Lai, , Stephen Weyman and Jonathan Chevreau.
How to take a tax holiday by working outside of Canada
Want an Unlimited TFSA? Try moving to these countries with territorial taxation
Are dividend stocks in a bubble?
The risks of investing in cryptocurrency
Should I have Bitcoin in my Portfolio?
Maximize the New Aeroplan and Post-Covid travel plans
Don’t let FOMO ruin your investment returns
Maximize Work From Home tax tips in a Post-Covid World
Will the Canadian Housing bubble finally pop?
How to setup a corporation, invest within it, and then pay yourself
The BEST ETFs in Canada
Why self-made dividends are better than ordinary dividends in every way!
I was happy to chat with co-host Kyle Prevost earlier this summer when we filmed our session about how not to let FOMO (fear of missing out) ruin your investment returns. It’s a topic at the forefront over the past 18 months as cryptocurrencies and meme stocks soared by triple and quadruple digits. Continue Reading…
I started investing in individual stocks shortly after the Great Financial Crisis ended in 2009. I picked an investing strategy that closely resembled the Dogs of the TSX, buying the 10 highest yielding Canadian dividend stocks. As you can imagine, the share prices of these companies got hammered during the stock market crash so I was able to scoop up shares in banks, telecos, pipelines, and REITs on the cheap.
Stocks came roaring back right away and my portfolio gained 35% by the end of 2009. Investing is easy, right?
It took me a while to figure out that my portfolio returns had less to do with my stock picking prowess and more to do with market conditions, luck, and the timing of new contributions. The rising tide lifted all ships, including my handful of Canadian dividend stocks.
I started comparing my returns to an appropriate benchmark to see if my judgement was adding any value over simply buying a broad market index fund. My portfolio outperformed for a few years until it didn’t. In 2015, I had enough and switched to an index investing strategy. Now I invest in Vanguard’s All Equity ETF (VEQT) across all of my accounts.
New investors who started trading stocks in the past 18 months have likely had a similar experience. Stocks crashed hard in March 2020, falling 30%+ from the previous month’s all-time highs. Since then markets have been on an absolute tear. The S&P 500 is up 91% from the March 2020 lows. The S&P/TSX 60 is up 70%.
That’s just country specific market indexes, mind you. Since March 2020 individual stocks like Facebook and Apple are up 137% and 155% respectively. Tesla is up 700%. Meme stock darlings AMC and GameStop are up 1,045% and 3,621% respectively.
No doubt, unless they’ve done something disastrous, new investors participating in this market have seen incredible returns so far.
This can lead to overconfidence – when people’s subjective confidence in their own ability is greater than their objective (actual) performance.
Overconfident Investors
Larry Swedroe says the biggest risk confronting most investors is staring at them in the mirror. This is the first type of overconfident investor.
Overconfidence causes investors to trade more. It helps reinforce a belief that any investment wins are due to skill while any failures are simply bad luck. According to Swedroe, individual investors tend to trade more after they experience high stock returns.
Overconfident investors also take on more uncompensated risk by holding fewer stock positions.
Furthermore, overconfident investors tend to rely on past performance to justify their holdings and expectations for future returns. But just because stocks have soared over the past 18 months doesn’t mean that performance will continue over the next 18 months.
In fact, you should adjust your expectations for future returns – especially for individual stocks that have increased by 100% or more. No stock, sector, region, or investing style stays in favour forever. If you tilt your portfolio to yesterday’s winners (US large cap growth stocks) there’s a good chance your portfolio will underperform over the next decade.
The second type of overconfident investor is one who makes active investing decisions based on a strong conviction about how future events will unfold.
Think back to the start of the pandemic. As businesses shut down around the world it seemed obvious that global economies would suffer and fall quickly into a massive recession. The stock market crash reinforced that idea. Investors hate uncertainty, but this time it seemed a near certainty that stock markets would continue to fall and remain in a prolonged bear market.
Markets quickly turned around as central banks and governments doled out massive stimulus to keep their economies afloat and their citizens safe at home. Now it became ‘obvious’ that investing in sectors like groceries, cleaning supplies, online commerce, and video technology would produce strong results. Continue Reading…


 Posted By
 Posted By
 Posted By